Key Highlights
- The U.S. 10-year Treasury yield briefly touched 5.2% on Thursday before settling at 5.163%, driven by Middle East conflict pushing oil and diesel prices higher and complicating the global inflation outlook.
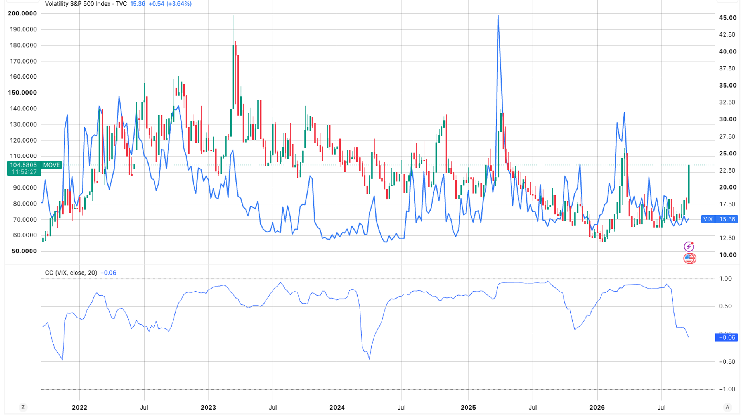
- The ICE BofA MOVE Index ($MOVE) shows bond traders are paying significantly more for interest-rate volatility protection despite the S&P 500 rising roughly 21% since March when $MOVE was last at similar levels.
- The 20-day correlation between the VIX and $MOVE turned negative (-0.06) for the first time since April 2024, while the BVIV-$MOVE correlation sits at -0.37, indicating a historic divergence between equity and bond volatility expectations as Bitcoin’s implied volatility hovers near yearly lows.
Global Bond Yields Surge Amid Middle East Tensions
A broad-based climb in government bond yields is rippling through global markets this week, with the benchmark U.S. 10-year Treasury yield briefly piercing the 5.2% threshold on Thursday before retreating slightly to 5.163%. The selloff in fixed income comes as the widening conflict in the Middle East drives crude oil and diesel prices higher, injecting fresh uncertainty into the inflation outlook and prompting traders to reassess how much further major central banks may need to tighten monetary policy. The move underscores the fragile nature of the disinflation narrative that had previously anchored market expectations for rate cuts.
MOVE Index Signals Rising Rate Volatility Premium
The ICE BofA MOVE Index, a widely watched gauge of expected volatility in U.S. Treasury markets, has climbed to levels last seen in March. However, the equity market backdrop has shifted dramatically: the S&P 500 stood near 6,350 when $MOVE previously traded at this level, but the index has since surged to 7,704, a gain of approximately 21%. This divergence highlights a critical shift—bond traders are now paying a considerably higher premium for protection against interest-rate swings even as equity markets rally, suggesting fixed-income participants see risks that stock investors are currently disregarding.
Correlation Breakdown Between Asset Class Volatility
The structural relationship between equity and bond volatility measures is showing signs of fracture. Over a 20-day rolling window, the correlation between the Cboe Volatility Index (VIX) and the MOVE Index has slipped to -0.06, turning negative for the first time since April 2024, though the reading remains statistically close to zero. The correlation between the Cboe Bitcoin Volatility Index (BVIV) and $MOVE is more distinctly negative at -0.37, marking one of its lowest readings in years. This decoupling occurs as bond volatility rises while Bitcoin’s expected volatility remains anchored near its yearly low, a dynamic that challenges traditional cross-asset hedging assumptions.
Bitcoin’s Detachment from Yield Narrative
Adding to the complexity, recent analysis from CoinDesk indicates that rising yields alone have demonstrated little consistent relationship with Bitcoin’s returns. The cryptocurrency’s implied volatility, as measured by BVIV, has failed to respond to the spike in rate volatility, remaining near annual lows. This suggests that Bitcoin is currently trading on idiosyncratic drivers—such as ETF flow dynamics and regulatory developments—rather than macroeconomic interest-rate sensitivity, further isolating the digital asset from traditional fixed-income turbulence.
Why This Matters
The simultaneous rise in bond yields and volatility premiums, coupled with a breakdown in cross-asset correlations, signals a potential regime shift for multi-asset portfolios. For institutional investors, the negative VIX-MOVE correlation undermines the traditional negative equity-bond correlation that has underpinned 60/40 portfolio construction for decades. The fact that Bitcoin volatility remains suppressed while rate volatility spikes suggests the asset is not currently functioning as a macro hedge against inflation or rate uncertainty. Market participants should monitor whether the $MOVE index sustains these elevated levels, as persistent bond volatility could force a repricing of risk assets broadly, including equities and digital assets, particularly if the Federal Reserve signals a higher-for-longer rate stance in response to energy-driven inflation pressures.
Frequently Asked Questions
What is the MOVE Index and why is it important?
The ICE BofA MOVE Index ($MOVE) measures the implied volatility of U.S. Treasury securities across the 2-, 5-, 10-, and 30-year maturities. It serves as the bond market’s equivalent of the VIX, reflecting how much traders are paying to hedge against interest-rate swings. A rising $MOVE indicates growing uncertainty about the path of monetary policy and inflation.
Why has the correlation between VIX and MOVE turned negative?
The 20-day correlation between the VIX (equity volatility) and MOVE (bond volatility) fell to -0.06, its first negative reading since April 2024. This suggests equity traders are complacent—pricing in a soft landing and continued rally—while bond traders are hedging aggressively against sticky inflation and higher-for-longer rates, creating a rare divergence in risk perception across asset classes.
Is Bitcoin acting as a hedge against rising yields?
According to CoinDesk’s analysis, rising yields alone have shown little consistent relationship with Bitcoin’s returns. Currently, Bitcoin’s implied volatility (BVIV) is near yearly lows while bond volatility ($MOVE) spikes, and the BVIV-MOVE correlation sits at -0.37. This indicates Bitcoin is not currently functioning as a macro hedge against interest-rate volatility.
Leave a Reply