Author: Evan Mercer

  • XRPL’s New Lending Tool Could Lock Up XRP From Minutes to Decades

    XRPL’s New Lending Tool Could Lock Up XRP From Minutes to Decades

    Key Highlights

    • The XRP Ledger Foundation released xrpld 3.4.0 on September 16 with LendingProtocolV1_1, introducing closed-ended vaults with fixed subscription, investment, and redemption periods and cash-basis interest accounting.
    • Deposited assets in closed-ended vaults are locked during the investment phase, which can range from 60 seconds to just under 30 years, while interest is recognized only when borrowers actually pay it.
    • Both the base LendingProtocol and SingleAssetVault amendments remain below the 28-of-35 validator threshold required for activation, meaning the features are not yet live on the mainnet.

    XRP Ledger 3.4.0 Introduces Structured Lending With Fixed-Term Vaults

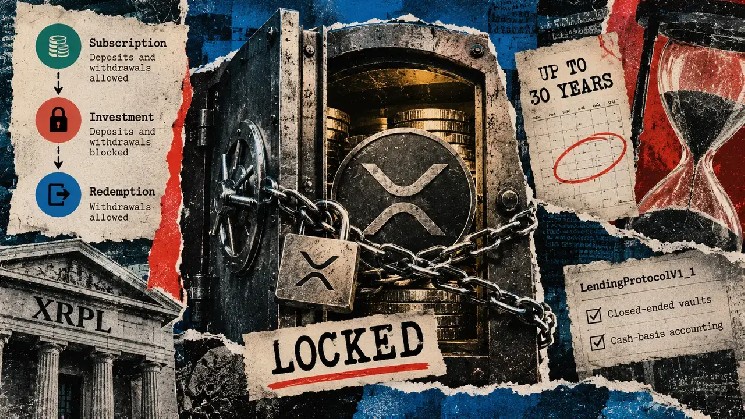
    The XRP Ledger Foundation shipped xrpld version 3.4.0 on September 16, embedding the LendingProtocolV1_1 code path that defines a new generation of closed-ended lending vaults. The release adds two structural changes: a fixed calendar that locks depositor capital for a predetermined term, and a shift to cash-basis accounting that records interest income only when borrowers make payments. Together, these changes aim to make the risk-return profile of on-ledger lending more transparent for participants.

    Unlike open-ended pools that allow continuous deposits and withdrawals, the new closed-ended vaults move through three distinct phases. At creation, the vault sets a SubscriptionDate and a RedemptionDate that remain immutable. During the subscription window, depositors may add assets and redeem shares freely. Once the investment phase begins, the protocol blocks new deposits and withdrawals, committing the vault’s capital to loan funding. Only when the redemption date arrives can depositors withdraw their share of the proceeds. The investment period must be at least 60 seconds and strictly less than 30 years, providing a wide but bounded range for term design.

    Cash-Basis Accounting Separates Expected From Realized Returns

    The accounting overhaul addresses a longstanding ambiguity in how vault income is reported. Under the prior whole-life model, scheduled interest could be booked at loan origination, before the borrower delivered any cash. A missed payment would then force the system to unwind income that had already appeared in the vault’s net asset value. The LendingProtocolV1_1 implementation stamps newly created vaults with a cash-basis accounting version, recognizing interest strictly as borrowers pay it. Vaults created under the earlier rules permanently retain legacy whole-life accounting, ensuring backward compatibility without forced migration.

    For depositors, the practical effect is a cleaner separation between a claim on a borrower and realized vault income. Scheduled payments remain off-balance-sheet receivables until cash arrives, making the reported asset value less dependent on money that has not yet been received. The change also alters how much debt a broker appears to carry against protocol limits, because future interest no longer enters the total at origination. This may create additional headroom for new loans under the protocol’s measurements, though actual utilization still depends on real borrowers and funding.

    Amendment Governance Remains the Critical Gate

    Despite the code being present in the 3.4.0 release, the features are not yet accessible on the live network. A dashboard snapshot fetched on September 17 showed the base LendingProtocol amendment at 13 of 35 trusted-validator votes and SingleAssetVault at 16 of 35, both below the displayed activation threshold of 28. The LendingProtocolV1_1 amendment itself did not appear in the responding node’s feature feed, nor was an activation countdown visible. Network governance therefore remains the first measurable hurdle: the amendments must become visible, attract sufficient validator support, and complete the two-week activation window before any vault can be created.

    Single-asset vaults can denominate their principal in XRP, an issued trust-line token, or a Multi-Purpose Token. This flexibility means that lasting XRP demand from the lending system depends entirely on later choices by application developers, borrowers, and depositors. Moving already-owned XRP into a vault produces a visible locked balance without requiring a market purchase, and applications could build lending pools around issued assets while leaving XRP outside the principal flow entirely.

    Why This Matters

    The introduction of closed-ended vaults and cash-basis accounting represents a maturation of the XRP Ledger’s native lending architecture. By enforcing a visible commitment period and recognizing income only upon receipt, the protocol reduces the opacity that can obscure credit risk in decentralized lending markets. However, the economic significance for XRP holders hinges on adoption metrics that have yet to materialize: the number of XRP-denominated vaults created, the volume of XRP deposited, loan origination activity, repayment performance, and whether depositors renew after the first redemption cycle. Until those on-chain indicators emerge, the system’s capacity to generate sustained demand for XRP—beyond a temporary liquidity sink—remains an open question. The next concrete milestones are the amendment activation process and the subsequent launch of application-level lending products that choose XRP as their principal asset.

    Frequently Asked Questions

    When will the new lending features be available on the XRP Ledger mainnet?
    The features require the LendingProtocol and SingleAssetVault amendments to reach a 28-of-35 validator supermajority and complete a two-week activation period. As of September 17, voting stood at 13 and 16 respectively, with LendingProtocolV1_1 not yet visible in the feature feed.
    Can depositors withdraw their assets early from a closed-ended vault?
    No. Once the investment phase begins at the SubscriptionDate, the protocol blocks all deposits and withdrawals until the RedemptionDate. The lock is enforced at the protocol level for the full term, which can range from 60 seconds to just under 30 years.
    Does this update create new demand for XRP?
    Not automatically. The vault design supports XRP, issued trust-line tokens, and Multi-Purpose Tokens as principal assets. Sustained XRP demand would require applications to select XRP for their vaults, borrowers to seek XRP-denominated credit, and depositors to repeatedly fund and renew positions after observing repayment performance.
  • FCA Targets Three London Sites in Renewed P2P Cryptocurrency Trading Crackdown

    FCA Targets Three London Sites in Renewed P2P Cryptocurrency Trading Crackdown

    Key Highlights

    • The Financial Conduct Authority (FCA), HM Revenue & Customs (HMRC), and the Metropolitan Police conducted a joint enforcement action against three peer-to-peer (P2P) cryptocurrency trading locations in London, issuing cease-and-desist letters.
    • No P2P crypto trading businesses are currently registered with the FCA in the UK, meaning any operator conducting P2P trading by way of business is doing so illegally and outside anti-money laundering safeguards.
    • The operation marks an escalation in the UK’s regulatory stance, following the FCA’s action six months ago against HTX (formerly Huobi), where major app stores were asked to restrict access for UK consumers.

    FCA Leads Coordinated Raids on Unregistered London Crypto Venues

    The Financial Conduct Authority has significantly escalated its enforcement posture toward cryptocurrency businesses operating outside the regulatory perimeter. In a coordinated operation with HM Revenue & Customs and the Metropolitan Police Service, the FCA targeted three physical peer-to-peer crypto trading locations in London, handing operators formal cease-and-desist letters. The action signals a decisive shift from warnings to active disruption of unregistered venues that facilitate direct crypto transactions between individuals on a commercial basis.

    Under the UK’s Money Laundering, Terrorist Financing and Transfer of Funds (Information on the Payer) Regulations 2017, any entity conducting P2P crypto trading by way of business must register with the FCA. Personal, non-commercial transactions between individuals do not require registration. However, the regulator confirmed that as of the enforcement date, there are zero registered P2P crypto businesses operating in the United Kingdom. This regulatory vacuum means every commercial P2P venue currently operating is doing so without the mandatory oversight designed to detect and prevent money laundering.

    Regulators Warn of Unrelenting Scrutiny for Non-Compliant Operators

    The FCA’s executive director of enforcement and market oversight, Steve Smart, issued a direct warning to the sector:

    Anyone running an unregistered peer-to-peer crypto business should assume we are looking at them.

    The Metropolitan Police underscored the law enforcement rationale behind the crackdown. Sathish Alalasundaram of the Metropolitan Police Service stated:

    As criminals continue to adapt their methods, the Met Police continues to evolve and adapt our investigative capabilities…

    The joint operation reflects growing concern that unregistered P2P venues serve as critical infrastructure for illicit finance, enabling the conversion of criminal proceeds into cryptocurrency without the transaction monitoring, customer due diligence, and suspicious activity reporting obligations that registered firms must follow.

    Escalation Follows HTX App Store Restrictions

    The London raids represent the next phase in a hardening regulatory trajectory that began approximately six months ago. In that earlier action, the FCA moved against HTX (formerly known as Huobi), resulting in major mobile app stores being asked to restrict access for UK consumers. That case established a precedent for using distribution channels—app stores—as enforcement levers against non-compliant crypto firms. The current operation extends that logic to physical trading venues, demonstrating a multi-vector approach that targets both digital and brick-and-mortar touchpoints.

    The message from regulators is consistent: the era of regulatory forbearance for crypto businesses operating without registration has ended. The focus has evolved from offshore exchanges to domestic P2P operators, but the core requirement remains unchanged—any firm conducting cryptoasset activity by way of business in the UK must be registered and supervised.

    Why This Matters

    The UK’s approach to crypto regulation has historically been characterized by a registration regime rather than a licensing framework, placing the onus on firms to demonstrate compliance with anti-money laundering (AML) standards before operating. The absence of any registered P2P operators highlights a systemic compliance gap: either the business model is incompatible with current AML requirements, or operators have chosen to remain outside the regulatory perimeter. The FCA’s willingness to deploy law enforcement partnerships and physical enforcement actions suggests a strategic pivot toward disruption as a deterrent. For the industry, the implications are clear—regulatory tolerance for “wait-and-see” approaches has evaporated. For consumers, the action removes venues that offered no statutory protections, no access to the Financial Ombudsman Service, and no Financial Services Compensation Scheme coverage. The next steps will likely include further site actions, potential criminal referrals for persistent offenders, and continued pressure on ancillary service providers—such as payment processors and landlords—to avoid facilitating unregistered activity.

    Frequently Asked Questions

    What is peer-to-peer crypto trading and when does it require FCA registration?

    Peer-to-peer crypto trading involves individuals buying and selling cryptocurrency directly with each other, often facilitated by a platform or physical venue. In the UK, registration with the FCA is mandatory only when P2P trading is conducted “by way of business”—meaning on a commercial, habitual, or professional basis. Personal, non-commercial transactions between individuals do not require registration.

    Are there any legally operating P2P crypto businesses in the UK currently?

    No. The FCA has confirmed that as of the enforcement action, there are zero registered P2P crypto businesses operating in the United Kingdom. Any commercial P2P venue currently operating is doing so without the required registration and outside the regulatory safeguards designed to prevent money laundering.

    What happens to businesses that ignore the cease-and-desist letters?

    While the source does not specify next steps for non-compliance, the involvement of the Metropolitan Police and HMRC indicates that continued operation could lead to criminal investigation, asset seizure, prosecution under the Money Laundering Regulations, and potential court orders to shut down premises. The FCA has signaled that enforcement will be persistent and multi-agency.

  • NEAR Surges 21% on Launch of Historic Confidential Perps Powered by Hyperliquid

    NEAR Surges 21% on Launch of Historic Confidential Perps Powered by Hyperliquid

    Key Highlights

    • Near Protocol launches the industry’s first “Confidential by Default” perpetuals trading, masking all position details including asset types, sizes, entry times, and trading direction.
    • The feature runs on Near’s multi-chain Confidential Intents pipeline, which recently surpassed $70 million in total value locked (TVL), with Hyperliquid serving as the chief execution and liquidity layer.
    • NEAR token surges 21.36% to $3.21 while HYPE gains 10.82% to $86.72 following the announcement and Kraken parent Payward’s plans to bring Hyperliquid to the US market.

    Near Protocol Pioneers Confidential Perpetuals Trading on Blockchain

    Near Protocol has unveiled what it describes as the decentralized finance industry’s first “Confidential by Default” perpetuals trading environment, a development that directly addresses a fundamental tension in blockchain architecture: the conflict between radical transparency and competitive trading execution. The new feature, accessible via near.com, completely obscures all perpetual position data—including asset types, position sizes, entry timestamps, and directional bias—from public view.

    While transparency remains a foundational principle of blockchain technology, Near’s development team argues that complete visibility creates structural disadvantages for significant market participants. The protocol identifies three specific vulnerabilities inherent in fully transparent order books: front-running by on-chain bots that detect pending orders and execute ahead of them, strategy copying that allows competitors to mirror profitable approaches, and forced liquidations where malicious actors target public liquidation prices to push traders out of positions.

    Technical Architecture and Strategic Partnerships

    The confidential perpetuals infrastructure operates on Near’s multi-chain Confidential Intents pipeline, which recently achieved a $70 million total value locked milestone. The system combines high-speed execution with selective disclosure capabilities designed to satisfy regulatory compliance requirements. Integration with Circle’s USDC stablecoin enables inter-agentic payments, while Hyperliquid functions as the primary execution and liquidity layer, providing access to over 50 perpetual markets with leverage up to 40x.

    This architecture effectively merges the privacy characteristics traditionally associated with centralized exchanges—where order books and position data remain opaque—with blockchain’s core value propositions of speed, decentralization, and non-custodial asset control.

    Why This Matters: The Evolving Privacy Landscape in DeFi

    Near’s launch reflects accelerating industry demand for private transaction capabilities that maintain regulatory compliance. The competitive landscape now includes Ethereum-based confidential DeFi yield vaults, optional privacy wrappers from platforms such as Zama and Fhenix, and Cardano’s Midnight chain which offers what its developers term “rational privacy.” Each approach represents a different philosophical and technical solution to the privacy-transparency spectrum.

    However, Near’s confidential perpetuals trading remains restricted in the United States and Canada due to regulatory considerations, highlighting the ongoing tension between privacy-preserving financial infrastructure and jurisdictional compliance requirements. The geographic limitation underscores that technical innovation in this space continues to outpace regulatory clarity.

    Market Response and Price Action

    Following the announcement, NEAR token appreciated 21.36% intraday to trade at $3.21, according to CoinMarketCap data. The move coincides with broader sector rotation toward artificial intelligence-linked crypto assets. Technical analysis suggests that if NEAR maintains support above $3.00, the token could retest the $3.33 incentive threshold, while a break below $2.80 might trigger a decline toward the $2.57 Fibonacci support level.

    Simultaneously, HYPE token—native to the Hyperliquid ecosystem—gained 10.82% to reach $86.72 after Kraken’s parent company Payward announced plans to introduce Hyperliquid to the United States market, potentially expanding the protocol’s regulatory footprint and user base.

    Frequently Asked Questions

    What makes Near’s perpetuals trading “Confidential by Default”?

    All perpetual position data—including asset types, position sizes, entry times, and trading direction—is automatically masked from public view without requiring users to opt into privacy features.

    Which partners power the execution and liquidity for Near’s confidential perpetuals?

    Hyperliquid serves as the chief execution and liquidity layer, providing access to over 50 perpetual markets with up to 40x leverage, while USDC integration enables stablecoin settlements.

    Is Near’s confidential perpetuals trading available to users in the United States?

    No, the service remains restricted in the US and Canada due to regulatory reasons, despite the underlying technical infrastructure being operational globally.

  • Industry Doubts Democrats’ Effort to Restart Stalled CLARITY Act Talks: ‘It’s all talk!’

    Industry Doubts Democrats’ Effort to Restart Stalled CLARITY Act Talks: ‘It’s all talk!’

    Key Highlights

    • Moderate Senate Democrats led by Kirsten Gillibrand and Ruben Gallego pledged renewed bipartisan talks on the CLARITY Act after a 49-50 procedural vote failure.
    • Prediction markets assign less than a 30% probability of passage within two years, while JPMorgan analysts see a narrow but existing legislative window.
    • SEC Chair Paul Atkins and CFTC leaders committed to fast-tracking rulemaking to provide regulatory certainty regardless of legislative outcome.

    Moderate Democrats Vow Renewed Push After CLARITY Act Stalls

    A coalition of moderate Senate Democrats, spearheaded by Senators Kirsten Gillibrand and Ruben Gallego, signaled determination to revive the stalled CLARITY Act following a procedural defeat that underscored deep partisan fractures over digital asset regulation. The legislation, which has been under negotiation for approximately two years, failed to advance on a 49-50 vote after Democrats uniformly blocked the procedural step required to proceed. Notably, seven moderate Democrats who were anticipated to support the measure withheld their votes, citing insufficient ethics provisions as the primary objection.

    This week was a setback, but not the end of that important work. We remain committed to working in a bipartisan fashion to get this legislation passed.

    According to reporting by Eleanor Terrett, the commitment to new talks follows intensive behind-the-scenes efforts to reignite negotiations and potentially fast-track the crypto legislation before the current congressional session concludes. However, the path forward remains highly uncertain, with prediction market platform Kalshi assigning less than a 30% probability of enactment over the next two years.

    Industry Skepticism and Analyst Perspectives

    The Democrats’ recommitment has been met with pronounced skepticism from segments of the crypto industry and pro-crypto analysts. Nate Geraci, a prominent industry observer, characterized the renewed bipartisan rhetoric as “all talk” devoid of substantive action, drawing a sharp contrast with the regulatory posture of the previous administration.

    All talk at this point…There was no ‘working in a bipartisan fashion’ on crypto during the Biden admin. It was purely anti-crypto & regulation by enforcement. So it’s all talk. Actions speak louder than words.

    Despite the legislative impasse, JPMorgan analysts maintain that the bill is not definitively dead, identifying a narrow window for potential passage. This assessment reflects the complex legislative calculus where bipartisan cooperation remains theoretically possible but politically fraught, particularly given the ethics provisions that drove Democratic opposition.

    Regulatory Agencies Pivot to Rulemaking

    In a significant development for market participants, both the Securities and Exchange Commission and the Commodity Futures Trading Commission have pledged to accelerate rulemaking initiatives to establish clear regulatory frameworks for the digital asset sector. This administrative pivot aims to provide a degree of certainty that the legislative process has thus far failed to deliver.

    I have been unequivocal: with or without legislation, we will act decisively within the SEC’s statutory authority to deliver certainty for American investors.

    SEC Chair Paul Atkins’ declaration underscores the agency’s intent to utilize existing statutory authority to address regulatory gaps. The CFTC has echoed this commitment to expedited rulemaking. However, industry participants face a critical unresolved question: whether the next administration will uphold, modify, or reverse these forthcoming regulatory frameworks, introducing a new layer of policy uncertainty.

    Why This Matters

    The CLARITY Act’s stall represents more than a single legislative failure; it encapsulates the broader struggle to define a coherent federal framework for digital assets in the United States. With Congress deadlocked, the locus of regulatory action has shifted decisively to the SEC and CFTC, placing immense importance on the rulemaking agendas of Chair Atkins and his CFTC counterparts. For market participants, the immediate practical impact is a reliance on administrative rulemaking rather than statutory clarity—a dynamic that introduces durability risks should political winds shift after the next election cycle. The narrow legislative window identified by JPMorgan suggests that the lame-duck period or early next session may represent the last best chance for a comprehensive statutory solution before regulatory policy becomes entirely dependent on executive branch interpretation.

    Frequently Asked Questions

    Why did the CLARITY Act fail to advance in the Senate?

    The bill failed on a 49-50 procedural vote after all Democrats, including seven moderate senators expected to support it, voted against advancing the legislation. They cited insufficient ethics provisions as the reason for their opposition.

    What is the likelihood of the CLARITY Act passing in the near future?

    Prediction market Kalshi assigns less than a 30% probability of passage within the next two years. JPMorgan analysts believe the bill is not dead but face a narrow window for enactment.

    How will the SEC and CFTC respond to the legislative stall?

    Both agencies have committed to fast-tracking rulemaking to provide regulatory certainty. SEC Chair Paul Atkins stated the SEC will act decisively within its statutory authority “with or without legislation” to deliver clarity for investors.

  • CFTC Exempts Crypto and Prediction Markets Software Providers from Broker Classification

    CFTC Exempts Crypto and Prediction Markets Software Providers from Broker Classification

    Key Highlights

    • The CFTC issued a no-action letter exempting eligible crypto and prediction market software providers from broker registration requirements, provided they maintain zero trade discretion, never hold user assets, and avoid volume-based commissions.
    • The relief builds on a March precedent granting Phantom Technologies no-action relief, allowing Phantom Wallet to partner with Kalshi as a non-custodial passive interface without registering as an introducing broker.
    • The move comes alongside the SEC’s new “Innovation Exemption” for on-chain tokenized stock trading and UK FCA guidance on crypto authorization, signaling multi-jurisdictional regulatory momentum despite the Clarity Act’s Senate defeat.

    CFTC Grants Broad No-Action Relief for Non-Custodial Software Providers

    The U.S. Commodity Futures Trading Commission (CFTC) has issued a sweeping no-action letter that exempts eligible cryptocurrency and prediction market software developers from the requirement to register as brokers. The announcement, made today, establishes a formal regulatory safe harbor for developers who operate as passive, non-custodial interfaces connecting users to regulated trading platforms. A “no-action” position represents an official regulator statement that it will not pursue enforcement actions against an entity for a specific activity, providing critical legal certainty in a sector long plagued by ambiguity.

    Strict Conditions Define the Safe Harbor

    The relief is conditional and narrowly tailored to preserve user sovereignty and prevent conflicts of interest. To qualify, a developer must maintain zero discretion over trades, ensuring the user retains absolute control over every transaction. The developer must never assume custody of users’ assets at any point. Critically, the developer is banned from taking volume-based dynamic commissions, meaning they cannot take a “cut” of the trading volume passing through their software. These guardrails are designed to distinguish passive technology providers from active intermediaries who manage risk or hold funds.

    Phantom Technologies Precedent Paves the Way

    The CFTC’s decision codifies a precedent set in March when the agency granted its first no-action position to a passive software provider, Phantom Technologies. That relief allowed Phantom Wallet to integrate with Kalshi, a regulated prediction market platform, operating strictly as a non-custodial, passive interface without registering as an introducing broker. Phantom CEO Brandon Millman welcomed today’s broader policy on X, stating: “In March, Phantom became the first passive software provider to receive no-action relief from the CFTC. We’re grateful to the CFTC for working with us to chart a new path for non-custodial software providers to connect people with regulated markets, all while the provider never…”

    Industry Adoption and Parallel Regulatory Moves

    Major prediction market operators including Crypto.com and ProphetX have reportedly adopted similar non-custodial partnership models to expand their reach while remaining within the new legal provisions. The CFTC’s action arrives amid a flurry of regulatory developments. Earlier this week, the Clarity Act failed to secure a majority on the Senate floor, yet agencies continue to fill the void. Today, the U.S. Securities and Exchange Commission (SEC) unveiled its “Innovation Exemption” rule, permitting the on-chain trading of certain tokenized stocks. Simultaneously, the UK Financial Conduct Authority (FCA) published guidance clarifying which crypto activities require formal authorization, reflecting a coordinated international effort to define the regulatory perimeter.

    Why This Matters

    The CFTC’s no-action letter represents a significant inflection point for decentralized finance (DeFi) infrastructure and prediction markets in the United States. By explicitly legitimizing non-custodial front-end software, the regulator has removed a major legal overhang that discouraged developers from building interfaces for regulated markets. This bridges the gap between user-friendly, self-custodial wallets and compliant, exchange-based liquidity. The parallel moves by the SEC and UK FCA suggest a maturing global regulatory approach that favors activity-based, risk-proportionate rules over blanket prohibitions. For users, the immediate benefit is access to regulated prediction markets and tokenized assets through familiar, non-custodial wallets without surrendering control of private keys. For the industry, it establishes a viable compliance pathway that could unlock a wave of institutional-grade product development on public blockchains.

    Frequently Asked Questions

    What specific activities does the CFTC no-action letter cover?

    The letter covers software developers who partner with regulated platforms to provide non-custodial interfaces for crypto and prediction market trading. The developer must have zero trade discretion, never hold user assets, and cannot charge volume-based commissions or take a “cut” of trading volume.

    How does this differ from the Phantom Technologies relief granted in March?

    The March relief was a company-specific no-action letter for Phantom Technologies to operate with Kalshi. Today’s announcement establishes a general, reusable framework that any eligible developer meeting the stated conditions can rely upon, rather than requiring individual applications.

    Does this mean all crypto wallet providers are now exempt from registration?

    No. The exemption applies only to developers meeting all three strict conditions: zero trade discretion, non-custodial architecture, and no volume-based fees. Wallets that custody assets, execute trades on behalf of users, or charge percentage-based fees on volume do not qualify and remain subject to existing registration requirements.

  • MemeToro AI Agent Explained: Capabilities and Limits in Memecoin Launches

    MemeToro AI Agent Explained: Capabilities and Limits in Memecoin Launches

    Key Highlights

    • MemeToro’s presale architecture separates AI-driven research from immutable smart contract enforcement, preventing any single entity from altering token allocations or fund flows after launch.
    • The platform’s validator layer automatically rejects proposals with uncollected sources, invalid allocation totals, insider allocations, or conflicting funding terms before they reach the blockchain.
    • $MT token utility spans funding access, staking yield, memecoin trading, and prediction markets, contingent on the platform achieving live status and sustained user adoption.

    AI Agents as Researchers, Not Rulers

    MemeToro has structured its AI crypto presale model around a strict division of labor: artificial intelligence handles research and proposal drafting, while hard-coded smart contracts enforce financial rules without exception. The platform’s AI agent scans trend data, news feeds, and social signals to produce a launch manifest that explains a proposed token’s rationale, evidence base, and initial terms including supply, price, contribution cap, and fixed-rate funding conditions. This output gives prospective participants a transparent window to inspect a launch before committing capital. However, the system explicitly acknowledges that the AI offers no guarantee of post-launch attention or value retention, and its recommendations remain vulnerable to poor data quality, manipulated social content, and prompt-injection attacks.

    Smart Contracts as Immutable Guardrails

    Where the AI proposes, the validator checks, and the smart contracts enforce. MemeToro’s validator is designed to reject any proposal that includes uncollected source links, invalid allocation totals, non-zero insider allocations, or conflicting funding terms. The fair-launch escrow draft operates without an owner, admin role, or upgrade path, meaning that once deployed, the contract cannot be altered by the AI agent, the founding team, or any external actor. An agent cannot override a locked allocation or disabled admin function if the contract is correctly written and deployed, though the project emphasizes that the contract code itself must still undergo independent testing and review. Early contract code has been published, but the full presale process remains under active development.

    Off-Chain Risks Demand On-Chain Verification

    The project identifies the primary attack surface as off-chain: malicious links, false data, prompt injection, and coordinated social manipulation can all distort an AI agent’s recommendation before any transaction reaches the blockchain. MemeToro’s countermeasure is to require every proposal to cite collected sources and pass deterministic, rule-based checks before validation. This approach aims to close the gap between automated research and trustless execution. The $MT token is intended to serve as the ecosystem’s settlement asset, supporting funding access, staking rewards, memecoin trading, and prediction markets, though its long-term utility depends entirely on the platform launching successfully and attracting ongoing user activity.

    Buying $MT Follows a Fixed, Repeatable Process

    Participation in the presale follows a standardized flow regardless of payment method: users locate the buy button on the official website, which launches the presale smart contract; confirm their wallet is pointed to BNB Chain; select a supported cryptocurrency or card payment; and authorize the transaction to receive $MT in their balance. The token is positioned not as a one-time presale asset but as a persistent utility instrument across the MemeToro ecosystem. Official channels for updates include the website at memetoro.com, X at @memetoro_mt, Telegram at t.me/memetoro_mt, and a YouTube overview at youtube.com/watch?v=gY0jgWy_DtA.

    Why This Matters

    The MemeToro model addresses a structural tension in AI-assisted token launches: the speed and scale of automated research versus the irreversibility of on-chain financial commitments. By confining AI to a propose-only role and embedding enforcement in ownerless, non-upgradeable contracts, the platform attempts to eliminate the “admin key” risk that has plagued numerous crypto projects. The validator’s deterministic checks—rejecting insider allocations and unverified sources—introduce a layer of programmatic due diligence that is rare in memecoin launches. However, the system’s security ultimately rests on the quality of off-chain data inputs and the rigor of independent contract audits, neither of which are complete. For participants, the takeaway is clear: the architecture limits centralized control, but does not eliminate the need for personal verification of source data and contract code before committing funds.

    Frequently Asked Questions

    Can the MemeToro AI agent change token allocations or move funds after a presale starts?
    No. The AI agent is restricted to researching trends and drafting proposals. Once a presale is deployed, the ownerless smart contract enforces fixed terms without admin override capability, preventing any entity—including the AI—from altering allocations or accessing contributor funds.
    What checks does the validator perform before a proposal reaches the blockchain?
    The validator rejects proposals that lack collected source links, contain invalid allocation totals, include any insider allocation above zero, or present conflicting funding terms. Only proposals passing all deterministic checks proceed to contract deployment.
    What utilities does the $MT token provide beyond presale access?
    $MT is designed as the ecosystem’s settlement asset, enabling staking for yield, access to upcoming trading products, participation in memecoin trading and prediction markets, and ongoing platform governance once the full suite of services goes live.
  • How Binance Lists Crypto Presales: The Exchange Listing Process Explained

    How Binance Lists Crypto Presales: The Exchange Listing Process Explained

    Key Highlights

    • MemeToro’s Stage 7 $MT presale has raised over $135,000, but the token is not listed on Binance and no official listing announcement has been made.
    • The displayed $0.05186 launch-price target represents a ~12x multiple of the Stage 7 price ($0.00430) and is a numerical comparison only—not a guaranteed market price or confirmation of a centralized exchange listing.
    • MemeToro’s roadmap prioritizes a decentralized exchange (DEX) launch on BNB Chain via PancakeSwap; token deployment, liquidity provision, factory contracts, testnet validation, and independent review remain pending.

    Presale Mechanics vs. Exchange Listings: Understanding the Gap

    During a crypto presale, a project sells tokens under its own round terms—often at a fixed-stage price—without an open order book where buyers and sellers determine a real-time market price. MemeToro’s current Stage 7 sale follows this model: the project has raised more than $135,000 for its $MT token, yet the asset remains unavailable on Binance or any other centralized exchange (CEX). The project’s published launch-price target of $0.05186 is a mathematical benchmark derived from the presale structure, not a commitment from any trading venue. Investors should treat this figure as a reference point, not a forecast of secondary-market performance.

    MemeToro’s Current Status: Presale Progress and Technical Roadmap

    MemeToro states that its public-sale allocation carries no vesting and is intended to be claimable at launch. However, buyers must wait for official claim instructions and a verified $MT contract address before any tokens can be accessed. The project’s public fair-launch escrow draft outlines a planned plug-in point for token creation and liquidity execution, designed to lock round settings, prohibit insider allocations, and restrict funds to refunds or designated liquidity. Critical infrastructure steps—token deployment, liquidity provisioning, factory contract setup, BNB Chain testnet validation, and independent code review—remain on the roadmap and have not yet been executed.

    Binance Listing Requirements: Why No Presale Token Is Guaranteed Access

    Binance does not list every presale token. Listing decisions involve legal, technical, security, liquidity, community, and market-suitability factors controlled entirely by the exchange. A project typically needs a working token contract, sufficient distribution, reliable market infrastructure, and a product narrative that withstands exchange review. Requirements can change at Binance’s discretion, so no third-party analysis can treat a potential listing as certain without a formal announcement from Binance itself. MemeToro has not issued any such confirmation in the information provided. As the source material advises: do not buy a token because someone claims a Binance listing is “coming soon.” Treat unofficial listing images, anonymous messages, and social-media rumors as unverified.

    DEX Launch Pathway: PancakeSwap and BNB Chain Infrastructure

    Many BNB Chain tokens begin trading on a decentralized exchange such as PancakeSwap, allowing holders to swap through a liquidity pool rather than waiting for a CEX order book. MemeToro’s architecture anticipates this route. A DEX launch can establish an initial market price, but it does not guarantee deep liquidity, low slippage, or stable trading conditions. The open-market price may move significantly above or below any presale target depending on circulating supply, buyer and seller behavior, and the platform’s ability to deliver its planned utility—including access, funding, staking, rewards, memecoin trading, and prediction markets.

    Why This Matters

    The distinction between a presale, a token generation event (TGE), and an exchange listing is fundamental to investor protection in crypto markets. A TGE merely makes tokens claimable under the project’s rules; it does not trigger exchange trading. Binance and other major CEXes conduct independent due diligence that can take months and may never result in a listing. Meanwhile, DEX launches on chains like BNB Chain provide immediate liquidity access but expose holders to higher volatility and smart-contract risk. MemeToro’s transparent disclosure—no confirmed Binance listing, incomplete technical execution, and a price target framed as a numerical comparison—serves as a case study in how projects should communicate presale risk. Readers should verify contract addresses, claim procedures, and exchange announcements exclusively through official channels before committing capital.

    Frequently Asked Questions

    Is $MT currently listed on Binance?

    No. No confirmed Binance listing has been announced. $MT is currently available only through MemeToro’s direct presale process.

    Does a token generation event (TGE) guarantee an exchange listing?

    No. A TGE and an exchange listing are separate events. A TGE makes tokens claimable per the project’s rules; a CEX listing requires the exchange’s independent approval based on its own criteria.

    Can a DEX market price differ from a presale price target?

    Yes. The open-market price on a DEX like PancakeSwap can move above or below any published target based on liquidity depth, demand, circulating supply, and broader market conditions.

  • Real Stocks Finally Come to Blockchain as SEC Outlines Regulatory Framework

    Real Stocks Finally Come to Blockchain as SEC Outlines Regulatory Framework

    Key Highlights

    • The SEC has introduced an exemption allowing qualifying venues to operate Tokenized Securities Venues (TSVs) where tokenized stocks trade via blockchain-based liquidity pools and smart contracts instead of traditional order books.
    • The framework enables banks, brokers, and crypto firms to experiment with a new market structure for regulated U.S. equities while maintaining regulatory oversight.
    • The exemption does not authorize leverage or lending activities on TSVs, focusing strictly on trading and settlement innovation.

    SEC Opens Door for Blockchain-Based Stock Trading Venues

    The U.S. Securities and Exchange Commission has established a regulatory pathway that could fundamentally reshape how equities trade in the United States. Under a new exemption, qualifying platforms designated as Tokenized Securities Venues (TSVs) can facilitate trading of tokenized stocks through blockchain-based liquidity pools governed by smart contracts. This marks a significant departure from the conventional exchange model, which has long relied on central limit order books to match buyers and sellers. By permitting this alternative structure, the SEC is effectively allowing the traditional financial industry to test cryptocurrency-native trading infrastructure—specifically automated market makers and on-chain liquidity pools—on regulated U.S. securities.

    How Tokenized Securities Venues Differ From Traditional Exchanges

    In the current market structure, a retail or institutional investor places an order through a broker-dealer, which then routes that order to an exchange where it interacts with a central limit order book. The TSV model upends this workflow. Under the SEC’s exemption, an eligible investor can trade a token representing a regulated stock directly through a blockchain venue. Instead of matching against other orders in a book, the trade executes against a pool of tokenized assets managed by pre-set algorithms or smart contracts. This mechanism mirrors the automated market maker (AMM) model pioneered in decentralized finance, but it operates within a regulated, permissioned framework designed for compliant securities.

    Broader Implications for Settlement and Interoperability

    Industry proponents argue that migrating securities onto blockchain rails unlocks efficiencies beyond the trading venue itself. Tokenized shares could enable faster settlement cycles, seamless movement between compatible financial platforms, and eventual use as collateral in other on-chain transactions. These capabilities stem from the programmable nature of blockchain infrastructure, where ownership transfer and settlement can occur simultaneously—known as delivery-versus-payment—without the multi-day clearing processes typical of legacy systems. However, the SEC’s current exemption is narrowly scoped: it does not permit leverage, lending, or rehypothecation of assets on TSVs, limiting the initial use case to spot trading and settlement.

    Why This Matters

    The SEC’s TSV exemption represents a watershed moment in the convergence of traditional finance and blockchain technology. For years, regulators have maintained a strict separation between crypto markets and regulated securities markets. This framework acknowledges that blockchain-based trading mechanics—particularly liquidity pools and smart-contract execution—may offer legitimate structural advantages for certain asset classes. By creating a controlled sandbox, the SEC allows established financial institutions and crypto-native firms to gather real-world data on liquidity formation, price discovery, and operational risk in a tokenized equity environment. The outcomes of these experiments will likely inform future rulemaking on digital asset securities, custody standards, and the potential modernization of the National Market System. Market participants should watch for the first TSV applications and the types of assets—likely large-cap, highly liquid equities—selected for initial tokenization.

    Frequently Asked Questions

    What is a Tokenized Securities Venue (TSV)?

    A TSV is a qualifying venue approved under the SEC’s exemption that allows investors to trade tokenized representations of regulated U.S. stocks through blockchain-based liquidity pools governed by smart contracts, rather than through a traditional central limit order book.

    Does the SEC exemption allow margin trading or lending on TSVs?

    No. The exemption explicitly does not permit leverage, lending, or rehypothecation of assets on Tokenized Securities Venues. The framework is limited to spot trading and settlement of tokenized equities.

    Who can participate in trading on a TSV?

    Only eligible investors—as defined by the specific venue’s participation criteria and consistent with securities regulations—can trade tokenized stocks on a TSV. The venues themselves must qualify under the SEC’s exemption and operate in a regulated, controlled manner.

  • Ondo Finance Succession Crisis Deepens as Kathleen Allman’s Daughter Alleges ‘dementia’, Alcoholism, Reckless Spending

    Ondo Finance Succession Crisis Deepens as Kathleen Allman’s Daughter Alleges ‘dementia’, Alcoholism, Reckless Spending

    Key Highlights

    • Ondo Finance founder Nathan Allman’s mother, Kathleen Allman, has filed a lawsuit against acting CEO De Bode alleging a “brazen usurpation of corporate control” and a proposed $11 million compensation package drafted days after her son’s death.
    • The disputed package included a $900,000 annual salary, a $1 million signing bonus, 26 million restricted token units valued over $9 million, and equity awards that would have increased De Bode’s stake from 0.33% to roughly 8%.
    • A September 3 court order currently maintains De Bode as acting CEO and board member, despite Kathleen Allman’s attempt to remove him after appointing herself chair and interim CEO alongside daughter Tahnee Towill.

    Leadership Vacuum Triggers Boardroom Battle at Ondo Finance

    The sudden death of Ondo Finance founder Nathan Allman has precipitated a high-stakes corporate governance dispute that now sits before the courts. Following Allman’s passing, De Bode—identified in court filings as the company’s acting chief executive—assumed operational control of the tokenized treasury management firm. The transition, however, was immediately contested by Allman’s mother, Kathleen Allman, who moved swiftly to restructure the board by appointing herself and another of Allman’s children, Tahnee Towill, as directors. Kathleen Allman subsequently named herself board chair and interim chief executive, and moved to strip De Bode of all corporate titles.

    Court Order Preserves Status Quo as Litigation Advances

    Kathleen Allman’s attempt to remove De Bode has been temporarily blocked by a September 3 court order that explicitly preserves his status as acting CEO and board member pending further proceedings. Ondo Finance declined to comment on the matter when contacted, and De Bode did not respond to inquiries. The legal standoff centers on the legitimacy of De Bode’s appointment and the validity of a compensation package that Kathleen Allman’s complaint characterizes as a “brazen usurpation of corporate control.”

    Lawsuit Details Alleged Self-Dealing and Fiduciary Breaches

    The complaint filed by Kathleen Allman paints a picture of rapid self-dealing in the immediate aftermath of her son’s death. According to the filing, De Bode began plotting a new $11 million compensation package within a week of Nathan Allman’s passing. The package, as detailed in the complaint, comprised a $900,000 annual salary and bonus structure, a $1 million signing bonus, and 26 million restricted token units valued at more than $9 million. Additionally, the awards covered 846,000 shares that would have inflated De Bode’s equity stake from a marginal 0.33% to approximately 8%—a roughly 24-fold increase. Vesting for these awards was scheduled to commence on May 25, the day immediately following Allman’s death.

    Chen Appointment and Governance Validity Also Challenged

    The lawsuit extends beyond compensation to challenge the legitimacy of De Bode’s own appointment and his effort to install Chen, described as an early Ondo backer, to the board. Kathleen Allman’s suit seeks a judicial determination that neither De Bode nor Chen were validly appointed to their positions, that the contested compensation awards be declared void, and that damages be awarded for alleged breaches of fiduciary duty. The complaint frames these actions as an exploitation of the governance vacuum created by the founder’s unexpected death.

    Why This Matters

    The dispute at Ondo Finance highlights the acute governance risks facing young, founder-led crypto and tokenization firms where succession planning is often informal or nonexistent. Ondo, a significant player in the tokenized real-world asset (RWA) sector, manages substantial on-chain treasuries for DAOs and institutions. The legal battle introduces uncertainty over who controls the protocol’s strategic direction, treasury management, and tokenomics at a time when the RWA narrative is attracting significant institutional capital. The court’s eventual ruling on the validity of De Bode’s appointment and the disputed equity grants will set a precedent for how Delaware corporate law—under which many crypto entities are incorporated—treats rapid post-founder governance maneuvers and insider compensation in the digital asset space.

    Frequently Asked Questions

    Who currently controls Ondo Finance?

    As of the September 3 court order, De Bode remains the acting CEO and a member of the board. Kathleen Allman’s attempt to remove him and install herself as interim CEO has been temporarily stayed pending litigation.

    What is the total value of the compensation package Kathleen Allman is challenging?

    The complaint alleges an $11 million package consisting of a $900,000 annual salary and bonus, a $1 million signing bonus, 26 million restricted token units valued over $9 million, and equity awards covering 846,000 shares that would increase De Bode’s stake from 0.33% to roughly 8%.

    What legal claims does Kathleen Allman’s lawsuit assert?

    The suit seeks to invalidate De Bode’s and Chen’s board appointments, void the disputed compensation awards, and recover damages for alleged breaches of fiduciary duty, arguing the actions constitute a “brazen usurpation of corporate control” executed within days of the founder’s death.

  • AI Crypto Price Predictions: What Comparable Launches Reveal About Valuation

    AI Crypto Price Predictions: What Comparable Launches Reveal About Valuation

    Key Highlights

    • MemeToro ($MT) is in Stage 7 of its presale at $0.00430 on BNB Chain, having raised over $135,000, with a stated launch target of $0.05186 representing a 12.06x price gap.
    • The project differentiates itself by combining AI-generated memecoin proposals with deterministic on-chain validation that checks key conditions before execution, rejecting unsupported URLs, non-100% allocation totals, and insider allocations.
    • Critical infrastructure remains unfinished: the live executor, factory contracts, testnet deployment, and independent code review are all pending despite 1,373 lines of code across 17 files published for the fair-launch draft.

    AI Utility Versus Branding in the Current Token Landscape

    The intersection of artificial intelligence and early-stage token launches continues to draw speculative capital, yet the presence of an AI label does not inherently signal a functional product or sustainable token economy. MemeToro positions itself as an AI-led memecoin launch platform on BNB Chain, where the native $MT token is currently in Stage 7 priced at $0.00430 with more than $135,000 raised. The project’s future valuation hinges on whether its planned AI tooling and fair-launch architecture translate into genuine utility for users rather than remaining theoretical constructs.

    Deterministic Validation as a Guardrail Against AI Error

    MemeToro’s stated AI function involves scanning trends and evidence, preparing memecoin proposals, and publishing launch manifests before a token moves toward execution. Crucially, the agent is not designed to exercise unlimited control over on-chain rules. Instead, its outputs are intended to pass through deterministic validation—traditional code rather than the language model alone checks key conditions before a proposal can advance. This validation layer is designed to reject unsupported URLs, allocation totals that do not equal 100%, non-zero insider allocations, and funding terms that conflict with the published proposal. The fair-launch escrow draft is structured without an owner, admin role, or upgrade path, a design choice meant to limit the surface area for AI mistakes or manipulated inputs.

    Unfinished Infrastructure and the Gap Between Code and Claims

    For analysts attempting a crypto presale price prediction, MemeToro’s validation architecture provides a clearer factual basis than projects relying solely on chatbot mascots or vague automation claims. However, the agent-to-contract connection remains incomplete. The project has published 1,373 lines of code across 17 files for its first fair-launch draft, yet the live executor, factory contracts, testnet environment, and independent security review are all still pending. This gap between published drafts and deployable infrastructure is a material consideration for any valuation model. The planned $MT utility spans access rights, funding participation, staking, rewards, memecoin trading, and prediction-market functions—features that could support demand if delivered and adopted, but which remain prospective until the platform goes live.

    Historical Cycles Underscore Narrative Volatility

    Previous AI token cycles demonstrated how rapidly attention can accumulate around autonomous agents and viral online personas, with some tokens reaching significant valuations during peak interest while many others lost momentum once speculation cooled. The lesson is not that every AI token will replicate that pattern, but that narrative demand can shift quickly, particularly for assets with limited trading history. A rigorous presale price prediction should look beyond past headline valuations and ask whether the project has active, auditable code; clear token utility; a realistic launch roadmap; and a compelling reason for users to return after the initial trading period.

    Why This Matters

    The MemeToro case illustrates a broader tension in the AI-crypto crossover: projects that embed AI within a rigid, auditable rule set may offer more analyzable risk profiles than those using AI primarily as a marketing veneer. For market participants, the distinction affects due diligence priorities—shifting focus from promotional claims to verifiable code, validation logic, and deployment milestones. As regulatory scrutiny of token offerings intensifies, designs that minimize centralized control (such as ownerless escrows and non-upgradeable contracts) may also face different compliance trajectories. The pending testnet launch and independent review will serve as the next concrete proof points for whether MemeToro’s architectural choices survive contact with a live environment.

    Frequently Asked Questions

    Does an AI label make a token valuable?

    No. The project needs a clear AI function, working technology, demand, and sound token economics.

    What makes MemeToro different from an AI-branded token?

    MemeToro’s stated model combines AI proposals with published manifests, deterministic validation, and planned fair-launch contract rules.

    Are AI token price targets reliable?

    No. They are scenarios, not guarantees, and can change with market conditions and product delivery.