Category: Coins

Digital assets, cryptocurrencies, blockchain, and currency news.

  • Kalshi Seeks 24/7 Tesla and Nvidia Perpetual Futures as Wall Street Battles Over Regulation

    Kalshi Seeks 24/7 Tesla and Nvidia Perpetual Futures as Wall Street Battles Over Regulation

    Prediction marketplace Kalshi is preparing to introduce one of cryptocurrency’s most widely traded instruments to the U.S. equities market, with perpetual futures contracts tied to major companies including Tesla, Apple, and Nvidia that would operate around the clock.

    Regulatory Filing Planned for Dozens of Contracts

    The operator intends to seek regulatory approval for approximately 60 perpetual futures linked to individual stocks and exchange-traded funds, the Wall Street Journal reported late Thursday. If cleared, these would become the first regulated single-stock perpetual futures offered in the United States.

    How Perpetual Futures Work

    Perpetual futures, commonly known as perps, allow traders to speculate on whether an asset will rise or fall, frequently using leverage, without the contract ever reaching an expiration date. Instead of settling at maturity, traders exchange regular funding payments that keep the contract price anchored to the underlying asset’s spot price.

    From Crypto Innovation to Mainstream Markets

    Since the soon-to-be-defunct exchange BitMEX launched these products in 2016, perpetual futures have grown into one of the cryptocurrency sector’s largest business lines. Newer platforms such as Hyperliquid now enable traders to take leveraged positions on bitcoin and hundreds of tokens at any hour.

    Around-the-Clock Price Discovery

    A Tesla perpetual future could continue trading through nights and weekends while Tesla shares on the Nasdaq remain closed, providing a live view of what traders believe the company is worth hours—or even days—before the stock market itself reopens.

  • Zcash Price Prediction 2026: Can ZEC Reach $2,200 After 2,000% Rally as MemeToro Targets AI Crypto Growth?

    Zcash Price Prediction 2026: Can ZEC Reach $2,200 After 2,000% Rally as MemeToro Targets AI Crypto Growth?

    Zcash Surges 2,000% to Multi-Year High, Fueling 2026 Price Debate

    Zcash ($ZEC) has become a focal point for cryptocurrency traders after climbing thousands of percent over the past year to reach a multi-year high near $1,254. The rally has pushed the privacy-focused cryptocurrency’s market capitalization to approximately $20 billion and ignited intense debate around Zcash price predictions for 2026.

    Key Drivers Behind the $ZEC Rally

    The extraordinary performance stems from a convergence of institutional adoption and market mechanics:

    • Institutional ETF Access: The approval of the Grayscale Zcash Trust (ZCSH) on NYSE Arca created a regulated pathway for traditional investors to gain exposure to $ZEC.
    • Short-Squeeze Momentum: Forced covering of short positions amplified buying pressure as the price ascended rapidly.
    • Shift in Market Narrative: The conversation has moved from whether $ZEC could recover from a prolonged decline to whether it can sustain momentum after an explosive advance.

    Can $ZEC Reach $2,200 or Higher in 2026?

    Analysts are now modeling scenarios that see $ZEC targeting $2,200, with some discussing a potential $2,500 objective by year-end 2026. Achieving these levels would require:

    • Sustained institutional demand through the ZCSH vehicle
    • Supportive broader cryptocurrency market conditions
    • Continued risk appetite among digital asset investors

    A move from the current $1,254 area to $2,200 represents an additional 75% gain, while $2,500 would require roughly a 100% increase from recent highs. However, rapid rallies often trigger profit-taking, and sentiment shifts can precipitate sharp corrections. The 2026 outlook is best viewed through probability-based scenarios rather than fixed price targets.

    Institutional Demand as a Structural Catalyst

    The ZCSH ETF represents more than a short-term catalyst—it structurally broadens the investor base beyond crypto-native participants. This development arrived concurrently with short-seller distress, creating a feedback loop that propelled $ZEC above $1,200.

    Market observers emphasize that the Zcash price prediction for 2026 hinges on whether ETF-driven demand persists after initial excitement subsides. Liquidity conditions, macroeconomic sentiment, and sustained inflows will determine if the rally has staying power.

    MemeToro Pursues AI Crypto Infrastructure on BNB Chain

    While Zcash captures attention through price action, MemeToro is advancing a fundamentally different strategy: building open-source infrastructure for AI-driven memecoin launches on BNB Chain.

    Stage 7 Presale and Transparent Launch Mechanics

    The project has progressed to Stage 7 of its presale, reporting over $121,171 raised according to its latest update. A core technical component is the FairLaunchEscrow Solidity contract, which is open-source and designed with zero insider allocation to prevent hidden developer distributions and support transparent community token launches.

    AI Agent Scripts and Ecosystem Development

    MemeToro is also developing open-source AI agent scripts as part of its broader vision for AI-powered memecoin deployment. This positions the project at the intersection of two dominant crypto narratives: artificial intelligence and community-driven token launches.

    Two Distinct Market Narratives

    The contrast is clear: Zcash is riding a mature asset’s explosive re-rating driven by institutional access and short-covering dynamics, while MemeToro is attempting to establish foundational infrastructure for a nascent AI-crypto niche. Both reflect shifting capital flows and narrative evolution within digital asset markets.

    MemeToro ($MT) Presale Resources

  • Coinbase, Moov Bring Stablecoin Payments to 1,000+ Community Banks

    Coinbase, Moov Bring Stablecoin Payments to 1,000+ Community Banks

    Coinbase and payments platform Moov have formed a partnership designed to bring stablecoin payments and custody capabilities to the technology stacks used by more than 1,000 U.S. community banks and credit unions. Announced by Coinbase, the agreement will see Moov integrate Coinbase’s stablecoin infrastructure into its existing payments platform, giving financial institutions a turnkey way to offer stablecoin services without having to independently build wallets, blockchain connections, or other crypto infrastructure.

    The planned services span consumer payments, merchant acceptance, settlement, payouts, and real-time funding. Neither company disclosed a launch date or identified which banks and credit unions will be the first to roll out the services.

    How the Partnership Splits the Work

    Coinbase will supply the digital-asset infrastructure underpinning the collaboration. Moov intends to leverage Coinbase Developer Platform’s Custodial Wallet accounts to hold funds and its Payments API to coordinate stablecoin transfers, extending the always-on settlement advantage that is driving stablecoin rails to replace traditional wire transfers. Moov will connect these capabilities to the payment systems already used by its financial-institution customers. Its platform currently links more than 1,000 community banks and credit unions to services including card acquiring, card issuing, and real-time payment rails.

    The integration does not mean every institution connected to Moov will immediately offer stablecoin products. Each bank or credit union will still need to decide whether to participate and determine how the services fit within its compliance and risk-management requirements.

    Coinbase Announces the Partnership on X

    Banks benefit from crypto.We’re partnering with @Moov to provide small and community banks the infrastructure for stablecoins.That means acceptance, settlement, and real-time funding for more than 1000 of them, through the tech stacks they already use.This is what regulated… pic.twitter.com/sS8NNIVZBF
    — Coinbase 🛡️ (@coinbase) September 10, 2026

    Why Community Banks Are Exploring Stablecoins Now

    Stablecoins can move outside conventional banking hours, potentially allowing merchants to receive funds on weekends and holidays. They may also provide an additional settlement option for businesses already receiving payment requests in digital dollars. Wade Arnold, Moov’s co-founder and CEO, noted that business customers are increasingly being asked to accept stablecoins but often must leave their primary financial institution to do so. The partnership is designed to let community institutions provide that connection themselves. Jill Castilla, CEO of Citizens Bank of Edmond, linked the technology to demand from small businesses seeking faster payments and lower interchange costs.

    However, stablecoin transfers still create custody, compliance, fraud, liquidity, and operational risks. Faster blockchain settlement does not guarantee that customers will receive immediate access to bank deposits, since conversion and compliance reviews may add separate processing steps.

    A Partnership Arriving Amid an Active Policy Debate

    The announcement arrives as banks and crypto companies continue to debate the treatment of stablecoins under U.S. legislation. Lawmakers are considering the Clarity Act and rules affecting stablecoin rewards, payment activity, and the division of oversight between financial regulators—a dynamic explored in recent comparisons of the Clarity Act versus the GENIUS Act. Community-banking groups have warned that stablecoins offering yield-like incentives could draw deposits away from smaller institutions. Coinbase and Moov are taking a different approach by positioning community banks as distribution partners for stablecoin services rather than competitors to them.

    The Details That Will Determine How This Rolls Out

    The first participating institutions, supported stablecoins, blockchain networks, pricing, and rollout schedule have not been disclosed. More information will also be needed on how customer funds will be held, converted, reported, and protected within each institution’s service.

    What This Means for You

    The partnership could let customers and businesses access stablecoin payments through familiar local institutions instead of relying entirely on standalone crypto platforms. Its practical impact will depend on how many Moov-connected banks adopt the services and what custody, conversion, and withdrawal terms they offer.

    This is not financial advice. Stablecoins and digital-asset custody involve regulatory, operational, counterparty, liquidity, and technology risks. Availability will depend on participating institutions and applicable requirements.

  • Bitwise Closes Dogecoin ETF, Signaling ETF Access Doesn’t Guarantee Demand

    Bitwise Closes Dogecoin ETF, Signaling ETF Access Doesn’t Guarantee Demand

    Bitwise Shuts Down Dogecoin ETF BWOW After Less Than a Year

    Bitwise Asset Management will close its Dogecoin exchange-traded fund (ETF) in October, marking a swift exit for a product that launched in late November 2025. The decision underscores a growing divide in the crypto ETF market: regulatory approval and brokerage access no longer guarantee sustainable investor demand for single-token funds.

    Late-October Wind-Down for BWOW

    According to a Form 8-K filed with the SEC, Bitwise Investment Advisers notified NYSE Arca of its decision to voluntarily close, delist, and liquidate the Bitwise Dogecoin ETF (NYSE: BWOW). Trading is expected to cease on October 14.

    Investors holding BWOW shares after liquidation need take no further action. Remaining shares will be redeemed for cash based on the fund’s net asset value (NAV) as of October 21, with distributions expected around October 22. The SEC filing notes these distributions will constitute taxable events.

    Bitwise offered only a brief explanation in its liquidation notice:

    “Bitwise has determined to liquidate the Fund as it continues to optimize its product range to meet evolving investor needs.”

    The firm did not cite a specific asset level, trading volume, or cash-flow threshold that triggered the closure, framing it instead as part of ongoing portfolio optimization amid shifting investor preferences.

    Fund Data Reveals Persistent Weakness

    The fund’s own metrics, however, point to chronically low demand. Bitwise announced BWOW on November 25, 2025, with trading beginning the following day. By September 8, 2026, the fund held just $721,815 in assets and approximately 8.2 million DOGE. Its August month-end data showed a cumulative NAV return of -45.37% since inception.

    The decline began early. BWOW’s second-quarter filing showed net assets falling from $1.15 million at the end of 2025 to $473,547 on June 30, 2026. There were zero share creations in the first half of 2026, while 20,000 shares were redeemed. The fund never achieved meaningful scale.

    Trading activity tells the same story. BWOW recorded roughly $3 million in daily volume during its launch week but never approached that level again. By September 10, U.S. Dogecoin ETFs had generated about $300 million in cumulative trading volume, according to The Block. That figure trailed Hyperliquid ETFs at $2.1 billion, Zcash products at $1.5 billion, and Chainlink funds at $680 million—highlighting how little secondary-market interest Dogecoin ETFs have attracted relative to newer altcoin products.

    Contrast with Bitwise’s Hyperliquid ETF

    The disparity is stark when compared with Bitwise’s own Hyperliquid ETF (BHYP). Cryptopolitan reported in August that Bitwise-linked ETF wallets purchased more than $5 million of HYPE in a single week and had not sold since July, citing on-chain data from Arkham. While that estimate is not an official Bitwise flow report, it aligns with broader evidence of stronger HYPE ETF activity.

    Dogecoin ETFs have moved in the opposite direction. The three U.S. DOGE funds posted approximately $670,530 in net outflows over the latest 30-day period, leaving cumulative net inflows at just $11.77 million, according to SoSoValue.

    Listing Access Does Not Equal Sustained Demand

    The takeaway is not that memecoins cannot function in ETF wrappers. Rather, a large community does not automatically translate into sustained brokerage demand.

    Spot crypto products became easier to launch after the SEC approved generic listing standards for commodity-based trust shares on September 17, 2025. Qualifying products can now list without a separate proposed rule change for each fund. That regulatory shift widened the field without equalizing investor appetite.

    ETF.com estimates spot Solana products have attracted nearly $880 million in cumulative inflows, while spot XRP products have drawn about $1 billion. For the global crypto market, BWOW’s closure demonstrates that easier listing accelerates launches without guaranteeing survival. Issuers are likely to concentrate on tokens that sustain assets, liquidity, and repeat inflows—focusing regulated-market liquidity around fewer altcoins.

    ETF access is getting easier. Sustained demand still has to be earned.

  • MoneyGram Launches Visa Stablecoin Card in Colombia

    MoneyGram Launches Visa Stablecoin Card in Colombia

    MoneyGram has launched a Visa stablecoin card in Colombia, giving eligible customers access to dollar-linked balances, card payments and local cash collection. The virtual MoneyGram Card became available through the company’s mobile application on September 10, with support for Apple Wallet and Google Wallet for online and contactless payments wherever Visa is accepted.

    Product architecture and partners

    The Dallas-based payments company developed the product with stablecoin infrastructure provider Rain. Crossmint supplies the wallet technology embedded in the MoneyGram app, while the Stellar network handles the blockchain transactions that power the service. Colombia is the first market for the card; MoneyGram plans to expand to additional countries in the coming months and introduce a physical version before the end of 2026. The company has not disclosed the next target markets, pricing structure or an exact release date for the physical card.

    Spending and cash access in one app

    Within the MoneyGram app, eligible customers can apply for the virtual card and manage their balance and transactions. The card lets users hold a stable-dollar balance and spend it through Visa’s merchant network without leaving the MoneyGram application. Cardholders who need physical currency can send money to themselves and collect local cash from a participating MoneyGram location. The initial virtual product does not provide direct ATM withdrawals, according to the release. MoneyGram expects the planned physical card to add ATM access and purchases at locations where digital wallets are unavailable.

    “We’re giving customers more freedom and control to manage their money, all in one place,” Chairman and CEO Anthony Soohoo said. He described the product as combining “a stable-dollar balance, everyday spending and cash access” inside MoneyGram’s existing service.

    Stablecoin backing and regulatory context

    The company did not identify which stablecoin backs customer balances, explain its reserve arrangement or publish redemption terms in the announcement. Its description of a “stablecoin-backed card” confirms that blockchain-based dollar value funds the product, but it does not say whether customers directly hold tokens or a platform balance representing them. MoneyGram has presented the card as a product for eligible users worldwide, though availability will depend on each launch market, local regulations and the company’s rollout schedule.

    Under the U.S. GENIUS Act, payment stablecoins must meet rules covering permitted issuers, reserve assets, redemption and monthly disclosures once the applicable provisions take effect. Crypto.news has detailed how U.S. stablecoin issuers face reserve and licensing requirements, although MoneyGram’s release does not identify MGUSD as the asset backing its Colombian card. The company has not said whether future versions will support multiple stablecoins or blockchain networks.

    Partner roles and MoneyGram’s scale

    Rain supplies the card infrastructure connecting stablecoin balances with the Visa payment network. The New York-based company provides card and wallet technology for businesses offering stablecoin-funded payments. Crossmint handles the wallet component used inside MoneyGram’s application. Stellar provides the public blockchain on which the product’s underlying digital transactions operate, according to MoneyGram.

    MoneyGram retains the customer-facing relationship through its app and cash network. The company reports more than 60 million active customers, operations across over 200 countries and territories, and nearly 500,000 retail locations. All three figures come from MoneyGram and were not independently audited in the card announcement.

    Colombian market and competitive landscape

    The Colombian debut places the card in a market where financial companies are testing blockchain-based settlement and foreign-exchange systems. In related coverage, crypto.news reported that two Colombian financial institutions joined a 24/7 settlement network, including state-owned Banco Agrario.

    Rain worked with Western Union on a separate Visa stablecoin card announced in August. Western Union’s Stablecard lets eligible recipients hold dollar-backed stablecoins and spend through Visa, giving both major remittance providers card products built with the same infrastructure company.

    MoneyGram’s stablecoin strategy evolution

    MoneyGram introduced MGUSD on Stellar in June 2026 for treasury management, settlement and foreign-exchange activity. The company said at the time that the dollar-linked token would initially become available in the U.S., followed by other markets. Its stablecoin strategy later extended to MoneyGram Ramps, an application programming interface linking digital wallets with its physical cash network. An August integration brought the service to Solana, letting supported wallet users deposit or withdraw value through participating locations.

    The card gives customers a spending function on top of MoneyGram’s digital balance and cash services. People can retain dollar-linked value, pay merchants through Visa or collect local currency through the company’s retail network.

    Remittance cost benchmarks

    The World Bank’s September 2025 remittance-pricing report found that the global average cost of sending $200 was 6.36% during the third quarter of 2025. Digital remittances averaged 4.59%, compared with 7.30% for nondigital services. Debit cards carried the lowest average cost among the payout methods measured. Disbursing a remittance through a debit card cost 3.61% across the 48 services in that category. Mobile wallets averaged 3.18% in the World Bank’s separate prospective-services index, where debit-card data were unavailable.

    For funding a transfer, credit and debit cards became the cheapest measured instrument at 4.39%. Cash-funded transfers averaged 7.01%, while bank-account funding cost 8.69%. The World Bank dataset covered 48 sending countries, 105 receiving countries and 367 corridors. MoneyGram and Western Union appeared in the International Money Transfer Operator Index because their services covered 90% and 95% of the tracked corridors, respectively.

    MoneyGram has not published the fees, foreign-exchange spread or card-transaction charges applying to its Colombian product. The planned physical card is scheduled for late 2026, when MoneyGram expects to introduce ATM withdrawals and in-person payments beyond locations supporting digital wallets.

  • Coinbase Targets 1,000 Banks With Moov Stablecoin Deal

    Coinbase Targets 1,000 Banks With Moov Stablecoin Deal

    Coinbase and Moov Partner to Bring Stablecoin Payments to Over 1,000 U.S. Community Banks

    Coinbase has announced a strategic partnership with payments infrastructure provider Moov to connect more than 1,000 U.S. community banks and credit unions with stablecoin payments, custody, merchant settlement, and real-time funding capabilities. The announcement, made on September 10, 2026, positions the collaboration as a way for smaller financial institutions to offer digital asset services without building their own blockchain systems.

    Shared Infrastructure Model for Community Institutions

    Moov, which provides card acquiring, card issuing, and real-time payment connections to institutional customers, will integrate Coinbase’s stablecoin infrastructure into the payment systems already offered to its financial institution clients. The companies did not disclose a commercial launch date or identify the first participating banks.

    Under the arrangement, Coinbase will supply digital asset custody and payment tools, while Moov will connect those capabilities with the systems used by its community bank and credit union customers. Moov plans to use Coinbase Developer Platform Custodial Wallet accounts to hold funds, and Coinbase’s Payments API will coordinate stablecoin transfers. This design allows Moov to embed blockchain functions inside its existing payment product.

    The companies identified consumer payments, merchant acceptance, merchant settlement, and payouts as initial applications. Business and merchant transactions will use Coinbase custodial accounts with disclosed ownership, according to the release.

    Executive Perspectives on the Partnership

    Coinbase highlighted the partnership in a social media post:

    Banks benefit from crypto.We’re partnering with @Moov to provide small and community banks the infrastructure for stablecoins.That means acceptance, settlement, and real-time funding for more than 1000 of them, through the tech stacks they already use.This is what regulated… pic.twitter.com/sS8NNIVZBF

    Ryan VanGrack, Coinbase vice chair and head of corporate affairs, stated that community financial institutions have watched customers use digital assets for years. Through Moov, Coinbase plans to place its infrastructure “right into their existing systems,” he said.

    Moov CEO Wade Arnold noted that business customers already receive requests to accept stablecoins and often leave their primary financial institution to obtain the service. He described acceptance and disbursement as the immediate products, with continuous funding presented as a possible later use.

    Banks Retain Customer Relationships and Control

    Moov will serve as the connection between Coinbase and participating institutions. Banks and credit unions can continue managing their customer accounts and local relationships while using third-party infrastructure for blockchain custody and payments. The partnership does not turn participating banks into stablecoin issuers.

    Coinbase described the arrangement as a way for institutions to offer payment and custody services, with no announcement made about a community bank creating its own dollar-backed token. Citizens Bank of Edmond Chairman and CEO Jill Castilla was quoted in the announcement noting that small businesses are seeking lower interchange costs and faster access to payments, though Coinbase and Moov did not confirm that the Oklahoma bank will become an initial customer.

    Regulatory Context and Compliance Considerations

    Under the Federal Reserve’s definition, its community bank program covers domestic state member banks, bank holding companies, and savings and loan holding companies with less than $10 billion in total assets. Other agencies supervise community institutions operating under different charters. Federal Reserve examinations usually take place every 12 months, with some eligible banks examined every 18 months depending on size, condition, and other factors.

    Coinbase and Moov did not describe how participating institutions will divide compliance duties involving customer identification, transaction monitoring, sanctions screening, or suspicious-activity reporting. Each bank will remain subject to its applicable federal and state obligations.

    Stablecoin Details and Operational Parameters Remain Undisclosed

    Neither company named the stablecoins or blockchain networks that the integration will support. Coinbase’s developer platform offers access to USDC and custom stablecoin products, but the announcement did not confirm which assets Moov’s customers will receive.

    Details covering transaction fees, conversion charges, redemption, insurance treatment, and user eligibility remain undisclosed. The partners did not say whether financial institutions would hold stablecoins directly or provide customers with balances backed by assets held in Coinbase custody. The announcement refers to “fully disclosed custodial accounts” for business and merchant payments without publishing the account terms.

    Diverging Models in Bank Stablecoin Adoption

    Large banks are pursuing stablecoin projects through structures that differ from Coinbase and Moov’s service-provider model. U.S. Bank disclosed a live cross-border test on September 9 involving USBDC, its proprietary dollar-backed token. As previously reported, U.S. Bank transferred USBDC between North American and European entities on the Stellar public blockchain, testing minting, redemption, freezing, and clawback functions while maintaining links with the bank’s finance, risk, and compliance systems.

    U.S. Bank did not make USBDC available to customers or external institutions. The bank released a Stellar issuer address but withheld the payment amount, transaction hash, reserve structure, and public rollout timetable.

    Coinbase and Moov are proposing shared infrastructure that can serve many institutions, centering on payment acceptance and custody through Coinbase instead of asking every participating bank to create a separate token and issuance platform. Banking technology providers are forming other institutional networks around tokenized deposits and digital assets. In related coverage, Cosmos formed a 17-member banking infrastructure network with participants including BitGo, Galaxy, and OpenZeppelin.

    The Coinbase partnership does not state whether Moov’s banks will work with tokenized deposits, which represent bank liabilities on blockchain infrastructure. Its announced scope covers stablecoins, custodial accounts, and payment movement.

    Federal Stablecoin Framework Sets Participation Requirements

    The GENIUS Act created a federal framework for payment stablecoins in July 2025. The law restricts issuance to permitted entities and requires one-to-one backing with qualifying liquid assets. Bank subsidiaries may issue payment stablecoins under the supervision of their federal banking regulator. State-qualified issuers can operate through certified state regimes, while nonbank firms may seek federal approval from the Office of the Comptroller of the Currency.

    Payment service providers remain subject to anti-money-laundering and sanctions requirements regardless of whether they issue tokens. Stablecoins are not automatically covered by federal deposit insurance, even when their reserves include deposits held at an insured bank.

    For the Coinbase-Moov arrangement, the applicable responsibilities will depend on the asset used, the custody structure, and the services offered by each institution. The companies have not published contracts explaining how losses, frozen transactions, redemption requests, or operational failures would be handled. Coinbase describes its digital asset infrastructure as regulated, but the announcement does not name the Coinbase legal entity that will hold each category of customer or merchant funds.

    No Public Rollout Date or Pilot Participants Announced

    Implementation will require Moov to integrate Coinbase’s wallet and payment interfaces before individual banks can offer the services. Each participating institution may need internal approval, compliance testing, and vendor-risk reviews based on its regulator and operating model.

    No bank has announced a customer launch through the partnership. Coinbase and Moov have not disclosed pilot participants, supported payment corridors, minimum transaction amounts, or settlement currencies. Future functions described by the companies remain plans. Coinbase said acceptance, settlement, and real-time funding are starting areas, while later work could connect digital assets with other products offered by community institutions.

    Moov said continuous funding could let institutions move value during weekends and holidays. The company has not released performance results showing settlement times, transaction capacity, or costs for the planned service. Coinbase and Moov have not provided a deadline for completing the technical integration or opening stablecoin services to the first community bank customers.
  • Bitcoin Below $77,000, Zcash Leads Losses as Traders Bet on Fed Rate Hike

    Bitcoin Below $77,000, Zcash Leads Losses as Traders Bet on Fed Rate Hike

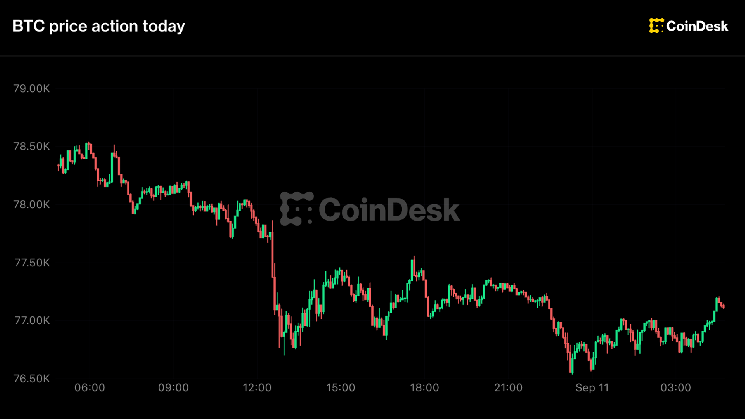
    Bitcoin hovered near a critical technical threshold Thursday as risk assets sold off broadly on surging oil prices, rising Treasury yields, and mounting expectations for another Federal Reserve interest-rate hike.

    Key Support Level in Focus

    Bitget analyst Lewis Huang marked the line before the print, saying “$76,270 is an important technical support level.” Bitcoin is now less than $800 above it.

    Energy Shock Ripples Through Markets

    Brent crude ripped above $107 a barrel, up more than 6%, with West Texas Intermediate near $102. The energy shock feeds directly into the inflation data the Fed is watching. The 10-year Treasury yield pushed toward 5% and the two-year above 4.5%.

    Gold slipped toward $4,330, the dollar index firmed near 99, and the S&P 500 closed lower at about 7,594, a fourth straight decline. Asian equity futures followed, with Japan down nearly 2%, Korea more than 3% and Hong Kong close to 1%.

    Higher Real Yields Pressure Crypto

    Higher real yields drain crypto through two channels at once. They make government debt competitive with an asset that pays nothing, and they raise the cost of carrying leverage.

    U.S. spot bitcoin ETFs are already showing it, with $120 million of outflows on Wednesday, more than double Tuesday’s, while ether, $XRP and solana funds all took in money the same day.

    CPI Data and Fed Expectations

    August CPI lands at 8:30 a.m. ET, with headline inflation expected at 3.4% year over year and core at 2.4%. Interest rate futures put the odds of a hike at the Sept. 15-16 meeting near 70%, up from roughly a coin flip two weeks ago.

  • XRP Faces Key Test as Historical Pattern Points to Possible Pullback

    XRP Faces Key Test as Historical Pattern Points to Possible Pullback

    XRP Weekly Super Trend Flips Bullish, But Analyst Warns of Historical Pattern

    XRP’s weekly Super Trend indicator turned bullish on August 17 after the token rallied roughly 70% from $0.98 to $1.70. However, analyst ChartNerd cautions that this exact signal has marked local tops before deep pullbacks in every previous cycle dating back to 2019, and XRP is currently stalling at the resistance level that decided those earlier setups.

    Bullish Signal Meets Key Resistance Zone

    ChartNerd’s analysis focuses on the price action following XRP’s recovery from the $0.98 area. The token advanced about 70% toward $1.70, where it encountered the 50-week exponential moving average (EMA), currently near $1.52. Simultaneously, XRP has been trading between that resistance and the 20-week EMA around $1.29 to $1.30.

    “Whilst beneath the 50 and above the 20, we’re simply compressing,”

    ChartNerd said, describing the recent price action as a period of chop while traders wait for a clearer direction.

    That caution stems from XRP’s earlier cycle history. In 2022, the token rallied about 90% from its cycle low before a bullish Super Trend flip appeared around the 50-week EMA, a move followed by a 45% correction. In 2019, another bullish flip during the bear market preceded a 56% correction, and after the 2020 cycle low, XRP also printed a bullish flip before falling 32%.

    ChartNerd argues this pattern has appeared often enough to warrant caution.

    “Bullish super trends usually mark local tops,”

    the analyst said, while stressing that historical behavior does not guarantee the same outcome this time.

    He also placed a greater structural change around $1.90, noting that XRP would need to clear the $1.50 to $1.90 zone before the move toward its previous high looks more convincing. A short-term push above $1.52 is still possible, the analyst said, but even a close above the 50-week EMA would not automatically remove the historical warning.

    Price Action Remains Choppy This Week

    As CryptoPotato reported earlier, XRP dipped toward $1.39 during one leg of Bitcoin’s recent slide before buyers stepped back in to push it to $1.44. At the time of writing, the token had fallen close to 4% in the last 24 hours and was again trading near $1.38, according to CoinGecko data. It is up 1.5% over the past week but down more than 53% from a year ago, and remains about 62% below its all-time high of $3.65 from July 2025.

    Bitcoin has been chopping between $77,600 and $80,000 over the past few days, and XRP’s swings have largely tracked that back-and-forth rather than moving on independent catalysts.

    Futures Volume Surges, ETF Inflows Slow

    The Ripple token’s futures volume picked up in August, with trading across the three biggest exchanges topping $64 billion, the busiest month in half a year. Spot XRP ETFs continued adding money, although the pace slowed significantly, with weekly inflows dropping to just under $19 million last week after bringing in more than $110 million the week before. So far this week, SoSoValue data shows net inflows have hit about $13.83 million.

  • Ethereum Liquidity Surges: Can ETH Steal Bitcoin’s Spotlight in Q4?

    Ethereum Liquidity Surges: Can ETH Steal Bitcoin’s Spotlight in Q4?

    Bitcoin’s August Surge Masks Weak Spot Demand and Liquidity Concerns

    Bitcoin closed August over 25% higher compared to the previous month, recording its best monthly performance since November 2024. However, the stablecoin market cap only managed to grow by 0.5% and failed to hold above $310 billion, which suggests that the inflow of liquidity is happening at a slow pace.

    On-Chain Metrics Reveal Lack of Spot Buying Pressure

    The same pattern is evident on the on-chain level. As the chart below shows, Bitcoin rose by around 45% from its recent low, but there is a lack of spot demand, as evidenced by the 90-day CVD being neutral. Liquidity across exchanges is also weak, as seen in Binance’s stablecoin reserves, which dropped nearly $7 billion from their cycle peak above $50 billion.

    Source: CryptoQuant

    Technical Bullishness Contrasts with Speculative Positioning Risks

    So, while Bitcoin’s technical structure has turned bullish, liquidity and spot demand remain muted. At the same time, rising Open Interest suggests growing speculative positioning, which makes $BTC vulnerable to a long squeeze if $80k resolves as the ceiling, especially with the FOMC meeting approaching.

    Ethereum’s Liquidity Divergence Signals Potential Shift from Bitcoin

    However, the bigger signal may be the growing liquidity divergence between Bitcoin and Ethereum. If capital continues to rotate towards $ETH and away from $BTC, this could set up the conditions for altcoins to outperform Bitcoin in the coming Q4, particularly as macro volatility drives risk appetite shifts. If this trend holds, it could provide the first confirmation that Bitcoin’s [$BTC] current rally is a bull trap.

    Ethereum Derives Liquidity from Both Speculation and On-Chain Utility

    Unlike Bitcoin, Ethereum is capable of deriving liquidity from both speculative demand and on-chain utility. The promise of Ethereum as a platform for stablecoins, tokenized assets, and DeFi creates additional demand for the asset.

    For instance, the total stablecoin supply in the Euro minted on the Ethereum blockchain increased by 347.3% over the past three years to reach $848.1 million. Ethereum hosts 69.4% of the total, surpassing all other blockchains combined by more than double. Similarly, stablecoins on the Robinhood Chain exceeded the $1 billion mark, illustrating the strong demand for on-chain liquidity.

    Record ETH Staking Underscores Capital Commitment to Ethereum

    In addition, as depicted in the chart below, staking $ETH is yet another example of increased demand for Ethereum. According to the chart, the amount of $ETH staked saw yet another ATH. Specifically, 42.95 million $ETH or $105.96 billion were deposited across all validators, representing 35.21% of $ETH’s supply.

    Source: ValidatorQueue

    Capital Flows Into Ethereum Ecosystem Drive ETH/BTC Ratio Higher

    Taken together, improving stablecoin liquidity and record $ETH staking suggest that capital is flowing into the Ethereum ecosystem. Not only are traders fueling demand, but holders are also locking up significant amounts on-chain and committing them to the network.

    This helps explain why the $ETH/$BTC ratio keeps trending higher. While Bitcoin is seeing rising bull trap fears and weak spot buy, Ethereum has seen increased liquidity and capital inflows. If the divergence persists, then $ETH/$BTC ratio could very well have the momentum to break above 0.031.

    Altcoin Outperformance Potential in Q4 Hinges on Sustained Liquidity Rotation

    More importantly, a sustained rotation of liquidity into Ethereum [$ETH] can spill over into the broader altcoin market. And if Bitcoin continues to lose liquidity share to $ETH, it could be a major catalyst for altcoins to outperform $BTC in the fourth quarter.

    Final Summary

    • Ethereum is seeing more liquidity, with stablecoin growth and record $ETH staking showing stronger demand.
    • If this trend continues, $ETH could keep gaining on $BTC and help drive an altcoin rally in Q4.
  • Bitcoin Mining Generates 90% of HIVE’s $1 Million Daily Revenue Amid Ongoing AI Expansion

    Bitcoin Mining Generates 90% of HIVE’s $1 Million Daily Revenue Amid Ongoing AI Expansion

    HIVE Digital Technologies Reports $1 Million Daily Revenue Average, Driven by Bitcoin Mining

    HIVE Digital Technologies disclosed that its combined Bitcoin mining and GPU cloud operations generated more than $1 million in average daily revenue from August 21 through September 10, offering a concrete measure of how the company’s artificial intelligence pivot is contributing to current results.

    GPU Cloud Contributes Roughly 10% of Daily Revenue

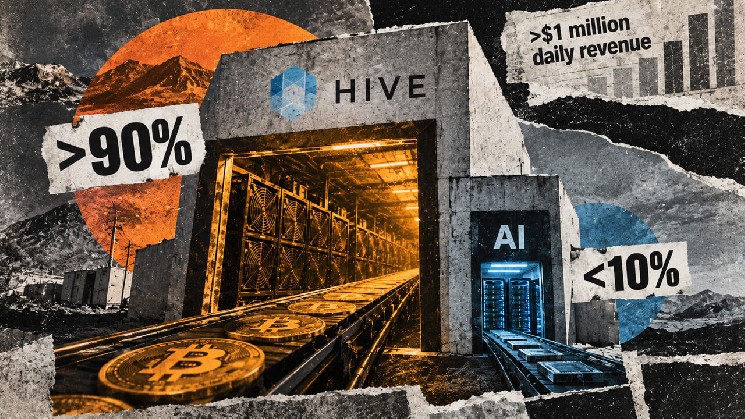
    According to the company’s September 10 update, the GPU cloud segment produced approximately $100,000 per day during the period. That figure represents an operating revenue stream from AI infrastructure, though it accounted for less than roughly 10% of the reported total. Bitcoin mining supplied more than nine-tenths of the daily average.

    An accompanying infographic illustrated the split, showing HIVE averaging over $1 million in daily revenue with approximately 90% derived from Bitcoin mining and 10% from GPU cloud services.

    Mining Output Tied to Network Conditions

    HIVE reported mining an average of about 12 Bitcoin per day during the window, equal to roughly 2% of global network production. The company emphasized that the revenue figures are preliminary, unaudited management estimates, and tied the results to prevailing Bitcoin prices, network difficulty, and operating conditions. The dollar value of mining output can change with Bitcoin’s price and network economics.

    While GPU cloud gives HIVE an operating foothold in AI infrastructure, Bitcoin mining remained the financial engine during the period.

    $600 Million Contract Pipeline Not Yet Recognized Revenue

    HIVE said it had closed more than $600 million in GPU-cloud total contract value year to date, combining signed customer agreements and letters of intent. The company warned that total contract value is not recognized revenue and does not guarantee future revenue.

    That distinction follows August reports of a $350 million AI cloud agreement and the financing and execution demands of a related $185 million GPU buildout. The new disclosure shows the AI business generating revenue, but the much larger commercial pipeline still depends on delivery over time.

    Wind-Down of Legacy Facilities Underway

    HIVE said those operations contributed less than 5% of the company’s global daily revenue in August and that it intends to wind down mining at the facilities. The company is evaluating whether to repurpose the sites for high-performance computing, the data-intensive infrastructure used for services such as AI. It has not said the conversion is complete, and its release cautioned that the wind-down and repurposing may not proceed as planned.

    Two-Speed Transition Continues

    For now, the operating numbers show a two-speed transition. AI cloud has become a revenue-producing business, while Bitcoin mining remains the financial engine carrying the shift. The next test is whether HIVE can turn more of its signed agreements and letters of intent, along with its existing infrastructure, into recognized GPU-cloud revenue without losing the mining cash flow that supports the transition.