Category: Coins

Digital assets, cryptocurrencies, blockchain, and currency news.

  • U.S. Regulator Warns of Cheating Risks in ‘Mention Markets’ on Prediction Platforms

    U.S. Regulator Warns of Cheating Risks in ‘Mention Markets’ on Prediction Platforms

    Key Highlights

    • The CFTC issued a staff advisory warning that “mention markets” — betting on what a specific individual might say or do — are “presumptively readily susceptible to manipulation.”
    • The regulator distinguishes these markets from standard event contracts because outcomes depend on “the discrete conduct of a named person” rather than independently generated, externally verifiable events.
    • Prediction platform operators including Kalshi and Polymarket are reminded they may only list derivative contracts that are not readily susceptible to manipulation.

    CFTC Targets ‘Mention Markets’ in New Supervisory Advisory

    The Commodity Futures Trading Commission has drawn a sharp regulatory line around a growing category of prediction-market contracts, issuing a staff advisory on Tuesday that labels wagers on an individual’s future statements or actions as “presumptively readily susceptible to manipulation.” The guidance, released by the agency’s Division of Market Oversight, signals a potential narrowing of the event-contract universe that can clear the CFTC’s supervisory hurdles, directly affecting operators such as Kalshi and Polymarket.

    How ‘Mention Markets’ Differ From Standard Event Contracts

    Unlike traditional event contracts that settle on “independently generated, externally verifiable outcomes that are outside the control of any single person,” the CFTC staff advisory explains that mention markets pivot on “the discrete conduct of a named person, and that conduct may be neither independently generated nor externally verifiable.” Because the outcome hinges on one person’s behavior — or the actions of those in their orbit — the agency warns that the individual or people around them could shift the result based on their own knowledge of the betting activity.

    Regulatory Reminder: Only Non-Manipulable Contracts Permitted

    The advisory serves as a formal reminder to prediction-platform operators that they are “only allowed to trade derivative contracts that are not readily susceptible to manipulation.” By classifying mention markets as presumptively problematic, the CFTC is effectively placing the burden on exchanges to demonstrate why any contract tied to a specific person’s conduct should be permitted, or to delist such markets altogether. The move underscores the agency’s focus on market integrity as prediction platforms expand their offerings beyond traditional economic and political indicators.

    Why This Matters

    The CFTC’s advisory arrives as prediction markets gain mainstream traction and attract significant volume during major news cycles. By targeting contracts tied to individual conduct, the regulator is addressing a structural vulnerability: markets where a single actor — or their associates — can influence the outcome create clear incentives for insider trading and market manipulation. For platforms like Kalshi and Polymarket, the guidance implies a compliance review of existing “mention market” listings and stricter vetting for future contracts. The decision also sets a precedent for how U.S. regulators may treat novel event-contract categories as the sector evolves, balancing innovation with the statutory mandate to prevent manipulation and protect market participants.

    Frequently Asked Questions

    What are “mention markets” according to the CFTC?
    Mention markets are wagers on what a specific, named individual might say or do — for example, whether a public figure will utter a certain phrase or take a particular action. The CFTC considers these distinct from standard event contracts because the outcome depends on the discrete conduct of one person.
    Why does the CFTC consider mention markets prone to manipulation?
    The advisory states that because the outcome pivots on “the discrete conduct of a named person,” that person or people around them could influence the result based on their own knowledge of the betting, making the market “presumptively readily susceptible to manipulation.”
    What must prediction platforms like Kalshi and Polymarket do in response?
    Operators are reminded they may only list derivative contracts that are not readily susceptible to manipulation. They will likely need to review existing mention-market contracts for compliance and apply stricter criteria before launching similar markets in the future.
  • CFTC Scrutinizes Kalshi After $5 Billion in Near-Identical Ether Perpetual Trades, WSJ Reports

    CFTC Scrutinizes Kalshi After $5 Billion in Near-Identical Ether Perpetual Trades, WSJ Reports

    Key Highlights

    • The Commodity Futures Trading Commission is reviewing unusual trading patterns on Kalshi involving nearly one million ether perpetual futures trades clustered around $5,500, representing over $5 billion in volume.
    • Kalshi denies wash trading allegations, attributing the pattern to market makers maintaining fixed resting orders and hundreds of distinct traders participating in the transactions.
    • Jump Trading and Wintermute were identified among firms involved in the rapid transactions, with Jump stating it trades for profit and uses self-match prevention tools.

    CFTC Scrutinizes Concentrated Trading Activity on Kalshi Ether Perpetuals

    The Commodity Futures Trading Commission is examining unusual trading activity on the Kalshi exchange after an analysis by The Wall Street Journal revealed nearly one million ether perpetual futures trades executed in almost identical amounts. According to the Journal’s review of public data, more than one-third of trades in the market during recent weeks clustered around the $5,500 price level, accounting for over $5 billion in ether perpetual volume over the past month. The regulatory review comes at a pivotal moment for Kalshi, which launched its crypto perpetual futures business in May and has since sought approval to offer similar contracts tied to individual U.S. stocks.

    Allegations of Wash Trading Prompt Regulatory Review

    The trading pattern has prompted allegations of wash trading—a practice involving trades lacking genuine economic purpose that can create a misleading impression of market activity. The CFTC is reviewing the activity before determining whether to open an enforcement investigation, according to a person familiar with the matter cited by the Journal. The agency said it could not comment on whether an investigation is underway. Kalshi has categorically denied the allegations, stating that hundreds of distinct traders participated in the transactions and arguing that the repeated trade sizes resulted from market makers maintaining fixed resting orders that were repeatedly hit by faster traders.

    Kalshi Defends Market Structure and Liquidity Programs

    In its defense, Kalshi emphasized that self-trading is mechanically blocked on its platform and that coordinated wash trading is both prohibited and actively monitored. The company said its liquidity programs compensate market makers for maintaining orders at specific sizes and spreads rather than rewarding trading volume. A temporary program also refunds trading fees for qualifying self-clearing members but does not allow traders to receive more in rebates than they paid in fees. According to the Journal, Jump Trading and Wintermute were among the firms involved in the rapid transactions. Jump said it trades for profit, uses self-match prevention tools, and does not coordinate its activity with other traders.

    Why This Matters

    The CFTC’s scrutiny of Kalshi highlights the growing regulatory focus on crypto derivatives markets as they expand beyond traditional cryptocurrency exchanges into regulated venues. Kalshi, designated as a contract market by the CFTC, operates under a different regulatory framework than many offshore crypto platforms, making this review particularly significant for the evolution of U.S.-regulated crypto derivatives. The outcome could set precedents for how market-making activities, liquidity incentives, and high-frequency trading patterns are policed in crypto perpetual futures markets. As Kalshi seeks to expand into single-stock perpetual futures, the resolution of this review will likely influence the pace and conditions of that regulatory approval process.

    Frequently Asked Questions

    What triggered the CFTC’s review of Kalshi trading activity?

    The Wall Street Journal’s analysis of public data revealed nearly one million ether perpetual futures trades clustered around $5,500 in almost identical amounts, representing over $5 billion in volume over the past month. This concentration—accounting for more than one-third of recent market trades—prompted the CFTC to review the activity for potential wash trading.

    How has Kalshi responded to the wash trading allegations?

    Kalshi has denied the allegations, stating that hundreds of distinct traders participated in the transactions. The exchange attributes the repeated trade sizes to market makers maintaining fixed resting orders that were repeatedly executed by faster traders. Kalshi also noted that self-trading is mechanically blocked, coordinated wash trading is prohibited and monitored, and its liquidity programs reward order maintenance rather than volume.

    Which firms were identified as participants in the trading pattern?

    According to The Wall Street Journal, Jump Trading and Wintermute were among the firms involved in the rapid transactions. Jump Trading stated it trades for profit, uses self-match prevention tools, and does not coordinate its activity with other traders.

  • CryptoQuant CEO Ki Young Ju Predicts Bitcoin Could Surge 3-5x This Cycle

    CryptoQuant CEO Ki Young Ju Predicts Bitcoin Could Surge 3-5x This Cycle

    Key Highlights

    • CryptoQuant CEO Ki Young Ju forecasts Bitcoin appreciation of 3–5x in the current bull cycle, significantly below the 10x+ gains seen in prior cycles.
    • Growing institutional participation and market maturation are reducing both upside volatility and downside crash risk, potentially making future bear markets milder.
    • Ki argues this structural shift positions Bitcoin as a long-term capital preservation asset rather than a short-term speculative vehicle, with transformative implications for the global financial system if adoption as a functional currency accelerates.

    CryptoQuant CEO Projects Tempered Bitcoin Returns Amid Market Maturation

    CryptoQuant founder and chief executive Ki Young Ju has revised expectations for Bitcoin’s current bull cycle, suggesting the asset may climb only three to five times its present value rather than repeating the tenfold or greater surges characteristic of earlier market phases. In a post published on X, Ki attributed the moderated outlook to the cryptocurrency’s expanding market capitalization and the rising dominance of institutional investors, factors he says are fundamentally altering Bitcoin’s volatility profile.

    Institutional Growth Dampens Speculative Extremes

    Ki explained that during Bitcoin’s earlier stages, a comparatively small market cap and heavy reliance on retail participants left prices acutely sensitive to short-term speculative flows. That structure, he noted, routinely produced parabolic rallies followed by drawdowns as deep as 80 percent. As institutional capital assumes a larger share of ownership, the analyst argues, the market’s depth increases, compressing volatility in both directions and lowering the probability of both explosive melt-ups and catastrophic crashes.

    Shift Toward Long-Term Store of Value

    The CryptoQuant chief framed this evolution as a positive development for the asset class, contending that reduced cyclicality makes Bitcoin better suited for long-term capital allocation rather than short-term trading. He further speculated that should Bitcoin eventually achieve sufficient stability and gain widespread adoption as a functional medium of exchange, the resulting transformation of the global financial architecture could extend well beyond anything currently anticipated by market observers.

    Why This Matters

    Ki Young Ju’s assessment reflects a growing consensus among on-chain analysts that Bitcoin’s risk-return profile is normalizing as the asset graduates from a niche speculative instrument to an institutional-grade treasury reserve. The increasing presence of spot Bitcoin ETFs, corporate treasuries, and sovereign wealth fund allocations deepens liquidity and lengthens holder time horizons, structurally suppressing the boom-bust cycles that defined the 2013, 2017, and 2021 peaks. For investors, this implies a recalibration of expectations: lower maximum upside per cycle in exchange for shallower drawdowns and a higher probability of multi-year compounding. At a macro level, a Bitcoin that behaves more like a low-volatility monetary asset than a high-beta tech stock could accelerate its integration into global payment rails, central bank reserves, and cross-border settlement layers—a transition that would indeed reshape financial infrastructure in ways current models struggle to capture.

    Frequently Asked Questions

    What specific price multiple does Ki Young Ju expect for Bitcoin in this bull cycle?

    Ki Young Ju projects a 3–5x appreciation from current levels, contrasting with the 10x+ multiples observed in previous bull markets.

    Why does Ki believe future bear markets will be less severe?

    He cites the growing share of institutional investors and a larger market capitalization, which together deepen liquidity and reduce the influence of short-term speculative capital that historically amplified both rallies and crashes.

    Does Ki Young Ju’s analysis constitute investment advice?

    No. The original post explicitly includes a disclaimer stating “This is not investment advice.”

  • Democrats ‘chose visceral hatred for’ Donald Trump Over crypto Clarity Act, Lummis Says

    Democrats ‘chose visceral hatred for’ Donald Trump Over crypto Clarity Act, Lummis Says

    Key Highlights

    • Senator Cynthia Lummis blamed Senate Democrats for blocking a procedural vote on bipartisan crypto market structure legislation last week, calling the outcome “dismayed, dumbfounded and saddened.”
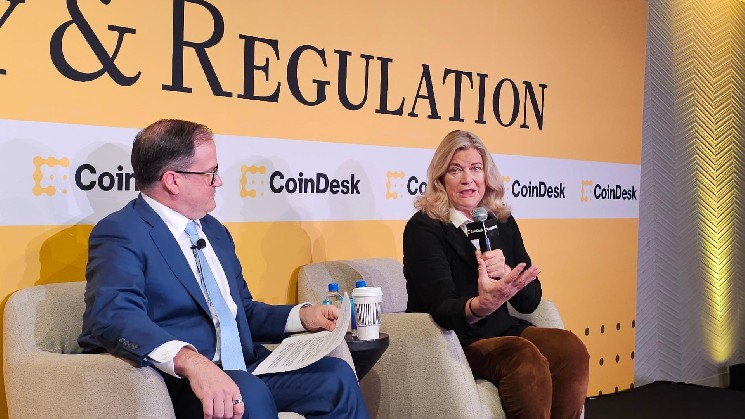
    • Speaking at CoinDesk’s Policy & Regulation event, Lummis alleged Democrats prioritized opposition to President Donald Trump over passing the bill, which had grown from 300 to over 600 pages after Democratic requests for provisions such as bankruptcy protections.
    • The legislation was the product of cross-party negotiations, but failed to advance before the midterm election cycle, leaving digital asset regulatory clarity in limbo.

    Lummis Points Finger at Democratic Opposition to Trump

    Senator Cynthia Lummis (R-Wyo.) delivered a sharp rebuke of her Democratic colleagues on Tuesday, arguing that partisan animosity toward President Donald Trump derailed a carefully negotiated crypto market structure bill that had achieved rare bipartisan consensus. Addressing attendees at CoinDesk’s Policy & Regulation event in Washington, D.C., Lummis said she was “dismayed, dumbfounded and saddened” that the Senate could not advance a key procedural vote on the measure last week.

    The Wyoming Republican framed the failure as a deliberate choice by Democrats to deny the incoming administration a legislative win ahead of the midterm elections. The problem was, as I see it, Democrats hate President [Donald] Trump more than they like good policy, and the way I see it is they chose their visceral hatred for President Trump and denied the opportunity to pass important policy legislation before a midterm, Lummis said. They chose that … pin it on the Democrats.

    Bill Expanded Significantly After Democratic Input

    Lummis emphasized that the legislation was not a partisan product but the result of extensive negotiations between members of both parties. She noted the bill had ballooned from roughly 300 pages to more than 600 after Democrats requested additional provisions addressing issues such as bankruptcy protections, among other items. Those concessions, she argued, demonstrated Republican willingness to accommodate Democratic priorities, only for the bill to stall at the procedural stage.

    The stalled measure represents the most comprehensive attempt to date to establish a clear regulatory framework for digital asset markets in the United States. Its failure to advance leaves critical questions unresolved regarding the classification of tokens, the roles of the SEC and CFTC, consumer protections, and the treatment of digital assets in bankruptcy proceedings — issues the expanded text had sought to address.

    Why This Matters

    The collapse of the bipartisan crypto market structure bill underscores how broader political dynamics — particularly the polarized response to President Trump — can override substantive policy agreement on emerging technologies. With the legislation now stalled, regulatory uncertainty continues to hamper the digital asset industry, driving activity offshore and complicating compliance for U.S.-based firms. The next opportunity for comprehensive crypto legislation will likely depend on the composition of the next Congress and whether either party chooses to revive the negotiated text or pursue a new approach. For now, the SEC and CFTC will continue to rely on existing enforcement authorities, and market participants will operate without the statutory clarity the bill was designed to provide.

    Frequently Asked Questions

    What specific provisions did Democrats request that expanded the bill?

    According to Senator Lummis, Democrats asked for provisions addressing bankruptcy protections, among other items, which caused the bill to grow from roughly 300 pages to over 600 pages.

    Was the crypto market structure bill a partisan or bipartisan effort?

    Lummis described the bill as a bipartisan product resulting from negotiations between members of both parties, though it ultimately failed to advance due to what she characterized as Democratic opposition to President Trump.

    What happens next for crypto regulation in the Senate?

    With the procedural vote blocked before the midterm elections, the legislation is effectively stalled. Future progress will depend on the next Congress’s composition and priorities, and whether lawmakers choose to revive this negotiated text or start anew.

  • Arch Lending Targets Tokenized Stocks as Next Collateral Market

    Arch Lending Targets Tokenized Stocks as Next Collateral Market

    Key Highlights

    • Arch Lending plans to launch loans backed by tokenized equities “pretty soon” as the onchain stock market surpasses $3.15 billion in distributed value.
    • Bitcoin still dominates Arch’s loan book at over 80%, though the lender reports rising demand for XRP collateral among U.S. borrowers.
    • Competitors including Ondo Finance, Kraken, and Coinbase have already integrated tokenized stocks and ETFs into lending, margin, and futures products.

    Arch Lending Targets Tokenized Equity Credit Market

    Crypto lender Arch Lending is preparing to expand its collateral offerings into tokenized equities, marking a significant step in the convergence of traditional securities and decentralized finance. Co-founder and Chief Revenue Officer Himanshu Sahay disclosed the plan during an appearance on Cointelegraph’s Chain Reaction podcast, stating the firm intends to enter the market “pretty soon” to meet growing demand for credit facilities against onchain stock holdings.

    Tokenized Equities Market Surges Past $3 Billion

    The move comes as the tokenized equities sector experiences rapid expansion. According to data from RWA.xyz, the distributed value of tokenized stocks has climbed to approximately $3.15 billion, up from roughly $630 million a year earlier. Sahay noted that while issuance has accelerated — driven by firms such as Superstate, Robinhood, and Securitize — lending infrastructure against these assets remains underdeveloped. He predicted that multiple lenders will eventually participate in the market to provide credit against tokenized equity collateral.

    Arch Diversifies Beyond Crypto-Native Assets

    Arch has already begun broadening its collateral base beyond pure cryptocurrencies. In recent weeks, the lender introduced loans backed by Paxos Gold (PAXG) and Tether Gold (XAUt), according to Sahay. Despite this diversification, Bitcoin (BTC) continues to dominate Arch’s loan book, accounting for more than 80% of outstanding credit. The firm has also observed increasing interest in XRP as collateral, particularly among borrowers in the United States.

    Competitive Landscape Heats Up

    DeFi Protocols Lead Tokenized Equity Integration

    Arch would not be the first entrant to the tokenized equity credit market. In February, Ondo Finance launched DeFi lending markets for two of its tokenized exchange-traded funds — the SPDR S&P 500 ETF and Invesco QQQ — through an integration with lending protocol Morpho on Ethereum. These tokenized ETFs can now serve as collateral for onchain borrowing.

    Centralized Exchanges Expand Utility

    Centralized platforms are also embedding tokenized equities into broader trading products. Kraken made 10 xStocks eligible to back futures and margin positions in July, while Coinbase launched its B20 stocks on the Base network in August with price-feed infrastructure designed to support DeFi borrowing and lending use cases.

    Why This Matters

    The entry of established crypto lenders like Arch into tokenized equity lending signals a maturing infrastructure for real-world asset (RWA) finance. As tokenized stocks and ETFs gain liquidity and regulatory clarity, they are becoming viable collateral for credit markets — bridging traditional portfolio assets with onchain capital efficiency. The involvement of major issuers (Superstate, Securitize, Robinhood) and exchanges (Kraken, Coinbase) suggests a multi-sided ecosystem is forming, where lending, trading, and custody of tokenized securities could eventually mirror the depth of legacy prime brokerage. For borrowers, this unlocks liquidity without selling equity positions; for lenders, it diversifies collateral risk beyond volatile crypto-native assets. The next phase will likely involve standardization of legal wrappers, oracle reliability, and cross-chain interoperability to scale these markets globally.

    Frequently Asked Questions

    What is Arch Lending’s timeline for launching tokenized equity-backed loans?
    Arch co-founder and CRO Himanshu Sahay said the firm plans to enter the market “pretty soon,” though no specific launch date was disclosed.
    Which companies currently issue tokenized equities that could serve as collateral?
    According to Sahay, firms including Superstate, Robinhood, and Securitize are issuing tokenized equities that Arch sees as potential collateral assets.
    How large is the tokenized equities market today?
    Data from RWA.xyz shows the distributed value of tokenized stocks has reached approximately $3.15 billion, up from roughly $630 million one year ago.
  • Crypto Bull Market Returns? Three Signals Indicate a Possible Comeback

    Crypto Bull Market Returns? Three Signals Indicate a Possible Comeback

    Key Highlights

    • Total cryptocurrency market capitalization surged nearly $1 trillion in six weeks, climbing from $2.06 trillion to over $2.91 trillion as Bitcoin led a broad-based recovery.
    • Spot Bitcoin ETFs recorded $999 million in net inflows—the largest single-day haul since October 2023—while combined Bitcoin and Ethereum ETF inflows reached $1.27 billion.
    • Bitcoin reclaimed all major long-term moving averages after 300 days below them, trading above both the True Market Mean ($76,746) and short-term holder cost basis ($71,763), signaling potential bull-market onset.

    Market Sentiment Shifts From Fear to Greed as Bitcoin Breaks $85,000

    The cryptocurrency market has entered a pronounced bullish phase since early August, with Bitcoin spearheading a recovery that has erased much of the bear-market damage accumulated since October 2023. In just six weeks, the aggregate crypto market capitalization has swollen from $2.06 trillion to more than $2.91 trillion, according to CoinGecko data, adding nearly $1 trillion in fresh value. The Fear & Greed Index—a widely watched sentiment gauge—has surged to 59, squarely in “greed” territory, up sharply from a “fear” reading of 45 only a week earlier. The inflection point coincided with Bitcoin’s decisive push above the $85,000 psychological threshold, a level that had acted as stiff resistance during the prolonged consolidation.

    Record ETF Inflows Signal Deepening Institutional Conviction

    Underpinning the price action is a torrent of institutional capital flowing into U.S.-listed spot exchange-traded funds. On the most recent trading day, Spot Bitcoin ETFs collectively attracted $999 million in net inflows, marking the largest single-session intake since the products drew $1.21 billion on October 6, 2023, per SoSoValue figures. BlackRock’s iShares Bitcoin Trust led the charge with $381.37 million, followed by the Ark 21Shares Bitcoin ETF at $289.12 million and Fidelity’s Wise Origin Bitcoin Fund at $238.84 million. The momentum was not confined to Bitcoin: Ethereum ETFs simultaneously pulled in $269.98 million, lifting the combined daily net inflow across both asset classes to $1.27 billion. Analysts note that the breadth of participation—spanning both the flagship cryptocurrency and its largest smart-contract rival—suggests the rally is evolving into a genuine altcoin expansion rather than a Bitcoin-only phenomenon.

    On-Chain and Technical Metrics Align With Bull-Market Thesis

    Beyond fund flows, on-chain and technical indicators are flashing constructive signals. Glassnode data shows Bitcoin has now recaptured all of its long-term moving averages after spending roughly 300 days trading beneath them—a duration that historically precedes sustained up-trends. The asset’s spot price sits comfortably above two critical cost-basis benchmarks: the True Market Mean at $76,746 and the short-term holder realized price at $71,763. Holding above these levels implies that the majority of recent acquirers are in profit, a condition that typically reinforces holder conviction and reduces sell-side pressure. Meanwhile, the rally’s breadth has flipped the Bitcoin-cycle signal in favor of altcoins, indicating capital is rotating beyond the dominant store-of-value narrative into the broader ecosystem.

    Why This Matters

    The confluence of improving sentiment, record-breaking ETF flows, and technical breakouts arrives at a pivotal juncture for digital assets. After a grueling 18-month bear market that tested institutional commitment, the simultaneous breach of $85,000 Bitcoin, the reclamation of long-term moving averages, and the rotation into altcoins mirrors the early innings of previous bull cycles in 2017 and 2020-21. However, market veterans caution that the Fear & Greed Index’s rapid ascent toward “extreme greed” (above 70) often coincides with short-term tops or sharp pullbacks. The next few sessions will test whether the current inflow momentum can absorb profit-taking from early-cycle participants without triggering a deeper correction. Regulatory clarity around stablecoins and market structure legislation in the U.S. Congress, coupled with the Federal Reserve’s evolving rate-cut trajectory, remain the key macro variables that could either extend or truncate the advance.

    Frequently Asked Questions

    What triggered the latest surge in crypto market capitalization?
    A combination of Bitcoin breaking above $85,000, record single-day inflows into Spot Bitcoin ETFs ($999M), and concurrent Ethereum ETF inflows ($269.98M) drove the total market cap from $2.06T to over $2.91T in six weeks.
    Which ETF issuers led the Bitcoin inflows?
    BlackRock’s iShares Bitcoin Trust ($381.37M), Ark 21Shares Bitcoin ETF ($289.12M), and Fidelity’s Wise Origin Bitcoin Fund ($238.84M) were the top three recipients of the $999M net inflow.
    Are technical indicators confirming a new bull market?
    Yes. Bitcoin has reclaimed all long-term moving averages after 300 days below them and trades above both the True Market Mean ($76,746) and short-term holder cost basis ($71,763)—conditions historically associated with bull-market starts. However, the Fear & Greed Index at 59 nearing “extreme greed” warrants caution for near-term volatility.
  • Filecoin Outlines Three Development Phases in Latest Update

    Filecoin Outlines Three Development Phases in Latest Update

    Key Highlights

    • Filecoin has formalized its evolution into three distinct development phases—building storage capacity, enhancing usability, and generating paid demand—under the 2026 Filecoin Network Strategy.
    • The structured roadmap aims to accelerate user acquisition and strengthen the network’s competitive position in the decentralized storage sector.
    • Current market data shows absent trading volume and thin liquidity, suggesting traders are digesting the strategic update amid mixed broader crypto signals.

    Filecoin Unveils Three-Phase Growth Framework in 2026 Network Strategy

    Filecoin, the decentralized storage protocol, has publicly outlined its progression through three significant development phases since its mainnet launch, according to an announcement from the official Filecoin account. The framework, now formalized in the 2026 Filecoin Network Strategy, segments the network’s maturation into building raw storage capacity, improving usability for developers and end users, and—beginning in 2025—driving paid demand for storage deals. The strategy signals a deliberate shift from infrastructure build-out to commercial adoption, positioning the network to attract new participants and deepen engagement across its ecosystem.

    From Capacity to Commerce: The Strategic Arc

    The first phase focused on onboarding storage providers and scaling the network’s raw capacity, establishing the physical backbone required for a credible decentralized alternative to centralized cloud providers. The second phase prioritized usability upgrades—tooling, documentation, and integration pathways—to lower the barrier for developers building on Filecoin and for clients seeking to store data. The third and current phase, initiated in 2025, centers on generating sustained paid demand, converting available capacity into revenue-generating storage deals. Filecoin’s governance, steered by its community and stakeholders, treats these phased milestones as critical markers for the protocol’s long-term market positioning.

    Market Context: Mixed Signals and Thin Liquidity

    Despite the strategic clarity, market conditions are reflecting caution. Trading volume for Filecoin’s native token is currently absent, indicating potential thin liquidity as participants assess the implications of the updated roadmap. Broader cryptocurrency markets are delivering mixed signals, which may temper immediate trader enthusiasm for Filecoin’s structural updates. Observers note that the network’s ability to translate usability improvements into measurable paid demand will be the key variable influencing both user acquisition metrics and token market dynamics in the coming weeks.

    Why This Matters

    Filecoin’s phased approach mirrors the maturation cycle seen in other decentralized infrastructure protocols, where initial supply-side incentives must eventually give way to organic, revenue-driving demand. The 2026 Filecoin Network Strategy makes this transition explicit, providing a benchmark against which the community, investors, and potential enterprise clients can measure progress. Success in the paid-demand phase would validate the economic model underpinning decentralized storage—proof that unused global capacity can be efficiently matched with paying customers without centralized intermediaries. Conversely, persistent thin liquidity and low deal flow could signal that usability barriers or macro headwinds remain higher than anticipated, affecting both network growth and token valuation.

    Frequently Asked Questions

    What are the three development phases in Filecoin’s 2026 Network Strategy?

    The three phases are: building storage capacity, enhancing usability, and generating paid demand, with the demand-generation phase beginning in 2025.

    How does the strategy affect Filecoin’s market position?

    The structured roadmap aims to attract new users and bolster network growth by shifting focus from infrastructure expansion to commercial adoption, potentially strengthening Filecoin’s competitive standing in decentralized storage.

    What should traders monitor following this update?

    Traders should watch for shifts in user engagement, paid storage deal volume, and any changes in trading liquidity as the market digests the strategic framework amid broader crypto volatility.

  • Experienced CEO’s Bold Claim: “The Fed’s Interest Rate Hike Will Benefit Bitcoin”

    Experienced CEO’s Bold Claim: “The Fed’s Interest Rate Hike Will Benefit Bitcoin”

    Key Highlights

    • CrossBorder Capital CEO Michael Howell argues a potential Fed rate hike could be stimulative for Bitcoin, not contractionary, due to increased government interest payments flowing to the private sector.
    • Howell emphasizes global liquidity and balance sheet capacity—not policy rates—as the true driver of asset prices, noting 80% of capital market transactions now fund debt refinancing rather than new investment.
    • The analyst predicts a 25 basis point hike could strengthen long-term bonds, lower yields, and reduce volatility, with Bitcoin and gold positioned to benefit from ongoing “monetary inflation” driven by short-term Treasury issuance.

    Why Higher Rates May Not Hurt Bitcoin This Time

    Conventional wisdom holds that Federal Reserve interest rate hikes are unequivocally negative for risk assets like Bitcoin. Michael Howell, CEO of CrossBorder Capital and a widely followed analyst of global liquidity dynamics, challenges that assumption. In a detailed analysis, Howell argues that the modern financial architecture has shifted so fundamentally that a rate increase could actually inject cash into the private sector, creating a tailwind for cryptocurrencies and precious metals rather than a headwind.

    The Liquidity Framework Supplanting Rate Policy

    Howell’s thesis rests on a structural transformation in global capital markets. He calculates that approximately 80 percent of primary market transactions now serve to refinance existing debt rather than fund new productive investment. In this environment, the critical variable for financial stability is not the level of the policy rate but the availability of balance sheet capacity and liquidity that allows institutions to continue rolling over obligations. “If you raise interest rates in the U.S., you’re essentially giving more cash to the private sector. This isn’t a contraction, it’s a stimulus,” Howell stated, describing a mechanical fiscal transfer where higher coupon payments on expanding public debt flow directly to bondholders.

    This dynamic, he argues, means the U.S. government’s status as a massive net debtor has inverted the traditional transmission mechanism. When the Fed raises rates, the Treasury pays more interest, which functions as a fiscal injection. Howell contends a 25 basis point increase at the next meeting could align with short-term market expectations, strengthen long-duration bonds, push yields lower, and dampen volatility across fixed income markets—outcomes that would ease financial conditions rather than tighten them.

    Monetary Inflation and the Short-Term Debt Pivot

    Central to Howell’s outlook is the Treasury’s increasing reliance on short-term bills to finance the deficit. This shift expands commercial bank balance sheets and broad money supply, a process he describes as “monetary inflation.” In this regime, assets with fixed or limited supply—gold, silver, Bitcoin, and Ethereum—tend to outperform. Historical precedent from the 2008 global financial crisis and the COVID-19 period supports the pattern: when debt rollover stress forces central banks to expand liquidity, these assets record sharp price appreciation.

    Howell emphasizes that the United States’ elevated public debt trajectory compels policymakers to maintain ample liquidity and favor short-term borrowing. Consequently, he expects liquidity conditions to remain supportive even if the Fed moves rates higher. The recent rally in both Bitcoin and gold, he suggests, may reflect markets beginning to price this new paradigm where the policy rate is a secondary concern to the pace of balance sheet expansion.

    Why This Matters

    The analysis reframes the macroeconomic playbook for digital asset investors. For over a decade, the “Fed put” narrative has conditioned markets to expect easier policy as the primary catalyst for crypto rallies. Howell’s work suggests the catalyst may instead be fiscal-driven liquidity growth that persists regardless of the federal funds rate. If correct, the correlation between Bitcoin and global liquidity metrics—rather than interest rate expectations—becomes the superior signaling tool. This also implies that traditional recession indicators tied to yield curve inversion may misfire in a system where the curve is managed through bill issuance and central bank backstops. Investors and analysts should monitor Treasury refunding announcements, repo market functioning, and broad money aggregates with at least the same rigor applied to FOMC dot plots.

    Frequently Asked Questions

    Does Michael Howell believe the Fed will raise rates at its next meeting?
    The source does not state Howell’s prediction on whether the Fed will hike. He analyzes the potential consequences if a 25 basis point increase occurs, arguing it could be bullish for liquidity-sensitive assets.
    What specific assets does Howell identify as beneficiaries of monetary inflation?
    Howell explicitly names Bitcoin, Ethereum, gold, and silver as assets highly sensitive to global liquidity expansion and likely to benefit from the current fiscal and monetary structure.
    How does the 80% debt refinancing figure change the impact of rate hikes?
    When most capital market activity services existing debt, the system’s stability depends on rollover capacity and liquidity, not borrowing costs. Higher rates then transfer income to bondholders (stimulus) rather than choking off new investment (contraction).
  • Analyst Reveals New Bullish Targets for Bitcoin and XRP

    Analyst Reveals New Bullish Targets for Bitcoin and XRP

    Key Highlights

    • Crypto analyst Ali Martinez identifies $1.60 as the critical neckline level for XRP; a decisive breakout could confirm an inverse head-and-shoulders pattern and target a 30% rally toward $2.
    • Whale accumulation exceeds $2 billion in XRP, while Bitcoin sees over 2,722 large transactions (>$1M) in a single day and U.S. spot Bitcoin ETFs add $1.6 billion in BTC over 72 hours.
    • Bitcoin’s key on-chain support zones sit at $84,569 and ~$77,000, with major resistance at $104,765 and the MVRV average band near $100,670.

    Martinez Maps Out Technical Roadmap for XRP and Bitcoin

    Prominent crypto analyst Ali Martinez has published a detailed technical breakdown for the two largest digital assets by market attention—XRP and Bitcoin—following a period of sharp price appreciation. According to Martinez, XRP surged 27.6% from $1.25 to $1.58, a move he believes may have completed the right shoulder of a large-scale inverse head-and-shoulders formation on the daily chart. The analyst emphasizes that the $1.60 level now acts as the pattern’s neckline and represents the most critical threshold for the token. A decisive breakout above this price, Martinez notes, would validate the bullish structure and open the door for an approximate 30% advance toward the $2 psychological mark.

    Whale Activity and ETF Flows Underscore Institutional Conviction

    Beyond chart patterns, on-chain data shared by Martinez highlights aggressive accumulation by large holders. Whales have added more than $2 billion worth of XRP in recent sessions, signaling deep-pocketed confidence in the asset’s next leg higher. On the Bitcoin side, the analyst points out that the flagship cryptocurrency has climbed over 50% since its July 1 low of $57,749. Despite the rapid ascent, profit-taking among major players remains muted: the Bitcoin network processed more than 2,722 transactions valued above $1 million in the last 24 hours alone. Complementing this whale activity, U.S.-listed spot Bitcoin exchange-traded funds have collectively absorbed over $1.6 billion worth of BTC in just 72 hours, reinforcing the institutional demand narrative that has underpinned the rally.

    On-Chain Metrics Define Bitcoin’s Key Battle Zones

    Support and Resistance Clusters from Realized Price and MVRV Bands

    Martinez’s on-chain cost-basis analysis identifies two primary demand zones for Bitcoin. The first sits at $84,569, where roughly 600,000 BTC previously changed hands, creating a dense cluster of realized cost. A secondary support layer emerges near $77,000. On the upside, significant supply overhead resides around $104,765, a level at which approximately 283,000 BTC were last transacted. Market-Value-to-Realized-Value (MVRV) price bands paint a similar picture: the average MVRV band near $100,670 represents the next major resistance hurdle, while the lower MVRV band around $74,361 serves as a strong support floor. These levels provide traders with a data-driven framework for gauging potential price reactions as Bitcoin approaches the six-figure milestone once again.

    Why This Matters

    The convergence of technical pattern completion, whale accumulation, and record-breaking spot ETF inflows suggests a broadening of the bullish thesis for both XRP and Bitcoin. For XRP, a confirmed breakout above $1.60 would not only validate a classic reversal pattern but also coincide with renewed legal clarity following Ripple’s partial court victories, potentially attracting fresh institutional capital. For Bitcoin, the persistence of large-holder activity during a 50%+ rally—coupled with sustained ETF demand—indicates that the current up-cycle may be driven by structural adoption rather than speculative froth. Market participants should monitor the $1.60 neckline for XRP and the $100,670 MVRV band for Bitcoin as near-term catalysts that could dictate the pace of the next directional move.

    Frequently Asked Questions

    What is the significance of the $1.60 level for XRP?

    $1.60 represents the neckline of a large-scale inverse head-and-shoulders pattern on the daily chart. Analyst Ali Martinez states that a decisive breakout above this level would confirm the bullish formation and project a measured-move target near $2, implying roughly 30% upside from the breakout point.

    How much Bitcoin have U.S. spot ETFs accumulated recently?

    According to data cited by Martinez, U.S.-based spot Bitcoin ETFs have added over $1.6 billion worth of BTC in the last 72 hours, underscoring strong institutional demand amid the recent price rally.

    What are the key on-chain support and resistance levels for Bitcoin?

    Major on-chain support zones are identified at $84,569 (approx. 600,000 BTC volume) and ~$77,000. Key resistance sits at $104,765 (approx. 283,000 BTC volume), with the average MVRV price band near $100,670 acting as an additional overhead barrier. The lower MVRV band around $74,361 provides a deeper support reference.

  • Strategy Pays $100M Premium to Repurchase Bitcoin It Previously Sold

    Strategy Pays $100M Premium to Repurchase Bitcoin It Previously Sold

    Key Highlights

    • Strategy (formerly MicroStrategy) incurred a $100.2 million opportunity cost after selling 6,948 BTC at an average of $62,150 in summer 2024 and repurchasing 5,553 BTC at an average of $80,207 this autumn.
    • The company’s founder Michael Saylor and CEO Phong Le stated the sales were executed for “messaging purposes” to “inoculate the market” rather than due to cash needs, despite SEC filings citing dividend funding.
    • Strategy still holds 1,363 fewer BTC than its June peak of 847,363, and replacing the remaining coins at current prices would require approximately $100 million more.

    Summer Sale, Autumn Rebuy: A Costly Roundtrip

    Strategy, the corporate bitcoin treasury pioneer founded by Michael Saylor, has spent recent weeks reacquiring 5,553 of the 6,948 bitcoin it liquidated between May and August 2024. The roundtrip trade has proven expensive: the company sold at an average price of $62,150 per coin, generating $345.1 million in proceeds, only to repurchase at an average of $80,207 — a 29% premium that cost shareholders $445.4 million for the same 5,553 coins. The realized opportunity cost of being out of the market during bitcoin’s summer-to-autumn rally exceeds $100.2 million.

    The first repurchase tranche arrived during the week ending August 30, when Strategy acquired 4,603 BTC at $80,318 each for $369.7 million, funded by newly issued stock that diluted common shareholders. A follow-up purchase of 950 BTC at $79,670 apiece was executed last week using cash instead of equity. Despite these outlays, the company’s holdings stand at 846,000 BTC — still 1,363 coins short of the 847,363 it held as recently as June 21. Reacquiring the remaining shortfall would demand roughly another $100 million at prevailing market prices.

    Sales Driven by Narrative, Not Necessity

    According to Saylor and CEO Phong Le, the motivation for the initial sales was not liquidity pressure but strategic messaging. On a May 5 call with analysts, Saylor stated the company would sell bitcoin “just to inoculate the market” and send a signal to news publications that it had done so. He later told Fortune, “the skeptics and the short-sellers don’t recognize that we’re just selling a $BTC derivative, and we have the option to sell the $BTC.” Both executives appeared on numerous television interviews and podcasts to frame the sales as deliberate communication rather than financial distress.

    However, official SEC filings for the sales cited dividend funding as the use of proceeds — despite the company holding sufficient cash to cover those dividends without liquidating bitcoin. The discrepancy between public statements and regulatory disclosures has drawn scrutiny from analysts and shareholders alike.

    Leadership Remains Unapologetic

    Neither Saylor nor Le has expressed regret over the sequence of trades. On the day of Strategy’s fourth sale of the year, Le posted, “This is the Digital Credit Capital Framework at work.” He subsequently told Bloomberg that it was “the right trade at the time to sell $BTC.” Le added, “It’s a two-way strategy. There will be times when it makes sense to sell bitcoin.” The comments underscore a philosophical shift toward active portfolio management — buying and selling based on capital market conditions — rather than the perpetual accumulation strategy the company previously championed.

    Why This Matters

    Strategy’s bitcoin treasury operations have long served as a bellwether for corporate digital asset adoption. The summer 2024 sell-and-rebuy episode marks the first significant deviation from the company’s “never sell” narrative, testing investor confidence in a model that previously relied on unwavering conviction. The $100 million-plus opportunity cost quantifies the financial penalty of market-timing decisions in a volatile asset class. Furthermore, the divergence between management’s public rationale (“messaging”) and SEC filing rationale (dividend funding) raises governance questions about transparency. With 1,363 BTC still un-replaced and bitcoin trading near multi-month highs, the company faces a choice: deploy additional capital at elevated prices or accept a permanently reduced bitcoin position — either outcome carrying implications for shareholders who viewed Strategy as a pure-play bitcoin proxy.

    Frequently Asked Questions

    How much bitcoin does Strategy currently hold compared to its June 2024 peak?
    Strategy holds 846,000 BTC as of the latest disclosure, down from 847,363 BTC on June 21, 2024 — a shortfall of 1,363 coins.
    What was the stated reason for the summer 2024 bitcoin sales?
    Michael Saylor and CEO Phong Le publicly stated the sales were for “messaging purposes” to “inoculate the market” and demonstrate the company’s ability to sell bitcoin as a derivative-like instrument. SEC filings, however, listed dividend funding as the use of proceeds.
    Has Strategy completed its repurchase program?
    No. The company has repurchased 5,553 of the 6,948 BTC sold. Replacing the remaining 1,363 BTC at current market prices would require approximately $100 million in additional capital.