Category: Coins

Digital assets, cryptocurrencies, blockchain, and currency news.

  • XRP Selling Pressure Hits 2026 High as Price Holds Firm Above $1.40

    XRP Selling Pressure Hits 2026 High as Price Holds Firm Above $1.40

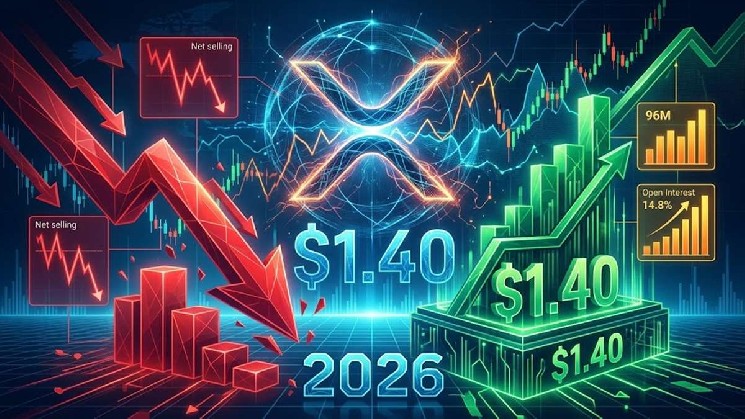
    XRP’s derivatives market is flashing its strongest net selling pressure of 2026, with Binance recording approximately $96 million in sell-side dominance. The surge follows a sharp 70% rally in XRP that has intensified speculative activity among derivatives traders. Despite the bearish signal, XRP continues to trade above $1.40 while Binance Open Interest has climbed 14.8%, signaling stronger market participation.

    Divergence Between Derivatives Selling and Spot Resilience

    The divergence between aggressive derivatives selling and resilient spot prices is giving traders a critical signal to monitor. The broader altcoin market has also strengthened in recent sessions, adding more than $183 billion in total capitalization within days. That represented an increase of roughly 20%, while XRP gained about 70% over the same period, making it one of the stronger performers during the recovery.

    XRP Selling Pressure Reaches 2026 Peak

    Data highlighted by CryptoQuant shows that XRP’s net taker volume on Binance has shifted sharply toward sellers. Sell-side dominance has reached approximately $96 million, marking the strongest reading recorded since the start of 2026.

    The metric tracks aggressive market orders and can provide insight into how traders are positioning around short-term price movements. In XRP’s case, the increase suggests that some derivatives participants are using the recent rally to take bearish positions or secure profits after the rapid advance.

    However, elevated selling activity does not automatically mean that XRP’s uptrend has ended. Strong spot demand can absorb derivatives selling, while liquidations or short-term hedging can also influence net taker volume. The current price structure therefore remains important. Holding above $1.40 despite heavier derivatives selling suggests buyers have so far absorbed the additional supply pressure.

    Binance Open Interest Adds Another Signal

    At the same time, XRP’s Binance Open Interest has increased by approximately 14.8%. The rise means more capital is entering outstanding derivatives positions as traders respond to the token’s recent move.

    Higher Open Interest combined with strong selling pressure can increase volatility because a larger number of leveraged positions are exposed to sudden price movements. If XRP continues to hold its support levels, short positions could eventually face pressure from another upside move. Conversely, a decisive break below $1.40 would strengthen the bearish interpretation and could encourage further profit-taking or liquidations.

  • Aave V4 Deposits Surge 30% Weekly to Hit Record $806M

    Aave V4 Deposits Surge 30% Weekly to Hit Record $806M

    Aave V4 Deposits Surge 30% in One Week to Record $806 Million

    Aave V4 deposits have reached a record $806 million after climbing 30% over seven days, while active loans have increased to $206 million. The milestone marks a significant acceleration for the protocol’s latest version, which has more than doubled its total value locked in less than four weeks.

    Rapid Growth Across Multiple Markets

    Aave’s on-chain dashboard shows that V4 deposits reached $806 million on Aug. 27, extending a rapid rise that began earlier in the month. Deposits passed $500 million on Aug. 19 and exceeded $600 million two days later before adding more than $200 million over the following six days.

    Within the total, V4 deposits on Ethereum passed $500 million on Aug. 25. The dashboard divides the capital among several markets with separate collateral rules, borrowing limits, and risk settings instead of placing every asset inside one common lending pool.

    Ethereum Core is the largest market, holding $378 million, or about 47% of all V4 deposits. EtherFi Cash on Optimism follows with $257 million, giving the two markets a combined $635 million and nearly 79% of the version’s deposits, based on figures from the dashboard.

    Among the remaining markets, Ethereum Global Dollar holds $75 million, and Ethereum Prime accounts for $63 million. Avalanche Core has attracted $18 million, while Ethereum Plus holds another $15 million. Combined, the six listed markets account for the full $806 million reported on the dashboard.

    The latest figures have placed V4 well above the $400 million level reported in mid-August. Deposits had stood near $350 million at the start of the month, meaning the value supplied to the system has more than doubled in less than four weeks.

    Borrowing Activity Rises in Tandem

    Borrowing has risen alongside deposits, with active V4 loans reaching $206 million. EtherFi accounts for $62 million of the total as users deposit wrapped EtherFi staked Ether, known as weETH, as collateral to borrow wrapped Ether.

    According to the dashboard, the EtherFi market has reached a utilization rate of 92%. Utilization measures the portion of deposited assets currently being borrowed, making the figure important for both lenders and borrowers. High utilization can increase returns for suppliers, but it can also raise borrowing costs and leave less immediately available liquidity for withdrawals.

    A recent crypto.news report on Aave’s debt concentration found that Ether staking and restaking tokens, including weETH, rsETH and wstETH, made up about 66.2% of collateral among the protocol’s largest leveraged positions. WeETH alone accounted for roughly 42%, while WETH represented about 73% of the debt held by that group.

    The report also found that 9% of positions carried roughly half of Aave’s total debt. Average health factors for the group stood near 1.06, while debt-to-equity ratios were close to 10.7 times, according to the analysis. A health factor below 1 can trigger an automatic liquidation under Aave’s rules.

    Such figures cover Aave’s lending system beyond the new V4 markets and therefore should not be treated as a direct measure of V4 risk. Still, they provide context for the 92% utilization recorded in the EtherFi market, where weETH collateral supports borrowing in the closely related WETH asset.

    WeETH Dominates V4 Deposit Composition

    WeETH is also the largest individual asset supplied to V4, with deposits of $97 million. The Global Dollar stablecoin, or USDG, ranks second at $90 million, followed by WETH and USDC at $81 million each.

    Liquid staking and yield-bearing assets account for several other large positions. LiquidETH holds $77 million, while liquidUSD accounts for $58 million. Wrapped Bitcoin deposits have reached $54 million, giving users another crypto asset that can be deployed under V4’s market-specific collateral settings.

    The seven named assets together represent $538 million, or about two-thirds of all V4 deposits. Other supported tokens make up the remainder of the $806 million total.

    Hub-and-Spoke Architecture Differentiates V4

    V4’s structure separates its markets into liquidity hubs and specialized spokes. Hubs manage supplied capital and accounting, while spokes set the terms for individual borrowing markets, including which collateral can be used and how much users can borrow.

    The design differs from Aave V3, where each market generally operates as its own pool. V3 still holds approximately $31 billion in deposits, nearly 38 times the amount recorded in V4. The comparison shows that most Aave capital remains in the older system even as deposits move into the new version.

    During the Aave V4 launch in April, the protocol presented the hub-and-spoke model as a way to create lending markets with tailored risk controls without dividing liquidity across entirely separate pools. Supported uses included fixed-rate loans, tokenized real-world asset collateral, and structured credit.

    Aave’s DAO had previously approved $25 million in stablecoin funding and 75,000 AAVE tokens for protocol development. The funding framework established V4 as the system’s long-term technical base while directing revenue from specified Aave Labs products to the DAO treasury.

    Avalanche Deployment Adds Tokenized Treasury Access

    Outside Ethereum and Optimism, Avalanche Core accounts for $18 million of current V4 deposits. Aave launched V4 on Avalanche in July, making the network its first V4 deployment beyond Ethereum.

    As reported in July, Aave said the Avalanche rollout would support lending markets backed by tokenized real-world assets. Planned collateral included tokenized U.S. Treasuries, money market funds, private credit and corporate bonds.

    The planned Treasury-backed markets provide a direct connection to U.S. financial assets, although on-chain access does not by itself determine whether a product can legally be offered to U.S. investors. Any access rules would depend on the issuer, the structure of the tokenized instrument, and the regulations applying to its distribution.

    Avalanche’s deployment also sits alongside an effort to reduce support for markets with little activity. In July, an Aave governance proposal targeted six deployments and dozens of low-use reserves covering about $98.1 million in supplied assets and $15.6 million in debt.

    The proposal called for retiring deployments on Sonic, Scroll, zkSync, Metis, Soneium and Aptos while removing 50 low-adoption reserves and 21 matured Pendle principal tokens from other markets. Under the proposed process, Aave would first freeze affected reserves and cut their supply and borrowing caps before gradually reducing the remaining positions.
  • Next currency crisis may be harder to contain due to stablecoins, New York Fed report finds

    Next currency crisis may be harder to contain due to stablecoins, New York Fed report finds

    A new study from the Federal Reserve Bank of New York reveals that dollar-pegged stablecoins flow more aggressively into digital wallets linked to countries undergoing currency or banking crises, highlighting a growing challenge for central banks attempting to manage capital flight.

    Crisis-Linked Wallets Show Higher Stablecoin Receipts

    Researchers Pablo Azar, Maryam Farboodi, and Nish Sinha found that wallets associated with nations experiencing financial distress were 1.8% more likely to receive dollar stablecoins during the week a crisis began. Receipt volumes across these wallets also increased significantly during those periods, according to an August staff paper published by the New York Fed.

    The analysis covered nine crisis episodes across eight countries between 2021 and 2025, including monetary disruptions, banking restrictions, sanctions, and devaluations affecting Argentina, Egypt, Iran, Myanmar, Nigeria, Russia, Turkey, and the United Kingdom.

    Methodology: Linking On-Chain Activity to Country Signals

    To trace stablecoin flows, the researchers linked Ethereum Name Service (ENS) registrations carrying country indicators—such as languages, scripts, and national identifiers—with transfer histories for 19 major dollar-pegged stablecoins.

    During crisis weeks, tagged wallets recorded both a higher probability of receiving stablecoins and larger receipt volumes. A separate specification found no significant increase in the two weeks before the shocks, while the probability of receiving stablecoins rose 1.9% during the crisis week itself.

    Sending activity increased later, with wallets becoming 1.3% more likely to send stablecoins two weeks after the crisis began. The sequence supports the researchers’ argument that demand for blockchain-based dollars rises when confidence in domestic financial arrangements comes under pressure.

    Data Limitations and Scope

    The dataset does not represent every resident or crypto wallet in the countries studied. Its roughly 4.5 million observations are wallet-event-week records, and the sample focuses on wallet-country pairs that received stablecoins at some point within a 53-week window around each crisis.

    The result therefore captures a change in behavior among wallets already connected to stablecoin activity rather than showing that stablecoin adoption rose by 1.8% across an entire national population.

    Stablecoins Complicate the Capital-Control Playbook

    The findings feed directly into a longstanding constraint on monetary policy described by the Mundell-Fleming framework: countries cannot simultaneously maintain a fixed exchange rate, unrestricted capital mobility, and independent control over domestic interest rates.

    Governments seeking to protect a currency while retaining monetary autonomy have traditionally restricted capital movement through banks and other regulated intermediaries. The New York Fed researchers model stablecoins as weakening that enforcement channel.

    A household facing restrictions on buying or transferring dollars through its bank may instead receive dollar-denominated tokens into a blockchain wallet. As access to those rails expands, the government must devote more resources to enforcement or allow more of the pressure to emerge through currency depreciation or domestic interest rates.

    The paper does not establish that stablecoins caused particular currencies to weaken during the nine episodes. Instead, the observed wallet activity supports the model’s central assumption that financial stress encourages stablecoin adoption. Its broader monetary-policy consequences remain theoretical.

    Centralized Issuers and Regulated Exchanges Remain Control Points

    Governments retain significant points of control. Major dollar tokens such as USDT and USDC are issued by centralized companies that can freeze addresses, while regulated exchanges can be required to restrict transactions or identify customers.

    Those powers shift enforcement away from a country’s banking system toward a wider network of issuers, exchanges, and blockchain addresses. Transfers between self-custodied wallets can leave governments with fewer immediate domestic chokepoints even when issuers retain the ability to intervene at other stages.

    Market Growth Amplifies Policy Challenge

    The policy challenge becomes more consequential as stablecoins expand from a niche crypto product into a global dollar-payment network. The market has already grown beyond $300 billion and is expected to reach trillions of dollars before the end of the decade.

    Blockchain analysis firm Chainalysis projects an even steeper rise in activity, estimating that adjusted stablecoin transaction volume could reach $719 trillion by 2035 through organic growth alone and approach $1.5 quadrillion if broader macro and adoption trends accelerate usage.

    That growth would increase the number of routes available to households seeking dollar exposure during periods of domestic financial stress, but it would not put stablecoins entirely beyond government reach.

    Regulatory Warnings Highlight Enforcement Gaps

    Federal Reserve Vice Chair for Supervision Michael Barr warned in June that U.S. stablecoin legislation left an illicit-finance vulnerability around secondary-market transfers involving unhosted wallets.

    The Bank for International Settlements (BIS) has identified a similar problem for monetary policy, arguing that stablecoin dollarization can threaten monetary sovereignty while restrictions may prove less effective when bearer-like tokens circulate through self-custodied wallets.

    That creates a more fragmented enforcement map. Governments can exert substantial control over banks, stablecoin issuers, and regulated trading venues, but may have less visibility or immediate reach when dollar tokens move between private wallets without returning to those intermediaries.

    Stablecoins Becoming a Macroeconomic Constraint

    The distinction becomes particularly important during a currency crisis, when demand for an alternative store of value and payment rail can rise just as authorities try to restrict capital movement.

    The New York Fed paper suggests that this choice of financial infrastructure is becoming part of the macroeconomic constraint itself. As stablecoin networks grow, effective capital mobility increasingly depends on both the controls governments impose and the blockchain rails households can still access.

    At the scale projected for the next decade, that could turn stablecoins from an alternative payment mechanism into a material constraint on how governments defend currencies during periods of financial stress.

  • Connecticut Sues Kalshi Over Sports Prediction Contracts

    Connecticut Sues Kalshi Over Sports Prediction Contracts

    Connecticut has filed a lawsuit against prediction market operator Kalshi, escalating a nationwide legal battle over whether such platforms can offer sports-related contracts without state gambling licenses. The action, filed Thursday by Attorney General William Tong, alleges that Kalshi’s sports contracts function as traditional sports wagers and violate state consumer protection laws.

    State Alleges Unlicensed Sports Gambling

    The complaint targets contracts covering team wins, game scores, and point spreads. Connecticut officials contend these products cross the line into unlicensed sports gambling, an activity reserved for licensed operators under state law. The lawsuit follows a 2023 enforcement order directing Kalshi and two other platforms to cease offering unlicensed sports wagering to Connecticut residents.

    Kalshi Claims Federal Preemption

    Kalshi has challenged Connecticut’s authority in federal court, arguing its contracts qualify as regulated financial instruments under the Commodity Exchange Act. The company maintains that the Commodity Futures Trading Commission (CFTC) holds exclusive jurisdiction over its markets, preempting state gambling regulations.

    Regulatory Conflict Expands Across States

    Connecticut’s lawsuit opens a new front in Kalshi’s growing regulatory challenges. New York has launched a similar challenge against the company’s sports prediction markets. Meanwhile, a federal court recently blocked Minnesota from enforcing a ban against prediction markets, a ruling that bolstered Kalshi’s argument for federal oversight.

    However, a Connecticut judge recently denied Kalshi’s motion to halt the state’s enforcement efforts. The company has appealed that decision.

    National Implications for Prediction Markets

    The outcomes of these cases could define how regulators classify prediction markets across the United States. The central question remains whether states retain the power to regulate sports-related event contracts independently, or whether federal commodities law provides a complete shield for platforms like Kalshi.

  • Polygon Falls 12% Amid Heavy Selling Pressure; Can POL Recover?

    Polygon Falls 12% Amid Heavy Selling Pressure; Can POL Recover?

    Polygon (POL) is facing significant downside pressure after its recent uptrend collapsed at the $0.12 resistance level. The altcoin has now closed at lower lows for two consecutive sessions, breaching the $0.11 support floor to hit an intraday low of $0.105. At the time of writing, POL was changing hands near $0.108, representing a 12.3% decline on the daily chart. Trading volume has also contracted sharply, falling 34% to $157 million, signaling a notable reduction in market participation.

    Polygon Faces Intense Bearish Pressure

    The rejection at $0.12 on August 25 came despite a massive 690% surge in exchange outflows, a metric typically associated with strong buying pressure, according to data from CoinGlass. However, that buying momentum proved short-lived as investors quickly shifted to selling, driving the asset lower under heavy bearish pressure.

    Derivatives Data Shows Leverage Exiting the Market

    On the derivatives front, the bearish narrative is reinforced by declining open interest and volume. CoinGlass data indicates that POL’s Open Interest dropped 11.3% to $111 million, while derivatives volume plunged 38% to $157 million. The simultaneous decline in both metrics suggests that leverage is leaving the market, with traders actively closing positions rather than opening new ones.

    Futures market flows corroborate this trend. Over the past 24 hours, POL recorded $49.43 million in futures outflows against $39.3 million in inflows, resulting in a netflow decline of 196% to negative $3.04 million.

    Spot Market Sell Volume Dominates

    Seller dominance extends to the spot market. Data from Coinalyze shows that Polygon registered 139 million in sell volume over the same period. Historically, such persistent selling pressure across both spot and derivatives markets weakens market structure and often precedes further price declines.

    Technical Indicators: Mixed Signals

    From a technical perspective, the Relative Strength Index (RSI) has formed a bearish crossover, dropping to 69. While this crossover signals rising selling momentum, the RSI remains within the bullish zone (above 50), indicating that both buyers and sellers are active, though sellers have not yet fully seized control.

    Conversely, the Directional Movement Index (DMI) paints a more resilient picture. The Positive Directional Indicator (DI+) jumped to 45, while the Negative Directional Indicator (DI-) fell to 12, with the Average Directional Index (ADX) rising to 50. This configuration suggests that upward momentum remains strong and has historically preceded trend continuation. Despite aggressive selling, bulls appear to be holding the line, keeping the uptrend intact.

    Key Support Levels to Watch

    The immediate battleground is the $0.10 psychological support level. If buyers can defend this floor, a recovery toward the $0.12 resistance is likely, with $0.14 serving as the next key upside target. However, a failure to hold $0.10 would likely trigger a deeper correction toward $0.094.

    Final Summary

    • POL faced rejection at $0.12, dropping 12.3% and breaking below $0.11 support to a low of $0.105.
    • The decline was driven by heavy selling pressure across spot and derivatives markets.
    • Derivatives data shows leverage exiting (falling Open Interest) and negative futures netflows.
    • Technical indicators are mixed: RSI shows bearish crossover but remains bullish; DMI/ADX signals strong underlying uptrend momentum.
    • $0.10 support is critical; a hold could lead to a reclaim of $0.12, while a break targets $0.094.

    Sources: CoinGlass, Coinalyze, TradingView

  • Fidelity Executive Comments on U.S. Treasury’s Latest Bitcoin Move

    Fidelity Executive Comments on U.S. Treasury’s Latest Bitcoin Move

    Fidelity Investments’ Global Macro Director Jurrien Timmer argues that recent U.S. Treasury operations—specifically increased long-term bond buybacks paired with heightened short-term bill issuance—are pressuring the dollar while providing tailwinds for Bitcoin and gold.

    Treasury Buybacks Weaken Dollar, Lift Bitcoin and Gold

    Timmer observed that the dollar declined last week following the Treasury’s repurchase of additional long-term bonds funded by issuing more short-term securities. He contends the concurrent sharp rally in both gold and Bitcoin prices signals market anticipation of shifts in fiscal and monetary policy frameworks.

    According to the analyst, investors may have started pricing in a potential transition toward what is increasingly termed “fiscal dominance” in the United States, alongside a perceived erosion of Federal Reserve independence.

    “It is noteworthy that the U.S. Treasury Department’s issuance of more short-term Treasury bills last week while simultaneously buying back more long-term bonds dragged the dollar down and caused both gold and Bitcoin to rise sharply. The market senses a slippery slope towards fiscal dominance and a possible loss of the Federal Reserve’s independence.”

    Larger Buybacks May Require Fed Involvement

    Timmer suggests that for the Treasury’s strategy to effectively suppress long-term yields, the repurchase program may need to expand significantly beyond current levels. Such an expansion, he notes, could compel Federal Reserve participation in what amounts to an “Operation Maturity Restructuring” aimed at altering the maturity profile of the bond market.

    He warns this trajectory carries heightened currency depreciation risks.

    “For the U.S. Treasury Department to successfully keep interest rates low, it may need to significantly increase the size of repurchases. This could require the Federal Reserve to become involved in this Operation Maturity Restructuring policy, and could lead us down a path of currency depreciation.”

    Expansionary Policy Mix Favors Bitcoin

    The Fidelity executive emphasizes that the simultaneous pursuit of expansionary fiscal policy and accommodative monetary policy creates a distinctly negative outlook for the dollar. With the greenback testing a significant long-term trend line, Timmer views this macroeconomic backdrop as structurally positive for gold, adding that Bitcoin stands to benefit from the same dynamics.

    This is not investment advice.

  • Aave V4 Deposits Surge to $806M on 30% Weekly Gain

    Aave V4 Deposits Surge to $806M on 30% Weekly Gain

    Aave V4 Deposits Surge 30% in a Week to Record $806 Million

    Aave’s Version 4 protocol has reached a new all-time high in user deposits, hitting $806 million according to the platform’s live onchain dashboard. The figure represents a 30% increase over the past seven days and extends a steep growth trajectory that began in mid‑August.

    Rapid August Milestones

    Separate protocol announcements tracked the ascent: V4 deposits crossed $500 million on August 19, breached $600 million two days later, and surpassed $800 million six days after that. A further update noted that Ethereum‑based V4 deposits alone exceeded $500 million on August 25. EtherFi Cash has emerged as the second‑largest market within the V4 ecosystem.

    Borrowing Activity Grows Alongside Deposits

    The dashboard shows $216 million in active loans across V4. In the EtherFi Cash market specifically, Aave measured $62 million of active loans where weETH collateral backs WETH borrowing at 92% utilization.

    Deployment Breakdown by Network and Market

    V4 is currently deployed on Ethereum, Optimism, and Avalanche. The largest market by deposits is Ethereum Core at $378 million, followed by EtherFi Cash on Optimism at $257 million. Ethereum Global Dollar holds $75 million, Ethereum Prime $63 million, while Avalanche Core and Ethereum Plus account for $18 million and $15 million respectively.

    Asset Composition of Deposits

    The deposit mix is led by weETH at $97 million and USDG at $90 million. WETH and USDC each represent $81 million, followed by liquidETH ($77 million), liquidUSD ($58 million), and WBTC ($54 million).

    V3 Still Dominates Total Liquidity

    Despite V4’s rapid growth, Aave’s V3 protocol retains a far larger deposit base. The equivalent V3 dashboard shows $31 billion in user deposits, with Ethereum Core alone holding $25 billion.

    Architectural Shift: Hub‑and‑Spoke vs. Market‑per‑Pool

    The two versions organize liquidity differently. According to Aave’s documentation, V4 replaces V3’s market‑per‑pool design with a hub‑and‑spoke system. Hubs consolidate liquidity and accounting, while spokes apply separate borrowing rules and risk limits to particular markets.

    EtherFi Cash Targets $500 Million Lending Capacity

    On August 27, TokenLogic reported that the EtherFi Cash market had been live for two weeks and was progressing toward a $500 million lending‑capacity target.

  • WSJ: UAE Royal Sheikh Tahnoon Bin Zayed Holds 49% Stake in Trump-Linked World Liberty Financial Banking Venture

    WSJ: UAE Royal Sheikh Tahnoon Bin Zayed Holds 49% Stake in Trump-Linked World Liberty Financial Banking Venture

    UAE National Security Adviser Reportedly Holds 49% Stake in Trump-Linked Crypto Banking Venture

    The Wall Street Journal reports that Sheikh Tahnoon bin Zayed Al Nahyan, the United Arab Emirates’ national security adviser, holds a 49% stake in the banking venture of World Liberty Financial (WLFI), the cryptocurrency project associated with the Trump family. The report identifies Sheikh Tahnoon as a key backer and shareholder of the U.S. bank that WLFI is preparing to launch through its unit, World Liberty Trust.

    Regulatory Milestone: OCC Conditional Approval

    The Office of the Comptroller of the Currency (OCC), the primary U.S. federal banking regulator, has conditionally approved a bank charter for World Liberty Trust. This conditional approval represents a significant regulatory step for the venture, though it remains subject to specific conditions and final authorization. The OCC’s decision allows the charter process to advance while the applicant works to meet all regulatory requirements.

    Profile: Sheikh Tahnoon bin Zayed Al Nahyan

    Sheikh Tahnoon serves as the UAE’s national security adviser and is a member of the Abu Dhabi royal family. Often referred to as the “spy sheikh” due to his intelligence portfolio, he is a prominent figure in Emirati finance and technology investment. His reported involvement adds a substantial international dimension to the Trump family’s cryptocurrency banking initiative, prompting questions about foreign investment in U.S. financial institutions and the regulatory scrutiny such arrangements attract.

    Implications for Crypto-Banking Convergence

    This development underscores the accelerating intersection between traditional banking and cryptocurrency, as well as the growing participation of sovereign-linked investors in U.S. financial ventures. If finalized, the bank would mark a notable entry of a crypto-aligned entity into the regulated U.S. banking system.

    However, the involvement of a foreign royal family member raises potential concerns regarding national security and compliance with U.S. banking laws, particularly around foreign ownership thresholds and influence. The OCC’s conditional approval suggests these issues are under active review, but the final outcome remains uncertain.

    Why This Development Matters

    For industry observers, this story highlights the evolving landscape of cryptocurrency regulation and the complex relationships between political figures, financial innovation, and international capital. The outcome could set a precedent for how crypto-related banking ventures are treated by U.S. regulators, especially when foreign stakeholders hold significant equity positions.

    Key Facts at a Glance

    • Entity: World Liberty Financial (WLFI) / World Liberty Trust
    • Reported Stakeholder: Sheikh Tahnoon bin Zayed Al Nahyan (49% per WSJ)
    • Regulatory Status: Conditional bank charter approval from the OCC
    • Significance: Potential first crypto-aligned bank with major foreign sovereign-linked ownership

    Related Developments

    This is a developing story. Further details are expected to emerge as regulatory processes advance and additional reporting becomes available.

  • Moving Self-Custody Bitcoin to Wall Street Now 25 Times Easier, $5 Billion Already Transferred

    Moving Self-Custody Bitcoin to Wall Street Now 25 Times Easier, $5 Billion Already Transferred

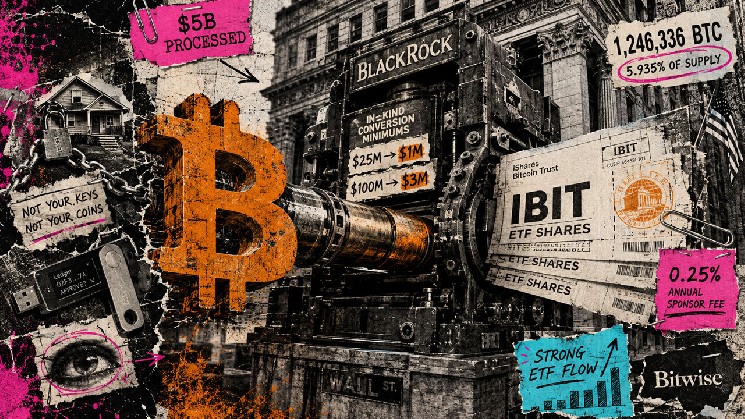
    BlackRock and Bitwise Slash Minimums for In-Kind Bitcoin-to-ETF Conversions

    BlackRock has reduced the minimum transaction size for converting privately held Bitcoin into shares of its iShares Bitcoin Trust (IBIT) from $25 million to $1 million, a 96% cut confirmed to Bloomberg in July. Bitwise followed with an even steeper reduction, lowering its floor from an initial $100 million to $50 million and now to $3 million—a 97% total decline. While the dollar thresholds still exclude most retail investors, the moves signal a structural shift: institutional custody is evolving from a niche whale service into a repeatable wealth-management product.

    In-Kind Creation Removes Friction and Potential Tax Events

    The mechanics rely on in-kind creation, a process the SEC approved for crypto exchange-traded products (ETPs) in July 2025, ending the original cash-only restriction. An eligible holder transfers Bitcoin through an authorized participant; the trust issues ETF shares at settlement, and the intermediary credits those shares to the holder’s brokerage account. This compresses what was previously a multi-step sequence—selling Bitcoin, wiring dollars, and repurchasing ETF exposure—into a single institutional transaction.

    The efficiency gain is more than operational. Selling Bitcoin can realize a taxable gain, while in-kind transactions may defer that gain for some holders. Because the tax outcome depends on the holder’s legal structure, each conversion requires individual tax advice. BlackRock says the program has already processed more than $5 billion in conversions to date.

    Wealth-Management Channels Expand Access

    A referral program announced in June by Morgan Stanley and Galaxy illustrates how the workflow is embedding into wealth management. Eligible clients lend crypto to Galaxy, which coordinates an in-kind creation with an authorized participant before ETF shares arrive in the client’s chosen account. Galaxy cut its minimum for referred clients from $25 million to $5 million and said onboarding that can exceed four weeks may be shortened by up to 75%.

    Activity data underscores the trend. Grayscale completed 62% of its gross Bitcoin creations in kind in June, up from 28% in March. At 21Shares, completed transactions averaged about $5 million over the three months through July, according to Bloomberg.

    US Spot Bitcoin ETFs Now Hold Nearly 6% of Total Supply

    Institutional adoption is measurable on-chain. As of August 25, US spot Bitcoin ETFs collectively held 1,246,336 BTC across 13 funds, equal to 5.935% of the 21 million supply, per Bitbo. IBIT alone held 765,389.9 BTC (3.645% of supply), with BlackRock reporting net assets of $60.65 billion on the same date.

    Physical Security Risks Drive Custody Reassessment

    BlackRock’s head of digital assets, Robbie Mitchnick, told Bloomberg that kidnappings, ransom demands, and custody failures can motivate holders to move some or all of their coins into an ETF. The company has not broken down the $5 billion in conversions by motive, so the crime data provides environmental context rather than direct causation.

    The physical threat is quantifiable. Chainalysis documented 46 violent crypto incidents through late June 2026, estimating attackers successfully stole more than $30 million in the first half of the year—already over half of 2025’s record $58 million. Only 12 of the 46 attempts produced a payment. CertiK counted 52 verified incidents in the same period, up 33.3% year-over-year, with $124.1 million in recorded exposure (a broader measure including losses and ransom demands). Home invasions jumped from one to 20 incidents year-over-year, while kidnappings rose from 12 to 16.

    Self-custody removes intermediaries from the authorization chain, leaving the holder as the final signer. A properly secured wallet resists remote theft, but a criminal inside the home can target the person who controls the seed phrase, hardware device, or second multisig signer. The true cost of self-custody therefore extends far beyond a hardware wallet: multisig coordination, inheritance planning, private security, reporting, and recovery all consume capital or attention. BlackRock describes IBIT as a way to simplify the operating and custody complexity of direct ownership.

    Trade-Offs: Sponsor Fees and Concentrated Custody

    IBIT carries a 0.25% annual sponsor fee and depends on brokerage and market infrastructure. The owner holds a security tracking Bitcoin’s price while the fund’s custodians retain the coins. Direct custody preserves the ability to withdraw, transfer on-chain, and verify assets in a personal wallet.

    Moving coins into ETFs reduces individual key risk but concentrates Bitcoin inside a smaller set of institutional firms. CryptoSlate calculated in April that funds naming Coinbase as a custodian or primary custodian represented 84.1% of US Bitcoin ETF assets under a broad method; a stricter count excluding multi-custodian funds with undisclosed allocations still reached 80.8%, or about $74.06 billion. Those percentages describe funds connected to Coinbase in some custody capacity; exact allocations among providers remain undisclosed.

    The custody map is diversifying. BlackRock’s documents name Anchorage as an available additional custodian. ARK lists Coinbase alongside BitGo and Anchorage. Fidelity uses its own digital-asset subsidiary, and VanEck uses Gemini. The market can therefore move more coins into institutional custody while distributing them among more providers.

    Parallel Demand Channels: Fresh Capital and Existing Coins

    The conversion program is widening amid a fresh burst of ETF demand. Farside data show US spot Bitcoin ETFs absorbed $2.57 billion across seven positive sessions from August 17 through August 25, with IBIT capturing $1.82 billion (71% of the total). Daily net inflows and direct Bitcoin conversions measure different activity and belong in separate datasets, but together they show two routes operating simultaneously: new capital buying ETF shares while existing coin holders gain a cheaper path to place Bitcoin they already own inside the same funds.

    Self-Custody Remains an Option as Institutional Packaging Gets Cheaper

    Bitcoin’s protocol still lets holders control an asset that can move anywhere the network reaches. Wealthy owners can continue paying for the security, coordination, and recovery systems that direct control requires. Wall Street now sells Bitcoin price exposure in a conventional account and assumes much of that operational burden for qualifying clients. The self-custody option stays available as the fund industry cuts the entry price for its packaged solution by 96% at BlackRock and 97% at Bitwise. More than $5 billion has already passed through IBIT, demonstrating how institutional adoption advances through coins leaving private wallets alongside dollars arriving from buyers who never held Bitcoin.

  • Virtu, Tradeweb Complete On-Chain Repo Using Marshall Islands Digital Bond

    Virtu, Tradeweb Complete On-Chain Repo Using Marshall Islands Digital Bond

    Virtu Financial, M1X Global, and Tradeweb have completed an on-chain repurchase agreement (repo) transaction using a sovereign digital bond as collateral, with the full transaction settling on the Canton Network. The milestone marks the first repo to combine natively issued sovereign collateral with fully on-chain atomic settlement between regulated counterparties.

    Sovereign Digital Bond Used as Collateral

    The transaction utilized USDM1, a U.S. dollar-denominated sovereign bond issued on-chain by the Republic of the Marshall Islands. The bond is backed 1:1 by short-term U.S. Treasurys, pays a coupon while serving as collateral, and is structured under New York law as a fully collateralized sovereign obligation. USDM1 is available for trading on Tradeweb, with institutional custody provided by Anchorage Digital, BitGo, and tZERO.

    Atomic Settlement in Under 10 Minutes

    Executed on Tradeweb’s electronic trading platform, the complete repo and repurchase cycle settled in under 10 minutes. Both companies confirmed this represents the first instance of tokenized sovereign debt being used as collateral in an institutional financing transaction, rather than solely as an asset for issuance or trading. The model remains an early-stage example, and broader adoption across institutional repo markets is not yet certain.

    Canton Network Sees Accelerating Institutional Activity

    Canton is a blockchain network designed for institutional finance, featuring privacy and permissioning capabilities tailored for regulated transactions and tokenized assets. Thursday’s repo follows a July transaction where Tradeweb facilitated the real-time transfer of a tokenized U.S. Treasury from Franklin Templeton to Virtu Financial on Canton, settling against USDCx.

    Network activity accelerated significantly in August. FalconX and Interstice launched a cross-chain swap engine connecting Canton with Ethereum, Solana, and Robinhood Chain. Simultaneously, World Liberty Financial launched its USD1 stablecoin natively on the Canton Network.

    2027 Pilot for State Benefits Distribution

    Digital Asset and the American Idea Foundation, founded by former U.S. House Speaker Paul Ryan, also announced plans this month for a 2027 pilot. The initiative would use the Canton Network to distribute state-administered benefits across three U.S. states, further signaling growing institutional interest in permissioned blockchain infrastructure for regulated financial workflows.