Author: Evan Mercer

  • Bitcoin Bounces as Markets Brace for the Fed’s Next Move

    Bitcoin Bounces as Markets Brace for the Fed’s Next Move

    Key Highlights

    • The Federal Reserve raised its benchmark interest rate by 25 basis points to 3.75%–4% on a unanimous 12–0 vote, marking the first hike since July 2023.
    • Bitcoin held near $76,300, largely unmoved by the decision, while the broader crypto market capitalization stabilized around $2.63 trillion.
    • Zcash (ZEC) surged up to 23% to a multi-year high near $1,425 after Paradigm co-founder Matt Huang disclosed his firm’s stake, calling it “a private complement to Bitcoin.”

    Fed Delivers Expected Hike; Crypto Markets Absorb Move With Composure

    Bitcoin traded sideways near $76,300 on Thursday, showing remarkable resilience a day after the Federal Reserve executed its first interest rate increase since July 2023. The Federal Open Market Committee lifted the federal funds rate by 25 basis points to a target range of 3.75% to 4%, a decision backed by all 12 voting members. Heading into the announcement, CME’s FedWatch tool indicated traders had priced in a 93% probability of the move, which helped mute immediate volatility across digital asset markets.

    While traditional markets reacted more sharply—the Dow Jones Industrial Average fell roughly 1.2% and the S&P 500 declined 0.4% to 0.5% on Wednesday—cryptocurrency prices steadied by Thursday morning. The 10-year Treasury yield, which had breached 5% earlier in the week for the first time since 2007, retreated slightly, and equity futures turned positive. Oil prices also pulled back from highs above $100 a barrel driven by the Israel–Iran conflict. These developments eased the dual headwind of a stronger dollar and higher risk-free yields that typically pressure non-yielding assets like Bitcoin and gold.

    Zcash Breaks Out on Paradigm Endorsement and Privacy Narrative

    While major tokens traded in tight ranges, Zcash (ZEC) erupted as much as 23% to trade near $1,425, hitting a multi-year high. The catalyst came after Paradigm co-founder Matt Huang disclosed on X that his venture firm holds a position in ZEC and has invested in the Zcash Open Development Lab. Huang called Zcash “a private complement to Bitcoin” and argued its inflation-funded developer fund deserves continued backing as AI-driven cyber threats and quantum computing advance.

    The rally extends a powerful run for the privacy-focused cryptocurrency. ZEC has gained approximately 160% over the past month, vastly outperforming Bitcoin’s 18.2% climb in the same period, and is up nearly 3,000% over the trailing 365 days. In May, Multicoin Capital’s Tushar Jain revealed a position built since February, describing the token as “the cleanest way” to express a privacy thesis rooted in wealth-seizure fears. Those disclosures have helped make Zcash the standout performer among the top 10 cryptocurrencies by market capitalization this week.

    Broader Market Context: Liquidations, Legislative Setback, and Sentiment Shift

    Elsewhere in the top 50, gains were more modest. BNB traded near $724 (up 2%), Solana held just above $100 for a 3.3% increase, and XRP lagged at $1.29—up 2% on the day but still down more than 6% for the week. XRP’s weekly decline followed the failure of the crypto Clarity Act to secure a Senate cloture vote days earlier. The legislation would have legalized most crypto activity in the United States and provided more meaningful regulatory clarity for altcoins such as Solana and XRP than for Bitcoin, which is widely recognized to occupy a distinct regulatory category.

    Leveraged positions felt the pressure as prices ground higher into the rate decision. Roughly $373 million in crypto liquidations hit the market over 24 hours, with short positions accounting for the larger share. Sentiment indicators reflect the cooling enthusiasm: the Crypto Fear and Greed Index read 50, exactly in “neutral” territory, a significant drop from the “extreme greed” readings recorded just three weeks ago.

    Why This Matters

    The Fed’s latest hike signals that the central bank remains vigilant on inflation despite growing risks to economic growth. The median “dot plot” projection places the federal funds rate at 4.1% by the end of 2026, leaving room for one more quarter-point move this cycle. The next FOMC meeting is scheduled for October 27–28, and markets will closely parse incoming labor and inflation data for clues on whether that final hike materializes.

    For crypto, the relatively muted reaction suggests the rate path was well-telegraphed and that the market is increasingly focused on idiosyncratic catalysts—such as the privacy narrative driving Zcash—rather than macro surprises. The failure of the Clarity Act underscores that regulatory uncertainty remains a persistent overhang for altcoins, even as Bitcoin continues to decouple from traditional risk assets in the eyes of some investors. With the Fear and Greed Index resetting to neutral, the stage is set for the next directional move to be driven by either a macro shock or a breakthrough in protocol-level adoption.

    Frequently Asked Questions

    How did Bitcoin react to the Fed’s rate hike?

    Bitcoin briefly touched $76,499 after the announcement before settling near $76,300, roughly flat on the day. The muted response reflects the fact that traders had priced in a 93% probability of the 25-basis-point increase, per CME’s FedWatch tool.

    Why did Zcash (ZEC) surge while other cryptocurrencies were flat?

    Zcash jumped as much as 23% after Paradigm co-founder Matt Huang disclosed his firm’s stake and investment in the Zcash Open Development Lab. Huang called ZEC “a private complement to Bitcoin”, and the token has benefited from a growing privacy narrative amid concerns over AI-driven cyber threats and quantum computing.

    What is the Fed’s projected rate path and next meeting date?

    The Fed’s median projection sees the federal funds rate at 4.1% by the end of 2026, implying one more potential quarter-point hike. The next FOMC meeting is scheduled for October 27–28.
  • Tokenovate Completes Repo Settlement on Canton

    Tokenovate Completes Repo Settlement on Canton

    Key Highlights

    • Tokenovate executed a full-lifecycle intraday repurchase agreement on the Canton Network using the FINOS Common Domain Model for trade representation.
    • Cash settlement utilized Circle-issued USDC stablecoin, represented as USDCx Reserve on the Canton Network.
    • Tokenovate has joined the Canton Foundation as a General Member to participate in network governance and development.

    Tokenovate Demonstrates End-to-End Repo Automation on Canton Network

    Tokenovate, a technology provider specializing in post-trade automation for financial markets, has successfully completed an intraday repurchase agreement transaction on the Canton Network. The demonstration marks a significant step in applying distributed ledger technology to traditional secured funding markets, covering the complete repo lifecycle from trade inception through final settlement.

    The transaction leveraged the FINOS Common Domain Model (CDM) as the standard for trade representation and lifecycle events. FINOS, the Fintech Open Source Foundation, maintains the CDM as an open-source standard designed to harmonize data and processes across the financial industry. By building the repo workflow on this model, Tokenovate aimed to showcase how standardized digital representation can reduce operational friction and reconciliation burdens that typically characterize collateralized lending.

    Stablecoin Settlement via Circle’s USDC on Canton

    Cash settlement for the repo was executed using USDC issued by Circle, represented on the Canton Network as USDCx Reserve. This implementation demonstrates the integration of regulated, fiat-backed stablecoins into institutional settlement workflows. The use of a permissioned blockchain environment allowed the transaction to occur within a controlled setting that adheres to existing legal documentation standards for repurchase agreements, including master repurchase agreements and global master repurchase agreements commonly used in wholesale markets.

    According to Tokenovate, the controlled environment test validated critical operational stages: trade creation, collateral allocation and movement, processing of corporate actions and other lifecycle events, and the simultaneous settlement of both the cash and collateral legs of the transaction. The firm emphasized that the workflow followed established market documentation, signaling a path toward production readiness without requiring fundamental changes to legal frameworks.

    Canton Network Architecture and Tokenovate’s Strategic Membership

    The Canton Network is a blockchain platform architected specifically for financial institutions, prioritizing data privacy, interoperability, and regulatory compliance. Unlike public permissionless chains, Canton employs a synchronized, multi-party architecture that allows institutions to maintain control over their data while enabling atomic, cross-ledger transactions. This design addresses core institutional requirements around confidentiality and settlement finality.

    Concurrent with the technical milestone, Tokenovate announced its membership in the Canton Foundation as a General Member. The foundation governs the network’s evolution, standards, and ecosystem development. As a member, Tokenovate will contribute to the roadmap and governance of the network, aligning its post-trade automation tooling with the protocol’s direction. This positions the firm to influence how smart-contract logic, asset representation, and privacy controls evolve for securities financing and broader capital markets use cases.

    Why This Matters

    The successful test signals growing convergence between traditional securities financing infrastructure and blockchain-based settlement layers. Repurchase agreements represent a multi-trillion-dollar market central to global liquidity management, yet they remain burdened by manual processes, T+1 or T+2 settlement cycles, and reconciliation overhead. By demonstrating a full lifecycle on Canton with FINOS CDM standardization and Circle’s USDC, Tokenovate illustrates a potential pathway to intraday, atomic settlement—reducing counterparty risk, freeing collateral faster, and lowering operational costs. The move also highlights the increasing role of regulated stablecoins as settlement assets in permissioned institutional networks, a trend watched closely by central banks, custodians, and market infrastructure providers. Tokenovate’s foundation membership suggests ongoing investment in making this capability production-grade for buy-side and sell-side firms.

    Frequently Asked Questions

    What is the FINOS Common Domain Model and why was it used?

    The FINOS Common Domain Model (CDM) is an open-source standard for representing financial trade data and lifecycle events. Tokenovate used it to ensure the repo transaction adhered to industry-agreed data standards, promoting interoperability and reducing the need for bespoke translation between systems.

    How does USDCx Reserve differ from standard USDC on public blockchains?

    USDCx Reserve is the representation of Circle-issued USDC on the Canton Network. It exists within Canton’s permissioned, privacy-preserving architecture, allowing institutional participants to settle with a regulated stablecoin while maintaining data confidentiality and compliance controls not available on public chains.

    What does Tokenovate’s Canton Foundation membership entail?

    As a General Member, Tokenovate gains voting rights and participation in the governance of the Canton Network. This includes influencing technical roadmap priorities, standards development, and ecosystem initiatives—enabling the firm to shape the network’s evolution for post-trade automation use cases.

  • Bitcoin, Altcoin Whale Activity Surges After Fed Decision: Traded Tokens Revealed

    Bitcoin, Altcoin Whale Activity Surges After Fed Decision: Traded Tokens Revealed

    Key Highlights

    • Bitcoin maintains support above $76,000 despite the Clarity Act vote failure and Federal Reserve interest rate hike, with Ethereum trading in a $2,370–$2,430 range.
    • Chinese whale Garrett Jin withdrew 35,001 ETH ($85 million) from Binance to Hyperliquid, likely to fund a 37,760 ZEC short position worth $51.5 million.
    • Bitcoin miner Jiang Zhuoer, founder of BTC.top, has repurchased all previously sold BTC and forecasts a price target of $80,000–$84,000 citing strong buying momentum.

    Bitcoin Resilience Amid Macro Headwinds

    Bitcoin demonstrated notable stability on Wednesday, holding above the $76,000 threshold despite a confluence of negative catalysts. The cryptocurrency market absorbed the rejection of the Clarity Act—a key regulatory framework for digital assets—and a Federal Reserve interest rate hike decision without triggering a sharp sell-off. Analysts suggest the Fed’s move was largely priced into the market beforehand, limiting immediate volatility. Ethereum, the largest altcoin, consolidated within a tight $2,370 to $2,430 band, while major alternatives such as XRP and Solana showed muted initial reactions, indicating a cautious but not panicked risk appetite among investors.

    Whale Activity Signals Strategic Positioning

    While macro factors provided the backdrop, on-chain analytics revealed aggressive maneuvering by major capital holders, suggesting high-conviction bets on specific assets and volatility plays.

    Garrett Jin’s Major ETH Transfer to Hyperliquid

    According to data from cryptocurrency analysis platform Lookonchain, a wallet attributed to Chinese whale Garrett Jin executed a significant withdrawal of 35,001 Ethereum (ETH), valued at approximately $85 million, from the Binance exchange to the decentralized exchange Hyperliquid. The same entity currently holds a short position of 37,760 Zcash (ZEC), worth roughly $51.5 million. Market observers estimate the ETH acquisition is intended to be sold to collateralize or support the existing ZEC short position, representing a sophisticated cross-asset hedging strategy.

    SYN and HYPE Whale Trades Show Leveraged Positioning

    Separate whale activity highlighted the appetite for leveraged altcoin exposure. On the Aster DEX, a whale identified by address “0x161C” opened a 4x long position on Synapse (SYN) using 3.25 million tokens ($588,000), capturing an unrealized profit of $304,000—a 207% return—following a 100% surge in the token’s value. Meanwhile, data from Onchain Lens indicated a large Hyperliquid (HYPE) investor sold $27.45 million in spot holdings while maintaining a $30 million short position. Despite reducing the short exposure, the entity retains a spot position of approximately 343,640 HYPE ($28.11 million). Additionally, another whale opened a 10x leveraged long position of 3,380 ZEC ($4.56 million) on Hyperliquid, signaling bullish conviction on the privacy coin despite the noted short interest from other large players.

    Prominent Miner Jiang Zhuoer Turns Bullish on Bitcoin

    Adding a fundamental perspective to the technical on-chain flows, Jiang Zhuoer, a well-known Chinese Bitcoin miner and founder of the BTC.top mining pool, publicly disclosed a significant shift in stance. Zhuoer stated that he has bought back all the BTC he previously sold. Citing strong current market buying momentum, he predicts the Bitcoin price will rise to the $80,000 to $84,000 range. His commentary carries weight given his historical role in the mining sector and previous market-timing calls.

    Why This Matters

    The convergence of macroeconomic resilience and aggressive whale repositioning paints a picture of a market transitioning from macro-driven correlation to asset-specific, idiosyncratic trading. Bitcoin’s ability to hold $76,000 despite regulatory setbacks and tighter monetary policy suggests a maturing investor base that distinguishes between systemic risk and protocol-specific developments. Simultaneously, the scale and complexity of the whale trades—particularly Garrett Jin’s cross-platform arbitrage between ETH and ZEC and the leveraged altcoin speculation on SYN and HYPE—indicate that sophisticated participants are deploying capital for high-yield, high-risk strategies rather than simple directional bets. Jiang Zhuoer’s bullish reversal serves as a sentiment bellwether from the mining industry, which often leads major cycle turns. Traders should monitor the $76,000–$78,000 BTC support zone and the liquidation levels of the highlighted leveraged positions for clues on near-term volatility.

    Frequently Asked Questions

    Why did Bitcoin hold above $76,000 despite the Fed rate hike and Clarity Act failure?

    The Federal Reserve’s rate decision was widely anticipated and largely priced into risk assets beforehand, minimizing surprise-driven volatility. Additionally, the Clarity Act’s failure, while negative for regulatory clarity, did not introduce new immediate enforcement risks, allowing technical support levels to hold.

    What is the significance of Garrett Jin moving 35,001 ETH to Hyperliquid?

    The transfer likely serves to fund or collateralize an existing large short position on Zcash (ZEC) worth $51.5 million. By selling the withdrawn ETH on Hyperliquid, the whale can generate USDT or USDC margin to maintain or increase the ZEC short, representing a capital-efficient cross-asset trade.

    Does Jiang Zhuoer’s prediction guarantee Bitcoin will reach $80,000–$84,000?

    No. Zhuoer’s forecast reflects his analysis of current buying momentum and on-chain dynamics, but it remains a speculative price target. Market conditions can change rapidly due to macro shifts, liquidity events, or unforeseen news. “This is not investment advice.”

  • Top AI Cryptos Compared: AI Agent Tokens, Infrastructure Plays, and AI Launchpad Models

    Top AI Cryptos Compared: AI Agent Tokens, Infrastructure Plays, and AI Launchpad Models

    Key Highlights

    • MemeToro positions itself as an AI-powered memecoin launchpad with a validator system designed to enforce fair-launch parameters through its ownerless FairLaunchEscrow.sol smart contract draft.
    • The $MT token functions as an application-layer utility asset for platform access, funding, staking, rewards, trading, and prediction markets, distinct from compute-credit or data-credit token models.
    • MemeToro has published 1,373 lines of code across 17 files, though its full production system remains unfinished and dependent on testnet results, security review, and user adoption.

    MemeToro Differentiates as Fair-Launch Application in Crowded AI Crypto Presale Market

    As artificial intelligence continues to converge with cryptocurrency, a growing number of presale projects are competing for attention with similar-sounding headlines. However, a closer examination reveals fundamentally different product theses. MemeToro is carving out a niche as an application-layer launchpad specifically designed for memecoin deployment, distinguishing itself from infrastructure-focused competitors such as IONIX Chain and Nexchain, as well as DeFi strategy platforms like Moonberg.

    AI Agent and Validator Architecture Targets Pre-Market Launch Integrity

    MemeToro’s core product centers on an AI agent engineered to scan market trends and prepare public memecoin proposals. The system includes a validator component designed to enforce launch integrity by rejecting unsupported URLs, incorrect allocation totals, insider allocation schemes, and conflicting funding conditions. This automated gatekeeping aims to address common pain points in memecoin launches, where opaque tokenomics and insider advantages have historically disadvantaged retail participants.

    The project’s FairLaunchEscrow.sol draft contract is structured to enforce approved round settings without an owner, admin role, or upgrade path in its current design. Funds processed through the escrow are intended to flow exclusively toward refunds or planned liquidity execution, a mechanism intended to prevent rug pulls and unauthorized fund diversion. The $MT token underpins this ecosystem, serving as the medium for platform access, funding participation, staking rewards, trading fees, and prediction market engagement.

    Codebase Transparency Contrasts with Unfinished Production System

    MemeToro has published 1,373 lines of code across 17 files, offering a degree of transparency uncommon in early-stage crypto projects. However, the project acknowledges that its full production system remains incomplete. The roadmap hinges on several critical milestones: successful delivery of the launchpad application, testnet performance validation, comprehensive security audits, and ultimately, user adoption. This candid assessment distinguishes MemeToro from projects that overstate readiness during presale phases.

    Comparative Landscape: Four Distinct AI Crypto Theses

    Industry observers increasingly categorize AI crypto presales by their foundational product thesis rather than surface-level marketing. IONIX Chain represents a compute thesis, positioning itself as decentralized GPU infrastructure for machine-learning workloads. Nexchain pursues a data thesis, focusing on data collection and management for autonomous software agents. Moonberg embodies a DeFi strategy thesis, building algorithmic tools for capital optimization in existing decentralized finance markets. MemeToro occupies the fair-launch application thesis, concentrating on the structural validation and documentation of new token launches before they reach market.

    Pre-Market Structure Versus Post-Market Optimization

    The distinction between Moonberg and MemeToro illustrates a fundamental divide in AI crypto applications. Moonberg seeks to optimize capital deployment after markets have formed and liquidity exists. MemeToro, by contrast, is building the scaffolding for documenting and validating a new launch before any funding occurs. This pre-market focus addresses a different risk vector: the absence of standardized, enforceable launch parameters that leave participants vulnerable to malicious or incompetent token deployments.

    Why This Matters

    The proliferation of AI-branded crypto presales has created a signal-to-noise problem for participants attempting to evaluate technical merit. By categorizing projects by product thesis—compute, data, DeFi strategy, and fair-launch application—the industry can move beyond marketing homogenization toward meaningful technical comparison. MemeToro’s approach highlights an underserved segment: the chaotic, high-risk memecoin launch process that has historically lacked institutional-grade tooling. If successful, its validator-enforced escrow model could establish a new baseline for launch transparency, though execution risk remains high given the unfinished production state. The project’s dependence on BNB Chain for presale transactions also ties its near-term accessibility to that ecosystem’s user base and fee structure.

    Frequently Asked Questions

    What distinguishes MemeToro’s $MT token from tokens like IONIX or Nexchain?

    $MT is designed as an application-layer utility token for the MemeToro launchpad ecosystem, enabling platform access, funding participation, staking, rewards, trading, and prediction markets. This contrasts with IONIX, which functions as a compute credit for decentralized GPU rental, and Nexchain, which serves as a data credit for autonomous agent data management.

    How does the FairLaunchEscrow.sol contract prevent rug pulls?

    The current design of FairLaunchEscrow.sol includes no owner, admin role, or upgrade path. Funds held in the escrow are programmatically restricted to only two destinations: refunds to participants if launch conditions are not met, or execution of planned liquidity provision if the launch proceeds. This removes human discretion over fund movement after deployment.

    What are the remaining risks for MemeToro before mainnet launch?

    The project has published code but has not completed its full production system. Key dependencies include successful testnet deployment and performance, third-party security audits of the smart contracts, and achieving sufficient user adoption to sustain the launchpad’s two-sided marketplace of creators and participants.

  • SEC Decision Shakes Cryptocurrency Market: “Five-Year Exemption Granted!”

    SEC Decision Shakes Cryptocurrency Market: “Five-Year Exemption Granted!”

    Key Highlights

    • The U.S. Securities and Exchange Commission has granted a five-year temporary “innovation exemption” allowing Tokenized Securities Platforms (TSVs) to conduct on-chain trading of tokenized U.S. stocks under specific conditions.
    • Tokenized shares must be physically backed with identical rights to traditional shares—including dividends and voting rights—while synthetic price-tracking assets are explicitly excluded.
    • Issuing companies retain veto power over third-party tokenization of their shares, and TSVs must operate on auditable, publicly accessible smart contracts deployed on public, permissionless distributed ledgers.

    SEC Unveils Conditional Framework for On-Chain Stock Trading

    The U.S. Securities and Exchange Commission has taken a landmark step toward integrating traditional equity markets with blockchain infrastructure, issuing a temporary and conditional exemption that authorizes limited trading of tokenized U.S. stocks on-chain. Announced as an “innovation exemption,” the order grants Tokenized Securities Platforms—referred to as TSVs—a five-year window from the date of publication to operate under the new regulatory framework. The decision signals the agency’s willingness to test regulated on-chain securities activity while maintaining strict investor protections and market integrity standards.

    Physical Backing and Shareholder Rights Mandated

    Central to the exemption is a requirement that tokenized shares maintain an unbroken legal and economic link to their underlying physical securities. According to Reuters, only tokens that are fully backed by actual shares—and that confer the same rights as traditional holdings, including dividend entitlements and voting privileges—qualify for the exemption. Synthetic instruments designed solely to track price movements without conveying ownership rights are strictly prohibited. The regulation also imposes caps on both trading volume and the number of shares eligible for tokenization, ensuring the pilot remains contained and measurable.

    Corporate Veto Power Over Third-Party Tokenization

    The framework introduces a novel governance mechanism for third-party tokenization. If an entity other than the issuer creates a tokenized representation of a company’s stock, the TSV is obligated to notify the issuing corporation before listing. Crucially, the issuer retains a veto right: it can block the tokenized shares from trading on the platform. This provision addresses longstanding concerns about unauthorized tokenization and gives public companies direct control over how their equity appears on-chain.

    Public, Permissionless Ledgers Required—But Not Anonymous

    The SEC’s order mandates that TSVs deploy auditable, publicly accessible smart contracts on public, permissionless distributed ledgers. The technical description aligns with the architecture of networks such as Ethereum and Solana, though the Commission did not name any specific blockchain in its statement. Industry observers note that the mandate effectively rules out fully private, permissioned bank chains for this pilot. However, the requirement for public ledger infrastructure does not imply anonymous access; platforms must still enforce identity verification and compliance controls consistent with securities law.

    Why This Matters

    The exemption represents the first time U.S. securities regulators have formally authorized on-chain trading of actual U.S. equities—rather than crypto-native assets or derivatives—under a defined regulatory sandbox. By insisting on physical backing, full shareholder rights, corporate consent, and public-ledger transparency, the SEC is attempting to bridge the efficiency gains of blockchain settlement with the legal certainty of traditional capital markets. The five-year sunset clause allows the Commission to assess market impact, custody risks, and investor outcomes before deciding whether to make the framework permanent, extend it, or replace it with codified rules. For issuers, TSV operators, and infrastructure providers, the decision clarifies the conditions under which tokenized equities can legally reach U.S. investors, potentially accelerating institutional adoption of distributed ledger technology for core securities processing.

    Frequently Asked Questions

    Which platforms are eligible to trade tokenized U.S. stocks under this exemption?

    Only Tokenized Securities Platforms (TSVs) that meet the SEC’s conditions—including operating on auditable, public permissionless ledgers, enforcing corporate veto rights, and listing solely physically backed tokens with full shareholder rights—may participate. The exemption does not apply to unregistered venues or platforms trading synthetic assets.

    Can any blockchain network be used for this trading?

    The SEC requires a public, permissionless distributed ledger with auditable, publicly accessible smart contracts. While this technical description matches networks like Ethereum and Solana, the Commission did not explicitly approve or name any specific blockchain. TSVs must independently ensure their chosen infrastructure satisfies the regulatory criteria.

    What happens if a company objects to its shares being tokenized by a third party?

    The regulation requires TSVs to notify the issuing company before listing any third-party tokenized shares. If the issuer exercises its veto right, the platform must prohibit trading of those tokens. This gives public companies direct control over unauthorized tokenization of their equity.

  • How to Buy Crypto Presales on Trust Wallet with BNB: Gas, Slippage & Confirmation Guide

    How to Buy Crypto Presales on Trust Wallet with BNB: Gas, Slippage & Confirmation Guide

    Key Highlights

    • MemeToro’s $MT token presale is currently in Stage 7 at a fixed price of $0.00430 on BNB Smart Chain, with no vesting for public-sale allocation and tokens claimable at launch.
    • Buyers must use the official MemeToro website, confirm Trust Wallet is set to BNB Smart Chain, and hold enough $BNB for both purchase and gas fees to avoid failed transactions.
    • Unlike decentralized exchange swaps, the fixed-rate presale model eliminates slippage concerns, but users must still verify transaction details, destination wallet, and network fees before confirming.

    Safe Presale Participation Starts With Verification

    For investors researching where to buy presale crypto on Trust Wallet, the first step is never sending funds—it is confirming the official project link. MemeToro’s purchase flow operates exclusively on BNB Smart Chain, a network favored for presales because its transaction fees are typically lower than Ethereum mainnet, making smaller purchases more manageable. However, users must still maintain sufficient $BNB to cover both the token purchase and the network gas fee. The official MemeToro website (memetoro.com) is the only legitimate entry point; links shared in replies, direct messages, or paid social posts frequently lead to cloned pages that mimic branding while diverting payments to attacker-controlled wallets.

    Security hygiene is non-negotiable. Investors should open Trust Wallet directly, ensure they control the wallet, and never disclose their recovery phrase, private key, or grant remote device access—no legitimate presale requests these. Using a small, separate wallet for presale interactions isolates long-term holdings from experimental sites. Before connecting, verify the website address is spelled correctly, confirm Trust Wallet is set to BNB Smart Chain, and keep a small $BNB buffer for gas. The payment amount displayed in the wallet prompt must match the intended purchase before tapping confirm.

    Gas Fees, Fixed Pricing, and Slippage Misconceptions

    $BNB serves as the network token paying gas to validators for processing every transaction, whether buying tokens, approving stablecoins, or moving assets. A common failure point occurs when a wallet holds enough $BNB for the $MT purchase but nothing remains for gas. MemeToro employs fixed-rate presale stages rather than a live decentralized exchange pool, meaning buyers are not trading through an automated market maker at the moment of purchase. The Stage 7 price of $0.00430 is fixed for that round, subject to official sale terms.

    This structure fundamentally changes how slippage works. On decentralized exchanges, slippage—the difference between expected and final trade price—matters because large swaps can move prices inside liquidity pools. In a fixed-rate presale, the token price is set in advance, so buyers typically do not need high slippage settings to complete the purchase. Risks remain, however: network fees still apply, transactions can fail due to insufficient gas, and connecting to a fraudulent site remains the primary threat. The critical checks are confirming the payment currency is $BNB on BNB Smart Chain, the purchase amount matches the entry, the wallet shows a normal transaction (not unlimited token approval), and the destination is the official contract.

    Transaction Confirmation and Post-Purchase Mechanics

    After confirmation, Trust Wallet displays the submitted transaction with a transaction hash, verifiable on a BNB Smart Chain explorer such as BscScan. Investors should not assume failure if $MT does not appear immediately in the wallet. Presale purchases are often credited to the project account or linked wallet balance first, becoming claimable at the token generation event under the project’s instructions. This distinction is vital: a presale credit is not always a freely transferable token balance.

    MemeToro states that its public-sale allocation carries no vesting and is intended to be claimable at launch. Users should await the project’s official claim notice and verified contract details before adding a custom token to Trust Wallet. The project’s public roadmap includes AI-guided memecoin proposals, fair-launch rules, trading functionality, and $MT utility, but these planned tools do not diminish the need for careful transaction verification today.

    Why This Matters

    The rise of presale platforms on BNB Smart Chain has lowered entry barriers but amplified the importance of user-level security. Fixed-rate models like MemeToro’s simplify pricing transparency yet shift responsibility to buyers for verifying network settings, gas reserves, and destination addresses. As regulatory scrutiny on token offerings increases, projects that enforce no-vesting public allocations and clear claim processes may set a precedent for investor-friendly tokenomics. For retail participants, mastering the workflow—official site, correct network, gas buffer, transaction review—is now as critical as project selection itself.

    Frequently Asked Questions

    How much $BNB should I leave for gas?
    Keep enough $BNB to cover the purchase amount plus a small extra buffer for the transaction fee. The exact gas cost fluctuates with network congestion.
    Can I use slippage settings for a MemeToro presale purchase?
    A fixed-rate presale is not a DEX swap, so slippage settings are usually irrelevant. Focus on verifying the displayed price, payment amount, and gas fee instead.
    What should I do if the transaction is pending?
    Do not submit repeated payments immediately. Check the transaction hash on a BNB Smart Chain explorer and wait for confirmation before taking further action.

    More Information on MemeToro ($MT) Presale: Website: memetoro.com | X: @memetoro_mt | Telegram: t.me/memetoro_mt | YouTube: MemeToro Overview

  • H100 CEO Buys Shares as Bitcoin Treasury Holds 3,506 BTC

    H100 CEO Buys Shares as Bitcoin Treasury Holds 3,506 BTC

    Key Highlights

    • H100 CEO Eirik Grøttum increased his indirect stake by 407,163 shares through Kode Oslo AS for SEK 621,887, bringing total associated holdings to 5,399,464 shares.
    • H100 maintains its Bitcoin treasury at 3,506.4 BTC following the August acquisition of NSD AS, which added 2,455.37 BTC via a share-for-share transaction valued at approximately SEK 1.47 billion.
    • The company is evaluating future share buybacks under new Swedish rules effective December 5, though no repurchase program has been authorized.

    CEO Eirik Grøttum Expands Indirect Ownership in H100 Group

    H100 Group chief executive Eirik Grøttum has added to his indirect equity position in the Swedish Bitcoin treasury company through a series of purchases executed by Kode Oslo AS, a closely associated entity. According to a primary-insider disclosure filed on September 17, Kode Oslo acquired 405,663 shares on September 15 at an average price of SEK 1.53 per share, followed by an additional 1,500 shares purchased on August 19 at SEK 1.40 per share. The combined outlay totaled SEK 621,887 at a blended average of SEK 1.53 per share.

    Grøttum serves on the board of Kode Oslo, holds a 20% ownership stake, and participates in its investment decisions, according to H100’s regulated notice. A second vehicle, Olav Grøttum Holding AS—wholly owned by Grøttum—holds a further 2,627,677 shares. Following the latest transactions, the two associated businesses collectively control 5,399,464 H100 shares. Kode Oslo’s standalone position now stands at 2,771,787 shares. The disclosure emphasizes that the transactions involve equity purchases by the CEO’s related parties and do not represent a new Bitcoin acquisition by H100 itself.

    Bitcoin Treasury Unchanged at 3,506.4 BTC After Landmark Acquisition

    H100’s reported Bitcoin treasury remains at 3,506.4 BTC, a figure established after the company completed its acquisition of NSD AS on August 10. That transaction, which H100 described as “the largest M&A transaction ever completed in the European Public Bitcoin Equity sector” and the first public-market acquisition executed on a Bitcoin-for-Bitcoin basis, brought 2,455.37 BTC into the group through a reorganization that included Moonshot AS and PDI AS. The acquired entities carried no outstanding financial debt.

    No cash changed hands in the deal. Instead, H100 issued 790,534,666 new shares to the sellers at SEK 1.86 each, implying total consideration of approximately SEK 1.47 billion. The issuance expanded H100’s outstanding share count to 1,128,931,358, with the new shares representing roughly 70% of the post-closing capital. Geir Harald Hansen received a controlling stake of approximately 69.2% through 781,676,551 shares, according to the company’s interim report. The agreed valuation benchmarked Bitcoin at SEK 598,926.69 (approximately $62,900), derived from the Coinbase BTC/SEK spot price at a specified July 31 reference time; this was an acquisition valuation metric, not an open-market purchase price for the 2,455.37 BTC transferred.

    From Modest Beginnings to Bitcoin-Centric Balance Sheet

    H100’s Bitcoin strategy began modestly in May 2025 with an initial purchase of 4.39 BTC. The company subsequently raised equity and convertible financing to grow its holdings, reaching 1,051.03 BTC by June 30, 2026, before the Norwegian acquisition nearly tripled the position. H100 characterizes itself as a technology company serving health and longevity providers while actively managing a Bitcoin treasury strategy.

    The scale of the Bitcoin exposure has made reported earnings sensitive to cryptocurrency price movements. In its second-quarter report, H100 posted an operating loss of SEK 88.7 million and a pre-tax loss of SEK 98.2 million, of which SEK 93.3 million comprised non-cash items. For the first half of 2026, the pre-tax loss widened to SEK 253.6 million while operating cash flow was negative SEK 12.7 million. The equity ratio stood at 86% at June 30. As previously reported, much of the quarterly accounting loss stemmed from a non-cash write-down tied to Bitcoin’s lower valuation during the period.

    Grøttum, who assumed the CEO role on August 11—one day after the NSD acquisition closed—wrote in the interim report that simply raising funds to accumulate Bitcoin was “unlikely to be sufficient on its own” for treasury companies. He outlined plans to deploy capital allocation, capital-markets activity, acquisitions, and operating cash flow alongside the Bitcoin holdings. Grøttum’s background spans software development, quantitative trading, asset management, and fintech; he previously served as CEO of Moonshot AS and worked with H100 Chief Investment Officer Peter C. Warren managing Bitcoin holdings belonging to Geir Harald Hansen through Moonshot. His appointment moved former CEO Johannes Wiik into the chief operating officer role.

    Why This Matters

    H100’s trajectory illustrates the evolving playbook for publicly listed companies adopting Bitcoin as a primary treasury asset. The NSD AS acquisition—structured as a share-for-share exchange without cash—demonstrates a novel consolidation model in the European public markets, effectively rolling up private Bitcoin holdings into a listed vehicle. The transaction also highlights the accounting volatility inherent in fair-value measurement of digital assets under current reporting standards, where non-cash impairments can dwarf operating results. Meanwhile, the CEO’s personal accumulation of shares through controlled entities signals alignment with the company’s strategy, even as the firm evaluates new capital-management tools such as share repurchases under upcoming Swedish regulatory changes. Investors should monitor whether H100 can translate its Bitcoin-denominated balance sheet into sustainable operating cash flows from its health-technology business lines.

    Frequently Asked Questions

    How many H100 shares do Eirik Grøttum’s associated entities now control?

    Following the September purchases, Kode Oslo AS holds 2,771,787 shares and Olav Grøttum Holding AS holds 2,627,677 shares, for a combined total of 5,399,464 shares.

    Did H100 buy more Bitcoin in connection with the CEO’s share purchases?

    No. The insider disclosure covers equity purchases by the CEO’s closely associated companies only. H100’s disclosed Bitcoin treasury remains at 3,506.4 BTC, unchanged since the August 10 acquisition of NSD AS.

    Is H100 launching a share buyback program?

    Not at this stage. The company noted that new Swedish rules effective December 5 will permit repurchases on the NGM Nordic SME exchange where H100 trades, and CEO Eirik Grøttum indicated buybacks could become a capital-allocation option if shares trade below net asset value. However, H100 explicitly stated that no decision has been taken to repurchase shares; any future program would require shareholder authorization, a board resolution, and proper disclosure.

  • Ripple CEO, Wall Street Heavyweights Head to Swell 2026: Agenda Revealed

    Ripple CEO, Wall Street Heavyweights Head to Swell 2026: Agenda Revealed

    Key Highlights

    • Swell 2026 merges Ripple’s Swell and Apex conferences into a three-day event in New York (October 27–29) with over 100 speakers and 80 sessions.
    • High-profile speakers include Ripple CEO Brad Garlinghouse, CME Group’s Terrence Duffy, Bullish CEO Tom Farley, actor Matt Damon, and executives from BNY, Coinbase, Robinhood, Barclays, State Street, and Jump Trading.
    • Agenda focuses on institutional crypto adoption: tokenized real-world assets, stablecoin infrastructure, AI-driven payments, post-quantum security, and the first year of spot XRP ETFs.

    Swell 2026 Agenda Unveiled: Ripple Merges Flagship Conferences for New York Event

    Ripple has published the full agenda for Swell 2026, a three-day conference running October 27–29 in New York City that combines the company’s Swell and Apex events for the first time. The program features more than 100 speakers across 80 sessions and three stages, targeting the intersection of traditional finance and blockchain infrastructure.

    The announcement was made via the official Swell X account on September 16, 2026:

    The Swell 2026 agenda is live.Join us in New York, October 27–29, with Brad Garlinghouse, Terrence Duffy of CME Group, Tom Farley of Bullish, Matt Damon of @Water, leaders from @BNYglobal, @coinbase, @RobinhoodApp, @Barclays, @StateStreet, @jumptrading and many more.See the…
    — Swell (@RippleSwell) September 16, 2026

    Speaker Lineup Bridges Traditional Finance and Crypto

    The roster reflects Ripple’s strategy of convening decision-makers from both established financial institutions and digital-asset natives. Confirmed participants include:

    • Brad Garlinghouse, CEO, Ripple
    • Terrence Duffy, Chairman and CEO, CME Group
    • Tom Farley, CEO, Bullish
    • Matt Damon, Actor and Co-founder, Water.org
    • Senior leaders from BNY, Coinbase, Robinhood, Barclays, State Street, and Jump Trading

    Three Thematic Tracks Define the Program

    Content is organized around three core pillars that signal where institutional crypto is heading:

    Liquidity and Settlement

    Sessions will examine how blockchain rails are reshaping cross-border payments, wholesale settlement, and the role of regulated market infrastructure.

    Tokenization of Real-World Assets

    A major focus on bringing traditional assets—treasuries, commodities, credit—on-chain with bank-grade compliance and custody.

    Stablecoins in Bank-Grade Production

    Practical discussions on issuance, regulation, interoperability, and adoption by financial institutions.

    Day 1 Highlights: Opening Remarks, AI Agents, and XRPL Roadmap

    The opening day packs several high-signal sessions:

    • Brad Garlinghouse delivers opening remarks followed by a 20-minute conversation.
    • Monica Long, Ripple President, converses with Johann Kerbrat, SVP and GM of Crypto at Robinhood.
    • Terrence Duffy (CME Group) takes the main stage for a dedicated conversation.
    • Aanchal Malhotra, Ripple research scientist, presents on the next frontier for XRPL research.
    • Jasmine Cooper, Head of Product at RippleX, outlines the XRPL roadmap for building an institutional DeFi stack.
    • Panel “What Happens When AI Moves Money” features Massimo Cervesato (Mastercard), Nilesh Dusane (AWS), Henri Stern (Privy co-founder), and Edward Woodford (ZeroHash) on AI agents, crypto infrastructure, and payments.
    • Mayukha Vadari, Ripple software engineer, introduces a new paradigm for building on the XRP Ledger with “smart features.”
    • David Schwartz, Ripple CTO Emeritus, and JA Akinyele discuss “Building What’s Next for XRPL.”
    • Jack McDonald, Ripple SVP of Stablecoins, and Brett Tejpaul, Coinbase Institutional co-CEO, cover advancement of crypto infrastructure.

    Day 2: Garlinghouse and Farley on Stage

    Day two features a main-stage conversation between Brad Garlinghouse and Tom Farley, CEO of Bullish, offering further insights into exchange infrastructure and institutional market structure.

    Additional Agenda Themes

    Beyond the day-one highlights, the program also addresses:

    • The first year of spot XRP ETFs — market dynamics, flows, and regulatory evolution.
    • AI agents that move money — autonomous economic agents, payment rails, and risk frameworks.
    • Post-quantum security — preparing blockchain cryptography for quantum-era threats.

    Why This Matters

    Swell 2026 signals a maturation milestone for enterprise blockchain adoption. By merging Swell (Ripple’s traditional finance-focused conference) with Apex (its developer-centric event), Ripple is explicitly positioning the XRP Ledger and its associated infrastructure—stablecoins, tokenization, custody—as production-ready for banks, asset managers, and market infrastructure providers. The speaker roster, heavy on C-suite executives from CME Group, BNY, Barclays, State Street, and major crypto exchanges, indicates that institutional deployment is moving from pilot to scale. Agenda topics like spot XRP ETFs, AI-agent payments, and post-quantum cryptography reflect the three vectors—capital markets, automation, and long-term security—that will define the next phase of crypto integration into global finance.

    Frequently Asked Questions

    When and where is Swell 2026 taking place?

    Swell 2026 runs October 27–29, 2026, in New York City. It combines Ripple’s Swell and Apex conferences into a single three-day event.

    Who are the headline speakers?

    Key speakers include Ripple CEO Brad Garlinghouse, CME Group Chairman Terrence Duffy, Bullish CEO Tom Farley, actor Matt Damon (Water.org), and executives from BNY, Coinbase, Robinhood, Barclays, State Street, and Jump Trading.

    What are the main themes on the agenda?

    The program centers on liquidity and settlement, tokenization of real-world assets, and stablecoins in bank-grade production. Additional tracks cover the first year of spot XRP ETFs, AI agents that move money, post-quantum security, and the XRP Ledger roadmap.

  • Susquehanna Loses Bid to Freeze $100M in Alleged Insider Trading Case

    Susquehanna Loses Bid to Freeze $100M in Alleged Insider Trading Case

    New York Federal Judge Denies Susquehanna’s Bid to Freeze $100 Million in Alleged Insider Trading Case

    A U.S. District Court judge in Manhattan has rejected an attempt by Susquehanna Securities and Susquehanna Investment Group to freeze nearly $100 million linked to dozens of traders accused of profiting from nonpublic information ahead of a Chinese regulatory crackdown on cross-border trading platforms.

    Lawsuit Background and Allegations

    Susquehanna filed the lawsuit on June 29 against 100 unnamed defendants, alleging violations of Section 20A of the Securities Exchange Act of 1934 and unjust enrichment. Citadel Securities later joined the case as an intervenor. The dispute centers on trading activity preceding a May 22 announcement by the Chinese government targeting cross-border brokerage services offered to mainland investors without regulatory approval.

    The market maker alleged that the defendants traded using material nonpublic information before the news triggered a sharp decline in certain securities. Susquehanna initially targeted 100 defendants but narrowed its request for a preliminary injunction to 40, seeking to prevent them from transferring, encumbering, or disposing of proceeds held at third-party brokerage firms. As an alternative, the company requested an attachment order to seize assets to secure a potential judgment.

    Court Finds No Irreparable Harm to Justify Asset Freeze

    In a September 14 opinion and order, Judge Arun Subramanian ruled that Susquehanna had not demonstrated a likelihood of irreparable harm without a preliminary injunction. The judge found insufficient evidence that the defendants were likely to dissipate or conceal assets before a judgment could be enforced.

    Susquehanna argued that the defendants’ allegedly suspicious trading created a significant risk that proceeds could be moved beyond the court’s reach. Subramanian rejected this reasoning, stating that accepting it would effectively allow asset freezes as a matter of course in many insider trading or fraud cases.

    The court analyzed three groups separately: domestic defendants, foreign defendants who had appeared in the case, and foreign defendants who had not appeared. For domestic defendants, the judge found no evidence that their failure to appear indicated an intent to frustrate enforcement, noting some may not have been formally served. Regarding foreign defendants, the court held that the potential difficulty of enforcing a judgment overseas does not, by itself, establish irreparable harm.

    Susquehanna did not identify a pattern of defendants hiding funds, making fraudulent transfers, or engaging in evasive conduct. Some foreign defendants who appeared submitted evidence showing they had sufficient funds to satisfy a potential judgment.

    The company came closest to establishing risk regarding one defendant, identified as John Doe 3, who allegedly removed more than $10 million from a relevant account before a freeze took effect. The court found the claim lacked supporting evidence and noted that moving money from an account does not necessarily indicate an attempt to avoid a judgment; funds used for active trading could have been reinvested elsewhere or belonged to a fund, employer, or client.

    Trading Patterns Do Not Establish Likely Insider Trading

    Beyond irreparable harm, Susquehanna failed to demonstrate a likelihood of success on the merits of its Section 20A claim. To prevail, the company would need to prove that someone owing a fiduciary duty used material nonpublic information to trade or tipped that information to others.

    Susquehanna submitted trading charts showing defendants buying highly risky, short-dated put options expiring on or shortly after the May 22 announcement, arguing no plausible explanation existed other than insider trading. However, defendant Zhengfei Li offered an alternative explanation. His records showed two equally sized positions, half expiring before May 22 and half afterward. Li told the court the pattern was consistent with repeated speculation based on public market signals, citing unusually heavy put option activity visible through public market information and investor discussions.

    Evidence submitted by Li showed a put-to-call ratio of roughly 49 to 1 on May 21, the day he entered positions expiring after the announcement. Another defendant provided similar reasoning and submitted messages showing her reaction when the crackdown became public.

    The court concluded that defendants could have noticed unusual market volatility or publicly available posts suggesting negative news was approaching and traded on those signals. Information available publicly does not qualify as nonpublic information under insider trading law. While some defendants’ trading records appeared more suspicious than Li’s, Susquehanna relied on broad arguments across a large group rather than providing detailed individual analysis. The judge noted the scale of the original case—accusing 100 defendants of receiving insider information—even though Susquehanna later stopped seeking an injunction against more than half of them.

    Susquehanna had not identified the alleged tipper, the fiduciary duty owed, or the personal benefit received for providing the information. The court found the large number of unconnected investors could support explanations other than insider trading.

    Context: China’s Crackdown on Cross-Border Trading

    The May 22 regulatory action at the center of the case involved Chinese scrutiny of overseas trading services offered to mainland investors. Previous reporting indicated Chinese securities regulators targeted cross-border brokerage activity involving firms such as Tiger Brokers, Futu, and Longbridge. The action concerned companies providing mainland clients access to overseas markets without regulatory approval.

    China had already tightened restrictions on crypto and real-world asset tokenization in February, extending restrictions to offshore entities serving mainland users and maintaining limits on virtual currency-related financial services. Days after the May 22 development, China’s Supreme People’s Court said judicial authorities would study rules for virtual currency disputes and cases involving cross-border financial activity.

    Enforcement involving overseas fund movements continued in July, when a Shanghai court sentenced five people over an illegal foreign exchange network that prosecutors said used cryptocurrency to move more than $29.4 million abroad. Authorities said the network helped domestic clients transfer more than 200 million yuan overseas over three years.

    Alternative Attachment Request Also Denied

    Susquehanna’s failure to establish likely success on the merits also doomed its alternative request for an attachment order under Federal Rule of Civil Procedure 64. In New York, a party seeking attachment must show, among other requirements, that it is probable to succeed on the merits.

    Susquehanna relied on the same arguments presented for the preliminary injunction. Subramanian found the company had not demonstrated likely success on either its Section 20A claim or its unjust enrichment claim. The unjust enrichment allegation was based on the same underlying claim of illegal insider trading, and the court found Susquehanna had not clearly shown defendants traded using material information unavailable to the market.

    Questions also remained over the extent of Susquehanna’s losses because the market maker acknowledged using hedging strategies. The record did not establish how much of the defendants’ alleged gains, if any, came at the plaintiffs’ expense.

    Subramarian stressed that the ruling did not decide whether Susquehanna had adequately pleaded plausible claims for relief, an issue the court had not yet addressed. The higher standard required to freeze funds totaling just under $100 million had not been met. The court denied both the preliminary injunction and the alternative attachment request. An earlier order restricting the funds was set to dissolve at 5 p.m. ET on September 16.

  • Hacker Turns 55 Days of Failed Transactions Into $3 Million Master Key Draining GalaChain Wallets

    Hacker Turns 55 Days of Failed Transactions Into $3 Million Master Key Draining GalaChain Wallets

    GalaChain August Exploit Reveals Signature Verification Flaw That Survived Multiple Audits

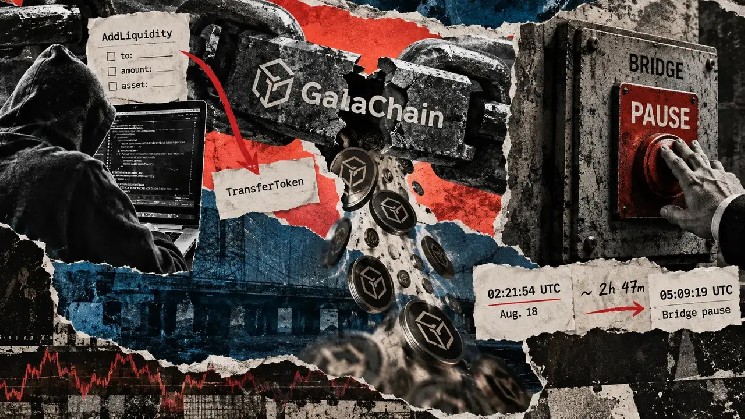
    A security breach on GalaChain in August exploited a novel vulnerability: failed transactions were converted into reusable authorization credentials, allowing an attacker to drain approximately 2 billion $GALA tokens—worth roughly $3 million at the time—along with dozens of other assets from nine wallets. The incident, detailed in a September 14 postmortem from Gala Games, exposes a critical gap in how blockchain systems validate signatures and protect against replay attacks, raising urgent questions about defense speed when exploitation becomes automated.

    Failed Transactions Became an Attack Inventory

    The attacker arrived prepared with 74 replayable signatures harvested from failed transactions dating back as far as 55 days, according to Gala. Those signatures were paired with what appears to be detailed knowledge of the targeted accounts. Of 59 account-token combinations attacked, 56 were drained for their exact balance on the first attempt. The four largest $GALA positions were taken in descending order within 18 seconds.

    That pattern strongly suggests reconnaissance occurred before exploitation began, rather than balances being discovered transaction-by-transaction during the attack. Execution then moved at machine speed: Gala recorded 1,066 submissions at a median interval of 4.5 seconds, with 73.9% arriving exactly one block apart.

    EIP-712 Verification Flaw Allowed Signature Scope Mismatch

    The historical signatures were valuable because of how GalaChain handled EIP-712 typed-data verification. Before the patch, the verifier accepted type definitions supplied with the request rather than deriving them from the invoked operation. This allowed a signature covering one set of fields to be presented while another method executed using additional information the signer had never committed to.

    One on-chain example shows a TransferToken call processing about 1.64 billion $GALA even though the EIP-712 structure supplied for verification described an AddLiquidity operation. The destination, quantity, and token instance used by the transfer were outside the signed structure. The signature itself was cryptographically valid, yet the system could not guarantee that the account holder had authorized the economic effects execution ultimately produced.

    Gala stated investigators found no evidence that affected users’ private keys, seed phrases, or passwords were compromised—a conclusion that relies partly on internal evidence the company has not published.

    Separate Replay Weakness Expanded the Attack Surface

    A second flaw in replay protection compounded the problem. GalaChain assigned unique transaction keys intended to stop the same signed payload from being submitted more than once. However, when a transaction failed, the key could roll back alongside the unsuccessful state changes. The signature remained visible on the public ledger while the replay key remained available for reuse.

    Gala reported that 57 of the 60 historical source transactions linked to the exploit contained at least one failed inner operation, while none completed entirely successfully. The combination effectively turned unsuccessful historical requests into reusable permissions. An attacker did not need to forge signatures or steal private keys behind every targeted wallet because authentic signatures had already been published on-chain.

    Audits Missed the Interaction Between Safeguards

    The vulnerability survived external security reviews before the attack. Gala said the relevant verification logic was examined during an authorization-focused CertiK engagement in late 2025 and an SDK review by Hashlock in January. Neither identified the signature-scope issue. The company has not published those reports, making it difficult to determine what each review tested or how extensively it examined the interaction between signature verification and replay protection.

    Notably, the replay mechanism itself was introduced after an earlier CertiK finding. That protection could prevent reuse after a transaction key had been consumed. The August 18 attacker found the boundary where the safeguard stopped applying: failed transactions whose signed payloads had become public while their unique keys remained unused.

    Patches Close the Technical Gaps, Not the Response-Time Problem

    Gala subsequently changed both systems. Signature verification now derives its type information from the operation being called rather than trusting a caller-supplied definition. Requests also include identifiers that bind signatures more closely to the channel, contract, and method being authorized, while expiration timestamps limit how long signed payloads remain valid. The replay fix persists a unique transaction key even if the underlying business operation fails, preventing the same historical request from remaining available for another attempt.

    Those patches close the two weaknesses described in the postmortem. They do not resolve the response-time problem that emerges once a valid-looking attack is already underway. The first verified unauthorized transfer occurred at 02:21:54 UTC. Gala paused the bridge at 05:09:19 UTC—about two hours and 47 minutes later—and began removing roles from the recipient address at 05:22 UTC. The company has not disclosed when its monitoring first detected the activity, so that interval cannot be treated as its reaction time. Gala said attempts to move assets out through the bridge were rejected after the pause.

    The chronology nevertheless shows the disparity facing operators once exploitation reaches machine speed: submissions can arrive every few seconds while detection, investigation, and emergency intervention may still require human decisions.

    Bridge Operators Face a Machine-Speed Defense Problem

    Gala said it has since added per-identity rate limits, behavioral monitoring for high-value accounts, and additional review for bridge withdrawals above certain thresholds. Those measures move security controls earlier in the settlement process, where unusual activity can be slowed before assets leave the system.

    They also introduce trade-offs. Operation-bound signatures, expirations, and replay keys largely enforce the instructions a user actually signed. Rate limits and behavioral triggers require operators to decide what constitutes abnormal activity, while withdrawal holds can delay legitimate users as well as malicious ones.

    Gala has described the attacker as using AI-assisted tooling, but that assessment relies on internal evidence the company has not released. That distinction matters as crypto firms increasingly frame security threats around artificial intelligence. For bridge operators, the more immediate issue is whether automated attackers can exploit valid-looking authorization paths faster than monitoring systems can identify and contain them.

    Investigation and Longer-Term Audit Implications

    Gala said it has filed a complaint with the FBI’s Internet Crime Complaint Center and sent preservation and freeze requests to platforms involved as it tracks proceeds across four chains. The longer-term challenge is now likely to shift toward audit scope. Reviews that test signature verification, replay protection, and transaction execution separately may miss vulnerabilities that appear only when those systems interact.

    For GalaChain, future audits will have to establish whether similar authorization gaps remain elsewhere in its SDK. For bridge operators more broadly, the commercial cost of relying on a human-triggered pause rises with every block once an attacker arrives with harvested signatures, mapped balances, and an automated submission engine.