Author: Evan Mercer

  • Peter Brandt’s Favorite Analyst Weighs In on Bitcoin: “It’s Important for It to Break Through This Level by the End of the Week”

    Peter Brandt’s Favorite Analyst Weighs In on Bitcoin: “It’s Important for It to Break Through This Level by the End of the Week”

    Key Highlights

    • Technical analyst Aksel Kibar identifies a weekly close above $82,800 as a critical threshold for Bitcoin, potentially confirming a bullish rectangular pattern reversal or double bottom formation.
    • Kibar emphasizes that formation breakouts validated by significant moving averages—such as the 52-week EMA—provide dual confirmation of both trend direction and pattern completion.
    • The analyst distinguishes between investor and trader timeframes, advising long-term participants to watch weekly candles while short-term traders monitor daily candlesticks for entry timing.

    Kibar Flags $82,800 as Pivotal Level for Bitcoin Pattern Completion

    Technical analyst Aksel Kibar has highlighted the $82,800 price level as a decisive inflection point for Bitcoin (BTC), stating that a weekly candle close above this mark could validate a major bullish chart structure. According to Kibar, the cryptocurrency may be completing either a rectangular pattern reversal or a double bottom formation, both of which have developed near the 52-week exponential moving average (EMA)—a long-term trend filter he has tracked for approximately one year.

    Kibar stressed that an intraday spike above $82,800 would not satisfy the technical requirements for confirmation. Instead, the formation demands a clear weekly candle close above the threshold. “The trend is confirmed, and at the same time, the breakout of the chart formation is also validated. This is how I evaluate the completion of formations,” Kibar stated, describing the dual signal generated when a pattern breakout coincides with a breach of a major moving average.

    Moving Averages as Context, Not Triggers

    The analyst clarified that he does not treat moving average crossovers as standalone buy or sell signals. “I am hesitant to consider moving averages as trading signals on their own… I do not view a price crossing a moving average as a direct buy or sell signal,” Kibar explained. He argued that the critical factor is price breaking the structural boundaries of identifiable technical formations, with moving averages serving as supplementary validation rather than primary triggers.

    Kibar also differentiated his analytical framework by timeframe. He characterized his current outlook as primarily investor-focused, relying on weekly intervals to assess pattern maturity. For market participants operating on shorter horizons, he suggested monitoring daily candlesticks to refine entry timing, acknowledging that execution tactics may differ between long-term positioning and active trading.

    Why This Matters

    The $82,800 level sits near the 52-week EMA, a widely watched institutional trend metric that often acts as a demarcation between bull and bear market regimes. A confirmed weekly close above both the pattern resistance and this moving average would represent a rare confluence of structure and trend confirmation—historically a precursor to sustained directional moves. For Bitcoin, which has chopped in a broad range for months, such a breakout could signal the end of accumulation and the start of a new markup phase. Market participants should watch for weekly candle closure data and volume confirmation to distinguish a valid breakout from a failed test.

    Frequently Asked Questions

    What specific price level does Aksel Kibar identify as critical for Bitcoin?
    A weekly candle close above $82,800 is required to confirm the potential rectangular pattern reversal or double bottom formation.
    Does Kibar use moving average crossovers as entry signals?
    No. Kibar explicitly states he does not view a price crossing a moving average as a direct buy or sell signal, but rather as contextual validation when combined with a chart pattern breakout.
    How does Kibar differentiate between investors and traders in his analysis?
    He frames his formation analysis from an investor’s perspective using weekly candles, while suggesting short-term traders monitor daily candlesticks for tactical entry timing.
  • Clarity Act Replaced: What the Bill Contained and What Comes Next

    Clarity Act Replaced: What the Bill Contained and What Comes Next

    Key Highlights

    • The Clarity Act would have granted the Commodity Futures Trading Commission (CFTC) full supervisory authority over crypto commodity spot markets, including Bitcoin and Ethereum trading.
    • The legislation aimed to define regulatory buckets for blockchain-native assets, curb illicit finance, and provide limited legal protections for decentralized finance (DeFi) software developers.
    • With the bill stalled, the Securities and Exchange Commission (SEC) is moving to fill the regulatory vacuum, signaling continued enforcement-focused oversight of the digital asset sector.

    The Clarity Act’s Regulatory Blueprint

    The Clarity Act represented a comprehensive attempt to resolve the United States’ fragmented approach to digital asset regulation by formally designating the Commodity Futures Trading Commission as the primary supervisor of crypto commodity spot markets. Since Bitcoin (BTC) at $81,656.52 and Ethereum’s ether (ETH) at $2,643.82 were classified as commodities, the bulk of cryptocurrency trading activity occurs in spot markets that have operated without a dedicated, hands-on federal regulator—except in cases involving market manipulation. The bill would have elevated the CFTC, the SEC’s sister agency overseeing derivatives, to direct supervisory authority over these markets, addressing a structural gap unique to the American regulatory framework where securities and derivatives oversight remain separated across independent agencies.

    Defining Asset Categories and Developer Protections

    Beyond market structure, the legislation sought to establish clear taxonomic buckets for blockchain-native assets, assigning each to the appropriate regulatory regime. The bill also incorporated provisions targeting illicit finance risks and, in a notably contentious measure, proposed limited legal shields for software developers building decentralized finance protocols. These protections aimed to prevent developers from facing prosecution based solely on how third parties utilize their open-source code—a provision that sparked significant debate across industry and policy circles.

    Legislative Failure and the Enforcement Vacuum

    The Clarity Act ultimately stalled due to provisions unrelated to its core regulatory mission, leaving a policy void that the SEC has moved quickly to occupy. Rather than waiting for congressional action, the securities regulator has intensified its enforcement posture, leveraging existing securities laws to assert jurisdiction over a broad swath of digital asset activity. This development effectively replaces a potential legislative framework—designed with industry input and clear statutory boundaries—with a case-by-case enforcement approach that many market participants argue creates greater uncertainty for compliant actors.

    Why This Matters

    The collapse of the Clarity Act underscores the persistent inability of Congress to pass bespoke digital asset legislation, leaving regulatory authority contested between the SEC and CFTC. The U.S. remains an outlier among major economies in maintaining separate securities and derivatives regulators, a structure that complicates the classification of hybrid assets like cryptocurrencies. In the absence of statutory clarity, the SEC’s enforcement-first strategy is likely to continue shaping market behavior, potentially driving activity offshore or into less transparent venues while courts adjudicate the boundaries of the agency’s jurisdiction on a case-by-case basis.

    Frequently Asked Questions

    What would the Clarity Act have changed for crypto regulation?
    The bill would have granted the CFTC full supervisory powers over crypto commodity spot markets—where Bitcoin and Ethereum primarily trade—while creating defined regulatory categories for blockchain assets, adding anti-illicit finance measures, and offering limited liability protections for DeFi software developers.
    Why did the legislation fail?
    The bill was derailed by unrelated provisions that had little to do with its primary regulatory objectives, though the source does not specify which particular sections caused the breakdown.
    How is the SEC responding to the legislative vacuum?
    The SEC is actively using its existing enforcement authority to police the digital asset sector, effectively filling the regulatory gap left by the Clarity Act’s failure through litigation and regulatory actions rather than new rulemaking.
  • ‘We have lost control’: Crypto pioneer warns AI could trigger systemic banking, infrastructure shocks

    ‘We have lost control’: Crypto pioneer warns AI could trigger systemic banking, infrastructure shocks

    Key Highlights

    • Hut 8 co-founder Marc van der Chijs has shifted to a “doomer” outlook on artificial intelligence, warning that humanity has lost control over the technology’s rapid development.
    • His concerns mirror warnings from Anthropic CEO Dario Amodei, who cautions that recursive AI self-improvement risks exceeding human control and causing widespread infrastructure damage.
    • Both leaders identify a structural competitive trap among companies and nation-states that penalizes restraint, making systemic disruption likely before international guardrails are established.

    From Bitcoin Pioneer to AI Skeptic: Van der Chijs Sounds Alarm

    Marc van der Chijs, the entrepreneur who co-founded the bitcoin mining firm Hut 8 (HUT), has issued a stark warning about the artificial intelligence sector to which his former company has pivoted. In an interview with CoinDesk, van der Chijs revealed a dramatic shift in his perspective, moving from viewing AI as a transformative opportunity comparable to bitcoin’s early days to fearing that the technology’s trajectory has escaped human governance.

    “I’ve become more of a doomer over the past week, to be honest,” he told CoinDesk. The admission marks a significant pivot for an investor who entered the cryptocurrency market in 2013 and has long championed disruptive technologies. While he maintains that AI will ultimately transform the global economy, van der Chijs now questions whether humanity can retain authority over its creation. “We have lost control, actually,” he said. “And until we get the control back, I’m actually worried that we’re moving too fast.“

    Echoes of Amodei: Converging Warnings from Industry Leaders

    Van der Chijs’s reversal aligns closely with recent public warnings from Dario Amodei, CEO of the AI safety and research company Anthropic. Amodei has urged technology leaders to slow the pace of frontier AI development, arguing that rapid progress—fueled by AI models recursively improving themselves—risks exceeding human control and causing widespread damage to critical infrastructure. Both men identify the same structural dynamic: an intense competitive race between corporations and nation-states that actively penalizes any individual actor who attempts to exercise restraint.

    This game-theoretic trap, they argue, makes systemic disruption or catastrophic failure appear almost inevitable before genuine international regulatory frameworks can be negotiated and enforced. The parallel between a bitcoin industry veteran and a frontier AI lab chief underscores a broadening consensus among technical insiders that the current governance gap represents an acute systemic risk.

    Why This Matters: The Governance Gap and the Risk of Crisis-Driven Policy

    The convergence of views from leaders in both the digital asset and artificial intelligence sectors highlights a maturing debate over technological governance. Van der Chijs fears that a major disruption—potentially affecting financial systems or critical infrastructure—may be the only catalyst sufficient to compel governments into meaningful cooperation. This scenario suggests a dangerous reliance on crisis-driven policymaking rather than proactive regulation. For investors and policymakers, the remarks signal that the “move fast and break things” paradigm may be reaching its logical limit in systems where the cost of failure is societal rather than commercial. The pivot of Hut 8 from bitcoin mining toward AI infrastructure adds institutional weight to the observation that capital is flowing into a sector its own pioneers increasingly view as inadequately controlled.

    Frequently Asked Questions

    Who is Marc van der Chijs and why does his opinion carry weight?

    Marc van der Chijs is a serial entrepreneur who co-founded Hut 8, one of North America’s largest bitcoin mining operations. His background in both cryptocurrency and traditional venture capital gives him a cross-sector perspective on disruptive technology cycles.

    What specific risks do van der Chijs and Amodei highlight?

    Both warn that recursive AI self-improvement, driven by unrestrained competition between companies and nations, could exceed human control and cause widespread damage to financial systems and critical infrastructure before international guardrails exist.

    Has Hut 8 officially pivoted to artificial intelligence?

    The source notes that Hut 8 has pivoted toward artificial intelligence technology, and van der Chijs’s comments reflect his concern about the technology “to which the company has pivoted.”

  • Chinese Whale May Have Made Another Large Altcoin Purchase as Token Surges

    Chinese Whale May Have Made Another Large Altcoin Purchase as Token Surges

    Key Highlights:

    • Garret Jin accumulated 202,080 ZEC worth approximately $88.3 million in December 2024; holdings now valued near $320 million as ZEC trades at $1,580.
    • The investor moved the full stack into Zcash shielded addresses before returning funds to transparent addresses within minutes, keeping all 202,080 ZEC under single-wallet control.
    • A concurrent short position of roughly 38,000 ZEC on Hyperliquid (current notional ~$60 million) carries a $34.5 million unrealized loss, functioning as a partial hedge against the much larger spot exposure.

    Whale Accumulation: December 2024 Withdrawals from Binance and Zcash

    Blockchain data and a screenshot shared by Garret Jin on X reveal a coordinated accumulation of Zcash ($ZEC) in late December 2024. On December 24, a wallet linked to Jin withdrew 68,080 ZEC from Binance when the asset traded near $436, valuing that tranche at roughly $29.7 million. Minutes earlier, the same wallet pulled 134,000 ZEC directly from the Zcash network, worth approximately $58.6 million at prevailing prices. Combined, the two transactions delivered 202,080 ZEC into a single address with a total cost basis near $88.3 million.

    Shielded Address Activity and Rapid Return to Transparency

    On-chain records show Jin subsequently moved the entire 202,080 ZEC balance into Zcash shielded addresses, leveraging the protocol’s zero-knowledge privacy feature. However, the assets were transferred back to transparent addresses within minutes, and the full position has remained in that wallet continuously since. The brief shielding event did not obscure the ultimate ownership or aggregate size of the holding, which remains publicly verifiable on transparent addresses.

    Price Surge Lifts Paper Gain to $232 Million

    With ZEC appreciation to $1,580, the spot position has swelled to an estimated $320 million in current market value. That translates to an unrealized dollar-denominated gain of approximately $232 million against the December acquisition cost. The magnitude of the appreciation underscores the volatile upside potential in privacy-focused crypto assets during broader market rallies.

    Hyperliquid Short Position Acts as Partial Hedge

    Simultaneously, Jin maintains a short position of roughly 38,000 ZEC on the decentralized perpetuals exchange Hyperliquid. At current prices, the short carries a notional value near $60 million and an unrealized loss of about $34.5 million. Analysts interpret the short as a deliberate hedge: should ZEC decline, profits on the perpetual contract would offset a portion of the spot drawdown, while the net exposure remains strongly long given the 202,080 ZEC spot holding versus the 38,000 ZEC short.

    Why This Matters

    The episode highlights how sophisticated participants manage concentrated positions in lower-liquidity privacy coins. Zcash’s dual address architecture—transparent and shielded—allows large holders to test privacy features without relinquishing auditability, a dynamic relevant for regulators and compliance teams monitoring anti-money-laundering (AML) risks. Meanwhile, the use of Hyperliquid for on-chain perpetual hedging demonstrates the growing role of decentralized derivatives venues in institutional-scale risk management. Market observers should watch whether the short position is adjusted, expanded, or closed as ZEC price action evolves, as changes could signal shifting conviction or risk appetite from one of the asset’s largest identifiable holders.

    Frequently Asked Questions

    Who is Garret Jin?

    Garret Jin is a pseudonymous cryptocurrency investor who publicly shares on-chain activity via his X (formerly Twitter) account. He is known for sizable positions in privacy-focused assets and for utilizing decentralized derivatives platforms such as Hyperliquid for hedging.

    Why did the ZEC move to shielded addresses and then back so quickly?

    The brief transfer to Zcash shielded addresses likely served as a functional test of the network’s privacy features or a tactical step for transaction privacy. Returning to transparent addresses within minutes kept the full balance visible on-chain, preserving verifiability of the total holding size.

    How does the Hyperliquid short position hedge the spot holding?

    The short position of ~38,000 ZEC represents roughly 19% of the 202,080 ZEC spot stack. If ZEC falls, gains on the short partially compensate for losses on the much larger long position, reducing net downside exposure while maintaining a predominantly bullish directional bet.

  • Ripple: Asset Managers Preparing for XRP Ledger’s Next Payments Upgrade

    Ripple: Asset Managers Preparing for XRP Ledger’s Next Payments Upgrade

    Key Highlights

    • The XRP Ledger’s Batch V1.1 amendment has secured support from 30 of 35 tracked validators, exceeding the 28-vote threshold to begin a 14-day activation countdown.
    • Batch enables exchanges, wallets, and marketplaces to attach service fees directly to customer transactions, processing payments and platform charges as a single atomic operation.
    • Activation is projected for September 29, 2024, provided validator support remains at or above 80%; the original Batch V1.0 was withdrawn in February after researchers discovered a critical signature-validation vulnerability.

    Batch Amendment Enters Activation Countdown With Strong Validator Consensus

    The XRP Ledger’s Batch amendment has officially entered its activation countdown after securing support from 30 of the network’s 35 tracked validators—well above the 28-vote supermajority required to trigger the two-week finalization window. The countdown commenced on September 15 at 14:06:41 UTC, positioning Batch V1.1 for projected activation shortly after the same time on September 29, provided validator backing holds at or above the 80% threshold throughout the period. Because validators retain the ability to change their votes, the activation date remains conditional until the window closes.

    Single-Operation Fee Attachment Streamlines Platform Economics

    Batch introduces a structural improvement for businesses operating on the XRP Ledger by allowing exchanges, wallets, and marketplaces to attach their service charges directly to a customer’s transaction. Rather than requiring separate transfers for the payment and the platform fee, both components are processed as one atomic operation. This design reduces operational complexity, lowers transaction overhead, and improves the user experience for applications that embed fee logic at the protocol layer.

    “Some projects are already being built with Batch in mind, so activation would allow that work to move closer to production,” Akinyele shared. “We’ll share more on specific partners and launch timing as those plans are finalized.”

    Security Remediation Paves Way for V1.1 Release

    The path to this activation follows a significant security intervention earlier this year. In February, researchers identified a critical flaw in Batch V1.0’s signature-validation process. Under certain conditions, the code could terminate signature checks prematurely, potentially allowing an attacker to include transactions from another account without the owner’s authorization. The vulnerability prompted developers to withdraw the original version entirely, delaying the feature’s deployment while a corrected implementation was developed and audited. Batch V1.1 incorporates the necessary fixes and has since undergone renewed validator scrutiny.

    Why This Matters

    Batch represents a meaningful evolution in the XRP Ledger’s native capabilities for composable, fee-aware transactions. By embedding platform economics directly into the ledger’s transaction model, the amendment reduces reliance on off-chain accounting or multi-step settlement flows—benefiting decentralized exchanges, custodial wallets, and payment processors that currently manage fee logic externally. The strong validator consensus signals network confidence in both the feature’s utility and the remediation of the V1.0 vulnerability. Successful activation would mark the restoration of functionality originally pulled over safety concerns, demonstrating the network’s governance process in action: identify, remediate, re-propose, and achieve supermajority approval.

    Frequently Asked Questions

    When will Batch V1.1 activate on the XRP Ledger?

    Batch V1.1 is projected to activate shortly after September 29, 2024, at 14:06:41 UTC, provided validator support remains at or above 80% for the full 14-day countdown window that began September 15.

    What was the critical flaw in Batch V1.0?

    Researchers discovered in February that Batch V1.0’s signature-validation process could stop checking signatures early under certain conditions, potentially allowing an attacker to include unauthorized transactions from another account. The original version was withdrawn and replaced by the corrected V1.1.

    How does Batch change fee processing for platforms on the XRP Ledger?

    Batch allows exchanges, wallets, and marketplaces to attach service fees directly to a customer’s transaction so that the payment and platform fee are processed as a single atomic operation, eliminating the need for separate transfers and reducing operational complexity.

  • Cryptocurrency App Secretly Steals Assets — Delete Immediately

    Cryptocurrency App Secretly Steals Assets — Delete Immediately

    Key Highlights

    • Blockchain security firm SlowMist, in collaboration with the OKX security team, discovered malicious code in FomoPeek versions 1.1 and 1.2 designed to steal private keys, seed phrases, and Keychain data from iOS devices.
    • The malware includes an exploit framework targeting iOS kernel vulnerabilities across versions 12.0 through 18.7 and 26.0–26.1, capable of bypassing sandbox protections and automatically selecting from eight attack methods based on device model.
    • SlowMist urges all affected users to immediately migrate assets to a new wallet generated on a clean device, update iOS to the latest version, and permanently cease using FomoPeek.

    SlowMist Uncovers Supply-Chain Attack in FomoPeek iOS App

    Blockchain security company SlowMist has issued a critical alert revealing that versions 1.1 and 1.2 of the FomoPeek application contain malicious code engineered to exfiltrate users’ private keys, seed phrases, login credentials, and other sensitive data stored in the iOS Keychain. The discovery followed reports from multiple FomoPeek users who experienced unexplained asset theft, prompting a joint forensic investigation by SlowMist and the OKX security team.

    Exploit Framework Targets Broad iOS Version Range

    According to SlowMist’s technical analysis, the compromised application bundles an exploit framework wholly unrelated to FomoPeek’s stated functionality. This framework specifically targets kernel vulnerabilities in Apple’s iOS operating system, supporting eight distinct attack vectors. The malware automatically fingerprints the victim’s device model and iOS version to select the appropriate exploit, enabling it to bypass the iOS sandbox and decrypt Keychain contents.

    The affected iOS versions span a remarkably wide range: iOS 12.0 through 18.7, as well as the newly released iOS 26.0 and 26.1. This coverage suggests the attackers maintained and updated their exploit chain over an extended period, potentially impacting millions of devices that have not applied the very latest security patches.

    Active Command-and-Control Infrastructure

    SlowMist researchers further determined that FomoPeek communicates with hidden command-and-control (C2) servers not associated with any legitimate public service. Analysis of intercepted unencrypted network traffic indicates the attack functions remain active and execute automatically at regular intervals, meaning the threat is ongoing and not merely a dormant payload.

    Why This Matters

    This incident represents a sophisticated supply-chain compromise targeting cryptocurrency users through a seemingly legitimate application. The breadth of iOS versions exploited underscores the persistent value of kernel-level vulnerabilities to threat actors and the difficulty of defending against zero-day or n-day exploits once they are weaponized in widely distributed software. For the crypto ecosystem, the case highlights the critical importance of verifying application integrity, using hardware wallets for significant holdings, and maintaining rigorous device hygiene. The collaboration between SlowMist and OKX also demonstrates the growing role of exchange security teams in threat intelligence sharing and incident response.

    Frequently Asked Questions

    Which FomoPeek versions are confirmed compromised?

    Only versions 1.1 and 1.2 have been identified as containing the malicious exploit framework and data-exfiltration code.

    What should I do if I installed FomoPeek 1.1 or 1.2?

    Immediately check your wallet for unauthorized transactions. Using a trusted device on which FomoPeek was never installed, generate a new private key and mnemonic phrase, then transfer all assets to the new wallet. Update your iPhone or iPad to the latest iOS version, delete FomoPeek, and do not reinstall it.

    Does updating iOS alone fix the problem?

    Updating iOS patches the kernel vulnerabilities used by the exploit, preventing future Keychain decryption. However, if your private keys or seed phrases were already stolen, the attacker retains control of the associated wallets. You must rotate credentials on a clean device as described above.

  • ‘The orange tie stays’: Michael Saylor responds to venture capitalist’s bitcoin obituary

    ‘The orange tie stays’: Michael Saylor responds to venture capitalist’s bitcoin obituary

    Key Highlights

    • Jason Calacanis declares Bitcoin “boring” as it returns to $80,000, criticizing its transaction utility, user experience, and cultural relevance.
    • Michael Saylor counters that Bitcoin has become a $1.6 trillion “Digital Capital” asset focused on generational wealth preservation.
    • The exchange highlights a fundamental divide between critics seeking utility and adoption metrics versus proponents viewing Bitcoin as a long-term store of value.

    Calacanis Declares Bitcoin’s Cultural Moment Has Passed

    As bitcoin reclaimed the $80,000 level on Friday, veteran investor Jason Calacanis took to social media to deliver a scathing assessment of the cryptocurrency’s current trajectory. “The dead cat continues to bounce,” wrote Calacanis, invoking a market term for a temporary recovery in a declining asset. He proceeded to dismantle the case for bitcoin across multiple dimensions, questioning its fundamental utility seventeen years after its inception.

    Utility, Experience, and the “Dinner Party” Test

    Calacanis argued that bitcoin fails as both a transactional medium and a platform for smart contracts, while presenting an “intimidating user experience” that alienates mainstream users. He contended the asset no longer captures the public imagination, applying a cultural litmus test: “If it comes up at the dinner party, it’s followed by a hearty ‘remember that!’” The investor suggested the narrative has shifted from wealth creation to stability expectations. “Folks expect bitcoin to be stable and that it’s no longer a way to get rich quick,” he continued. “It’s boring … Advocates went from pirates to suits in orange ties, awkwardly sharing cringe memes — just like the cool kids do!” His conclusion was definitive: “If Bitcoin were going to reach mass adoption and an important use case, it does better than anyone else, it would have by now.”

    Saylor Reframing: Digital Capital and Generational Wealth

    Michael Saylor, founder of MicroStrategy and bitcoin’s most prominent corporate advocate, issued a point-by-point rebuttal framing the asset in civilizational rather than consumer terms. “You’ve watched Bitcoin grow since 2011,” Saylor responded. “It’s now a $1.6 trillion success and the world’s most valuable digital asset.” He rejected the premise that transactional velocity or dinner-party relevance defines success. “Digital Capital is the killer app,” Saylor continued. “Preserving wealth across generations is a bigger ambition than entertaining a dinner party.” He closed with a symbolic declaration of continuity: “The orange tie stays.”

    Why This Matters

    The Calacanis-Saylor exchange crystallizes the central debate surrounding bitcoin in 2025: whether its value proposition lies in medium-of-exchange utility and mass consumer adoption — the original cypherpunk vision — or in settlement-layer “Digital Capital” serving as a sovereign-grade store of value. Calacanis represents the skeptic’s benchmark: seventeen years without Venmo-level usability or mainstream cultural currency suggests product-market fit failure. Saylor represents the institutional thesis: a $1.6 trillion market cap, nation-state accumulation strategies, and corporate treasury adoption prove the “digital gold” use case has already won. The “orange tie” motif — originally a bitcoin community signal — now functions as a Rorschach test: to critics, a symbol of cringe corporate co-option; to believers, a marker of institutional maturation. With bitcoin oscillating around $80,000, the next inflection point may depend less on technical upgrades and more on whether sovereign and corporate balance-sheet allocation continues to outpace retail onboarding.

    Frequently Asked Questions

    What triggered the Calacanis-Saylor exchange?

    Bitcoin’s return to the $80,000 price level on Friday prompted Jason Calacanis to post a critical thread questioning bitcoin’s utility, user experience, and cultural relevance after 17 years. Michael Saylor responded directly, reframing bitcoin as “Digital Capital” for generational wealth preservation.

    What is Michael Saylor’s “Digital Capital” thesis?

    Saylor argues bitcoin’s primary value proposition is not payments or smart contracts but serving as a sovereign-grade, digitally native store of value — “Digital Capital” — capable of preserving wealth across generations, a purpose he considers more significant than consumer adoption or dinner-party relevance.

    What does “the orange tie stays” signify?

    The orange tie has been a symbol worn by bitcoin advocates, including Saylor, representing conviction in the asset. Calacanis mocked it as “suits in orange ties, awkwardly sharing cringe memes.” Saylor’s closing line — “The orange tie stays” — signals institutional conviction remains unchanged despite criticism.

  • Robinhood Chain fees collapse 97% even as transactions stay near record highs

    Robinhood Chain fees collapse 97% even as transactions stay near record highs

    Key Highlights

    • Robinhood’s decentralized exchanges processed approximately $13 billion in weekly volume through September 16, marking a 5% increase from the prior week despite earlier fee spikes.
    • Applications built on the chain captured roughly $8 million in fees and retained $1.5 million in revenue over a recent 24-hour period, dwarfing the base network’s $230,000 take.
    • Top-ranked memecoin trader Unipcs asserts that elevated gas fees do not deter “trenchers” who trade newly launched tokens in their earliest hours, stating participants “don’t care about that as long as they can make money on the chain.”

    Weekly Volume Defies Fee-Driven Exodus Narrative

    Data covering the seven days through September 16 shows Robinhood’s decentralized exchanges handled about $13 billion in volume, a 5% rise from the preceding week according to CoinDesk calculations using DeFiLlama. The increase comes after market observers speculated that a collapsing fee chart signaled higher costs had chased traders toward Solana, taking Robinhood’s volume with them. Weekly figures instead reveal a narrower retreat, with stablecoin supply slipping just 1% to around $1 billion. Of that supply, approximately $930 million remains deployed in decentralized-finance applications, indicating sustained on-chain activity despite the earlier fee turbulence.

    Application Layer Captures Vast Majority of Economic Activity

    The economic disparity between the base layer and the applications built atop it remains pronounced. Over the latest 24-hour period tracked by DeFiLlama, businesses operating on the chain collected roughly $8 million in fees and retained approximately $1.5 million as revenue. By contrast, the underlying network itself accrued only $230,000. This dynamic underscores a structural reality where the application layer extracts the lion’s share of value generated by user activity, while the base settlement layer operates on a far thinner margin.

    Memecoin Traders Dismiss Gas Cost Concerns

    Pseudonymous trader Unipcs, who holds the top rank by all-time profit on FOMO—a platform that publicly tracks memecoin traders’ performance—maintained his positions through the recent market reversal. In a Telegram message to CoinDesk, he stated: “The earlier higher gas fees did not affect me or any trencher I know. People don’t care about that as long as they can make money on the chain.” The term “trencher” refers to participants who trade newly launched tokens in the earliest hours after they appear, when price movements are most violent and potential returns are highest. For this cohort, execution speed and early access outweigh transaction cost considerations.

    Why This Matters

    The divergence between network-level fees and application-level revenue highlights an evolving tension in blockchain economics. While base layers compete on cost and throughput to attract users, the applications capturing user-facing value—trading platforms, lending protocols, and memecoin launchpads—are accumulating the bulk of economic surplus. Robinhood’s volume resilience suggests that retail-oriented distribution channels can sustain activity even when base-layer fees fluctuate, provided the applications offer sufficient perceived opportunity. Meanwhile, the indifference of high-frequency memecoin traders to gas costs signals that for certain high-turnover strategies, fee sensitivity is secondary to liquidity and speed. Observers should monitor whether application-layer fee capture continues to outpace base-layer revenue, and whether stablecoin deployment in DeFi holds above the $930 million level as a proxy for sustained capital commitment.

    Frequently Asked Questions

    What was Robinhood’s decentralized exchange volume for the week ending September 16?

    Robinhood’s decentralized exchanges handled approximately $13 billion in volume during the seven days through September 16, representing a 5% increase from the prior week.

    How much revenue did applications on the chain generate compared to the base network?

    Over a recent 24-hour period, applications on the chain collected about $8 million in fees and retained $1.5 million in revenue, while the base network itself earned only $230,000.

    Who is Unipcs and what is a “trencher” in crypto trading?

    Unipcs is a pseudonymous trader ranked first by all-time profit on FOMO, a platform that publicly tracks memecoin trader performance. A “trencher” is someone who trades newly launched tokens in the earliest hours after they appear, when prices move most rapidly.

  • Why Wall Street Giants Are Building Tokenized Money for Institutions, Not Retail Investors

    Why Wall Street Giants Are Building Tokenized Money for Institutions, Not Retail Investors

    Key Highlights

    • Major financial institutions are simultaneously operating tokenized deposits, regulated stablecoins, and traditional correspondent accounts on separate infrastructure, creating operational complexity.
    • Fragmented liquidity across multiple networks multiplies capital inefficiency, with idle funds locked on five networks representing five times the inefficiency of a single pool.
    • Privacy and interoperability remain critical barriers: banks cannot expose client transaction data on public blockchains, while private blockchain bridges risk data leakage.

    The Multi-System Challenge Facing Treasury Desks

    Treasury operations at leading financial institutions are contending with a fragmented infrastructure landscape. According to Jerald David, CEO of Lynq Network, major banks are juggling three distinct systems for the same fundamental purpose: moving money. A single institution may run a JPMorgan tokenized deposit for one client, a regulated stablecoin for another, and a conventional correspondent account for a third. While the economic rationale for each transfer remains identical, the underlying rails differ entirely, forcing treasury desks to maintain parallel operational workflows.

    Tokenized Deposits vs. Stablecoins: Key Distinctions

    The distinction between tokenized deposits and stablecoins carries significant regulatory and functional implications. Unlike a stablecoin, a tokenized deposit remains a direct claim on the issuing bank. This structure enables it to bear interest, remain within the regulated banking perimeter, and potentially be programmed to settle against tokenized assets. The core question, as David frames it, is whether banks can deliver these benefits to consumers while preserving privacy, compliance, and control over who holds the deposit.

    Regulatory Advantages of Bank-Issued Tokenized Deposits

    Monument, highlighted by Bhandari, holds a banking licence that stablecoin issuers lack, permitting it to pay interest on deposits. The firm plans to launch tokenized savings accounts that earn yield—a capability unavailable to non-bank stablecoin operators. This regulatory foothold positions licensed institutions to offer interest-bearing, programmable deposit tokens that combine the efficiency of blockchain settlement with the consumer protections and yield generation of traditional banking.

    Privacy and Interoperability Hurdles on Public Infrastructure

    Public blockchain infrastructure presents a separate challenge for regulated entities. Fahmi Syed, President of the Midnight Foundation, emphasized that banks cannot expose clients’ transaction data and commercial relationships on transparent ledgers. Citibank and JPMorgan have recognized this constraint internally. Syed articulated the interoperability dilemma directly: “Once you create a private blockchain, how do you then speak to another private blockchain? You then have to use a bridge or some other mechanism, and at that point, you have data leakage.” This tension between privacy-preserving private networks and the need for cross-chain settlement remains unresolved.

    Why This Matters

    The convergence of tokenized deposits, stablecoins, and correspondent banking on disparate rails reflects a broader transition in wholesale and retail payments. As major banks experiment with tokenized liabilities, the industry faces a structural choice: consolidate liquidity onto interoperable standards or accept persistent fragmentation that inflates capital costs and operational risk. Regulatory clarity around interest-bearing tokenized deposits could accelerate adoption, but only if privacy-preserving interoperability solutions—such as zero-knowledge proofs or permissioned cross-chain protocols—mature sufficiently to satisfy compliance requirements. The next 12 to 18 months will likely determine whether bank-issued tokenized deposits become a mainstream payments rail or remain niche instruments constrained by infrastructure silos.

    Frequently Asked Questions

    How does a tokenized deposit differ from a stablecoin?

    A tokenized deposit is a direct claim on the issuing bank, remains within the regulated banking system, and can bear interest. A stablecoin is typically issued by a non-bank entity, backed by reserves, and does not carry a bank credit claim or interest-bearing capability.

    Why is fragmented liquidity across multiple networks a problem for clients?

    Idle liquidity locked across five separate networks creates five times the capital inefficiency compared to a single unified pool, forcing clients to allocate more capital to achieve the same operational coverage.

    What is the main barrier to using public blockchains for bank tokenized deposits?

    Public blockchains expose transaction data and commercial relationships, violating client privacy and regulatory obligations. Private blockchains solve privacy but create interoperability challenges, as bridges between them risk data leakage.

  • Hong Kong Jails Former Banker Over $1.6B False Credit, Cryptocurrency Bribes: Report

    Hong Kong Jails Former Banker Over $1.6B False Credit, Cryptocurrency Bribes: Report

    Key Highlights

    • Former China Construction Bank (Asia) customer relationship manager Lam Chun-yin sentenced to four years’ imprisonment for falsely authenticating letters of credit exceeding $1.6 billion.
    • District Court Judge Ernest Lin Kam-hung ordered restitution of over $470,000 in cryptocurrency bribes received by Lam, emphasizing deterrent sentencing for financial crimes.
    • Hong Kong’s Independent Commission Against Corruption (ICAC) has obtained arrest warrants for additional individuals connected to the scheme, signaling an expanding investigation.

    Ex-Bank Manager Jailed for $1.6 Billion Letter of Credit Fraud

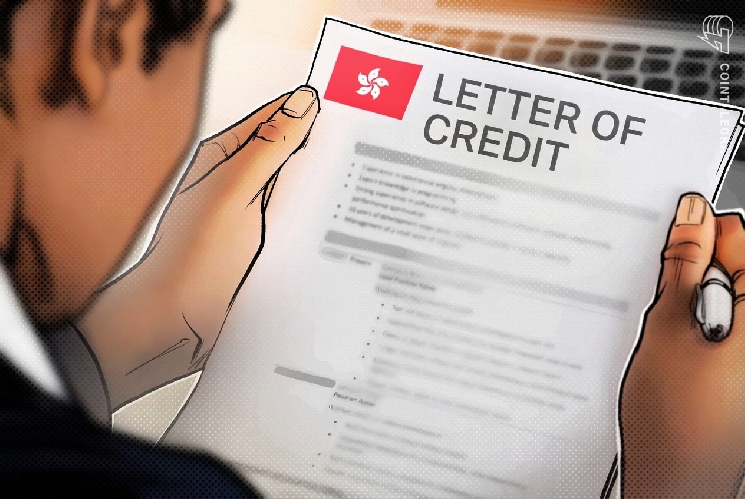
    A former customer relationship manager at China Construction Bank (Asia) has been sentenced to four years in prison after admitting to a massive trade finance fraud that undermined the integrity of Hong Kong’s banking system. Lam Chun-yin, 32, pleaded guilty in the District Court to falsely authenticating letters of credit valued at more than HK$12.5 billion (approximately US$1.6 billion), The Standard reported on Saturday.

    The scheme involved Lam exploiting his position to authorize fraudulent trade finance instruments, facilitating the movement of illicit funds through the banking network. In addition to the custodial sentence, Judge Ernest Lin Kam-hung ordered Lam to make restitution of more than HK$3.65 million (approximately US$470,000) that he had received in cryptocurrency bribes. The use of digital assets for corrupt payments highlights the evolving methods of financial crime in the region.

    Judiciary Stresses Deterrence to Protect Financial Hub Status

    In delivering the sentence, Judge Lin underscored the systemic risk posed by such offenses. “deterrent sentences are necessary even for first-time offenders, especially in light of the grave nature of the crime and its impact on society.” The judge further emphasized the foundational role of the financial sector, stating: “banking and insurance are the backbone of Hong Kong’s economy, and Lam’s scheme had served to undermine its standing as a global financial hub.”

    The court’s remarks reflect a broader regulatory posture that treats breaches of trust within authorized institutions as threats to the city’s reputation and stability. As an international financial center, Hong Kong relies on the integrity of its trade finance and correspondent banking relationships; fraudulent letters of credit distort risk assessments, expose counterparties to undisclosed liabilities, and erode confidence among global partners.

    ICAC Widens Net as Investigation Continues

    The Independent Commission Against Corruption (ICAC) has secured arrest warrants for other parties believed to be involved in the conspiracy, according to the report. This development indicates that the prosecution views Lam as one component of a larger network rather than a sole actor. The pursuit of additional suspects aligns with the ICAC’s standard practice of tracing both the facilitators and beneficiaries of corruption proceeds, particularly where cross-border fund flows and digital asset transfers are employed to obscure ownership.

    While the current case centers on traditional trade finance instruments, it occurs against a backdrop of rapid digital transformation in Hong Kong’s monetary infrastructure. In July, the Hong Kong Monetary Authority (HKMA) launched a framework to assess banks’ preparedness for quantum-computing threats as the city expands its use of tokenized deposits, digital assets, and blockchain settlement. The HKMA targets full sector readiness by 2030, underscoring that the same institutions targeted by fraudsters are simultaneously being upgraded for next-generation financial rails.

    Why This Matters

    The sentencing of Lam Chun-yin carries significance beyond the individual penalty. It demonstrates that Hong Kong’s courts and anti-graft agencies are willing to impose substantial custodial terms and asset recovery orders—even for first-time offenders—when crimes strike at the core of trade finance. The restitution order denominated in cryptocurrency also sets a practical precedent for tracing and clawing back digital-asset proceeds of corruption. With the ICAC actively pursuing co-conspirators, the case may reveal further vulnerabilities in bank internal controls, prompting tighter know-your-customer (KYC) and transaction monitoring standards across the sector. At the same time, the HKMA’s quantum-readiness initiative signals that regulators are preparing defenses not only against current fraud typologies but also against future cryptographic risks to the digital financial infrastructure now being built.

    Frequently Asked Questions

    What was Lam Chun-yin’s role at China Construction Bank (Asia)?
    Lam served as a customer relationship manager, a position that gave him authority to authenticate trade finance documents such as letters of credit.
    How much money was involved in the fraudulent letters of credit?
    The falsely authenticated letters of credit exceeded HK$12.5 billion (approximately US$1.6 billion) in total value.
    What further action is the ICAC taking?
    The ICAC has obtained arrest warrants for other individuals connected to the case, indicating an ongoing investigation into a broader network of participants.