Author: Evan Mercer

  • Why Trump backed a crypto ethics rule that stopped at the family business

    Why Trump backed a crypto ethics rule that stopped at the family business

    Key Highlights

    • The CLARITY Act’s failed ethics provision would have required senior federal officials to divest crypto-related equity holdings above $15,000 or place them in qualified blind trusts, covering spouses but not adult children.
    • Commerce Secretary Howard Lutnick’s transfer of Cantor Fitzgerald ownership to trusts benefiting his adult children illustrates the gap between legal separation and ongoing family financial exposure to crypto policy.
    • The Senate bill’s collapse leaves unresolved how far conflict-of-interest rules should extend when government policy can rapidly alter the value of family-held digital asset businesses.

    The CLARITY Act’s Ethics Provision: What It Targeted

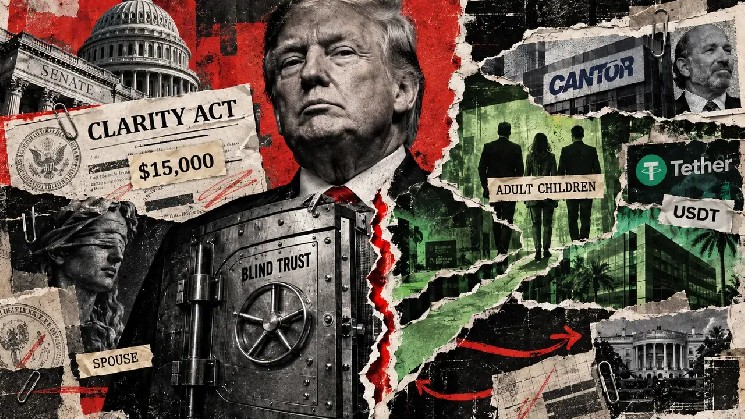
    The final Senate draft of the Clarifying Law Around Regulations of Innovative Technology (CLARITY) Act contained a narrowly tailored ethics rule that came surprisingly close to becoming law before the bill stalled on Sept. 15. The provision would have applied to the president, vice president, senior executive officials, members of Congress, and other federal officeholders already subject to public financial-disclosure requirements. It mandated that any covered official holding an equity interest worth at least $15,000 in a business whose largest revenue source in any of the preceding three calendar years was issuing or sponsoring digital assets—excluding tokenized traditional assets—must either sell that interest or place it into a qualified blind trust. The same restriction extended to spouses, but adult children were explicitly excluded.

    Republicans characterized the final draft as incorporating most of a bipartisan ethics proposal and dozens of changes requested by Democrats. Yet several Democrats withheld support, arguing the protections did not go far enough. The disagreement centered less on the mechanics of the rule than on where the line between an official’s financial interest and the family’s should be drawn—a distinction that has become increasingly consequential as crypto ventures proliferate among political families.

    The Lutnick Case: Legal Separation vs. Family Economic Reality

    Commerce Secretary Howard Lutnick provides a real-world case study of why that boundary matters. Before joining President Donald Trump’s Cabinet in February 2025, Lutnick spent decades running Cantor Fitzgerald, a major Wall Street trading and investment firm that became deeply embedded in the crypto ecosystem through its relationship with Tether, issuer of the world’s largest stablecoin, USDT. Cantor has held billions of dollars in U.S. Treasuries for Tether and serves as reserve custodian and preferred primary dealer for Tether’s regulated U.S. stablecoin.

    Upon entering government, Lutnick stepped down from Cantor and, in October 2025, transferred his ownership through trusts benefiting his adult children. His son Brandon now runs the company and serves as controlling trustee of the trusts holding the voting interests. Securities and Exchange Commission filings confirm that after the transfer, Howard Lutnick no longer held beneficial ownership of the securities tied to that control structure. Legally, the separation is clean. Economically, however, the family remains heavily exposed to a business whose fortunes are directly affected by federal stablecoin regulation, banking access rules, and securities law—all policy levers within the Commerce Department’s sphere of influence.

    Blind Trusts vs. Family Transfers: A Critical Distinction

    The CLARITY draft’s blind-trust requirement highlighted a common misconception. In federal ethics law, a qualified blind trust is not merely an arrangement where an official transfers assets to a trustee and promises not to interfere. It requires an independent trustee and strict limits on the official’s knowledge of, and control over, the investments. The purpose is to prevent the officeholder from knowing enough about the portfolio to shape government decisions around particular holdings. Moreover, federal ethics guidance generally treats the original holdings as known until the trustee disposes of them or they fall below the relevant threshold; an official cannot erase knowledge of owning a company simply by signing a trust agreement.

    Lutnick’s structure, by contrast, removed his control while deliberately keeping ownership within the next generation of the family. That is a legitimate estate-planning and ethics-compliance move under current law, but it falls short of the blind-trust standard the CLARITY draft would have imposed for certain covered holdings. The bill’s language specified that under this provision, the trustee’s actions and those of businesses held by the trust would not be attributed to the official, though existing conflict-of-interest laws would still apply.

    Where the Bill Drew the Line—and Why It Mattered

    Federal conflict law has traditionally drawn the attribution line close to the official: financial interests of a spouse or minor child can be attributed to an executive-branch employee, but an independent adult child’s interests generally are not. That principle prevents the law from assuming every financially independent son or daughter is simply an extension of a government official. Crypto makes the consequences of that boundary much easier to see. A parent can leave office-facing control behind while the next generation continues running a business tied to stablecoins, token issuance, or Bitcoin finance—sectors whose economics can shift rapidly with federal policy.

    The Trump family illustrates the same dynamic. Trump’s latest certified financial disclosure showed more than $1.4 billion in 2025 income from crypto ventures, according to Reuters, with most connected to World Liberty Financial and the Trump meme coin business. World Liberty was founded with members of his family, including his sons. The White House has said Trump’s finances are managed by his children and that his private interests don’t influence administration policy. Under the Senate proposal, a qualifying interest still owned by Trump himself could have required divestment or a blind trust, as would his spouse’s holdings. Ownership held independently by adult children would fall outside that particular requirement.

    Why This Matters

    The collapse of the CLARITY Act leaves a regulatory vacuum that extends beyond market structure into the heart of government ethics. As digital asset businesses become major sources of private wealth for political families, the speed with which federal policy—stablecoin legislation, banking guidance, securities enforcement—can alter the value of those holdings creates a persistent conflict-of-interest challenge. Congress can require a president or Cabinet secretary to sell an asset or submit to a qualified blind trust. What it has not settled is how far those restrictions should follow the money once the business passes to the next generation. Until that question is answered, the gap between legal compliance and public confidence will remain a defining feature of crypto-era governance.

    Frequently Asked Questions

    What specific holdings would the CLARITY Act ethics rule have covered?

    The rule targeted equity interests worth at least $15,000 in businesses or subsidiaries whose largest revenue source in any of the preceding three calendar years was issuing or sponsoring digital assets, excluding tokenized traditional assets. It also restricted officials from issuing or sponsoring digital assets for compensation. Simply holding Bitcoin or other tokens would not have triggered the requirement unless the official held equity in a qualifying issuer or sponsor.

    Why were adult children excluded from the ethics provision?

    Federal conflict law traditionally does not automatically attribute the financial interests of independent adult children to a government official. The CLARITY draft followed that precedent, covering the official and spouse but not adult children. Several Democrats opposed the bill in part because they believed this exclusion left too much room for families to remain financially connected to crypto businesses while the government writes the industry’s rules.

    How does a qualified blind trust differ from transferring a company to family members?

    A qualified blind trust requires an independent trustee and strict limits on the official’s knowledge of and control over investments. The original holdings are treated as known until the trustee disposes of them. Transferring a family company to adult children, as Howard Lutnick did, removes the official’s control but deliberately keeps ownership and economic exposure within the family—a legal separation that does not meet the blind-trust standard.

  • Fetch.ai Investigates Token Conversion Contract Exploit

    Fetch.ai Investigates Token Conversion Contract Exploit

    Key Highlights

    • Fetch.ai is actively investigating a reported exploit targeting its token conversion contract, prompting immediate security scrutiny.
    • The project’s official X account (@Fetch_ai) has warned users to rely exclusively on official communication channels for updates.
    • The incident has introduced uncertainty into Fetch.ai trading activity, with market participants awaiting investigation results.

    Fetch.ai Launches Investigation Into Token Conversion Contract Exploit Reports

    Fetch.ai, the decentralized platform leveraging artificial intelligence-driven agents for automation, has confirmed it is investigating reports of a security exploit involving its token conversion contract. The announcement, disseminated through the project’s official X account @Fetch_ai, marks a critical moment for the blockchain network as it confronts potential vulnerabilities in its core infrastructure. The development team’s proactive disclosure signals a commitment to transparency, though the situation has already cast a shadow over user confidence and market sentiment surrounding the FET token ecosystem.

    Official Channels Emphasized Amid Security Scrutiny

    In its public communication, Fetch.ai explicitly urged community members and token holders to trust only verified official channels for information regarding the ongoing investigation. This directive underscores the heightened risk of misinformation, phishing attempts, and social engineering attacks that typically proliferate during security incidents in the cryptocurrency space. The project’s emphasis on channel verification reflects broader industry best practices for incident response, where controlling the narrative and preventing scam exploitation are paramount to protecting the user base.

    Market Reaction Reflects Investor Apprehension

    Trading activity for Fetch.ai currently shows no reported volume or price data, a phenomenon that market observers attribute to the uncertainty generated by the exploit announcement. The absence of liquidity metrics suggests that investors and traders are adopting a wait-and-see posture, reluctant to commit capital until the scope and severity of the vulnerability are clarified. This trading pause highlights the acute sensitivity of digital asset markets to security-related news, particularly for protocols like Fetch.ai that position themselves at the intersection of blockchain and artificial intelligence infrastructure.

    Why This Matters: Security Trust in AI-Blockchain Convergence

    The Fetch.ai exploit investigation carries significance beyond a single protocol’s technical challenges. As a platform building at the convergence of decentralized ledger technology and autonomous AI agents, Fetch.ai represents a category of infrastructure where security assumptions are still being stress-tested in production environments. Token conversion contracts—critical bridges for asset interoperability—are high-value targets for attackers due to their liquidity concentration and complex logic. The outcome of this investigation will likely inform security standards across the emerging AI-agent blockchain sector, influencing how developers architect conversion mechanisms, how auditors assess multi-layer protocols, and how users evaluate risk in systems where autonomous agents execute financial transactions. Regulatory observers will also monitor the response, as incident handling transparency becomes a benchmark for consumer protection in decentralized finance.

    Frequently Asked Questions

    What specific component of Fetch.ai is under investigation?

    The investigation focuses on the project’s token conversion contract, a smart contract mechanism responsible for facilitating asset exchanges or migrations within the Fetch.ai ecosystem. No other protocol components have been implicated in the current reports.

    Where should users obtain verified updates about this situation?

    Fetch.ai has directed all community members to rely exclusively on its official communication channels, particularly its verified X account @Fetch_ai, for accurate and timely information regarding the investigation’s progress and any required user actions.

    Has the exploit affected FET token trading on exchanges?

    Current market data indicates no reported trading volume or price for Fetch.ai, suggesting that exchanges may have suspended trading or that market participants have withdrawn liquidity pending clarification of the security incident’s scope and resolution.

  • Gen Z Invests Like Boomers, But Makes Surprising Portfolio Choices

    Gen Z Invests Like Boomers, But Makes Surprising Portfolio Choices

    Key Highlights

    • Gen Z investors on Binance are directing more than twice as much equity trading volume toward unleveraged ETFs (25%) compared to millennials (9.5%), with ETF inflows remaining resilient even as overall investment declined.
    • Gen Z accounts show the lowest trading turnover across direct equities, tokenized bStocks, and TradFi perpetuals among working-age cohorts, with 76% of bStocks accounts and 77% of direct-equity accounts acting as net accumulators.
    • Despite growing up with crypto-native products, Gen Z users treat leveraged instruments as short-term tools rather than core holdings, allocating less than 3% of net inflows to leveraged and inverse ETFs by early August.

    Gen Z Investors Defy Risk Stereotypes with Conservative Portfolio Behavior on Binance

    A new Binance Research report published August 12 reveals that the youngest cohort of investors on the exchange is exhibiting surprisingly traditional investment habits, challenging assumptions that digital-native generations gravitate exclusively toward high-risk, speculative assets. The analysis, covering Binance users over a short period after the direct-equity product reached scale in June 2026, shows Gen Z participants recording the lowest portfolio turnover across all three major product lines: direct equities, tokenized bStocks, and TradFi perpetuals.

    ETF Adoption Outpaces Older Generations

    The clearest divergence appears in exchange-traded fund usage. In the first days of August, ETFs accounted for 25% of Gen Z’s direct-equity trading volume, up from 14.6% in June. Millennials, by comparison, allocated just 9.5% of their equity volume to funds during the same period. The inflow data reinforces this trend: unleveraged ETFs captured 18.5% of Gen Z’s net equity inflows in June and 21.9% in July, while the share directed to individual stocks declined from 77% to 74.2%.

    July saw a broad pullback in Gen Z equity deployment, with net investment falling 17.4%. However, unleveraged ETF inflows barely moved, declining only 2%, versus a 20.4% drop for single-stock inflows and a 28.5% drop for leveraged products. Gen Z was also the only cohort whose ETF holder base expanded in July, growing 2.9% while millennial and Gen X holders fell 4.5% and 5.9% respectively. This suggests ETFs function as a core allocation rather than a peripheral trade.

    Holdings Reflect Quality Bias Over Lottery Tickets

    Among Gen Z accounts that had only bought and never sold, the largest average direct-equity purchase was Schwab’s US Dividend Equity ETF (SCHD) at $16,567 per trade, followed by Broadcom at $12,370. While overall holdings show a semiconductor and artificial intelligence tilt, smaller average purchases went to names associated with retail speculation such as Tesla ($633) and Nvidia ($514 in bStocks). The pattern indicates larger tickets flow toward dividend and quality factors, while speculative names receive smaller position sizing.

    Holding behavior supports the accumulation narrative. Approximately 22% of Gen Z direct-equity accounts had never placed a sell order, compared with 19% for Gen X and 9% for Baby Boomers. Millennials led this metric at 30%. When the definition expands to net accumulators (buying more than selling), Gen Z moves to the front: 76% of bStocks accounts and 77% of direct-equity accounts were net accumulators, the highest shares across all generations.

    Perpetuals Used for Trading, Not Capital Formation

    Gen Z’s engagement with TradFi perpetuals reveals a similar discipline. The average Gen Z account executed 13 perpetual trades per month, below millennials (17), Gen X (16.5), and Baby Boomers (19). Only 14% of Gen Z perpetual accounts qualified as high-frequency, lower than all other working-age cohorts and even below boomers at 16%.

    Avoidance of leveraged and inverse products is pronounced: 88.2% of Gen Z TradFi-perpetual accounts recorded no activity in these instruments, compared with 84.5% for millennials and 85.9% for Gen X. In bStocks, 98.9% of Gen Z accounts avoided them entirely. Baby Boomers remain the most conservative overall, with 98.9% of direct-equity accounts avoiding leveraged and inverse products versus 96.5% for Gen Z.

    Leverage Treated as Tactical, Not Strategic

    The data shows leverage is used as intended: for short-term positioning rather than capital parking. Leveraged and inverse ETFs represented 9.25% of Gen Z direct-equity turnover in July but only 3.93% of net inflows, falling further to 2.65% by early August. TradFi perpetuals show a comparable pattern: roughly 60% of Gen Z accounts were net buyers (the highest proportion of any age group), yet net flow represented less than 1% of gross volume, indicating rapid position cycling.

    By contrast, direct equities displayed a net flow ratio of 26.5% with average net inflows of $1,898 per account. The distinction underscores that persistent capital is allocated to ownership-oriented products while derivatives serve tactical purposes.

    Why This Matters: Emerging-Market Access Reshapes Brokerage Dynamics

    Binance’s earlier research on the next generation of investors provides context for this behavior. Gen Z comprises approximately 44% of direct-stock and bStocks users and 45% of TradFi-perp users, making it the largest cohort in direct stocks and bStocks and roughly level with millennials in perpetuals. More than 90% of TradFi users across generations reside in emerging markets, where accessing US securities through conventional domestic brokers can be significantly more difficult.

    For many of these users, the crypto exchange functions as the most accessible brokerage they have encountered. The interface is familiar, accounts are pre-funded, fractional exposure is available, and markets operate outside standard US trading hours. Binance reported that 13% of all Direct Stocks users were Gen Z customers in emerging markets with less than $2,000 in equity assets. This structural advantage allows the platform to capture ordinary investment flows without converting every user into a high-frequency derivatives trader.

    Crypto-Native Doesn’t Mean Risk-Seeking

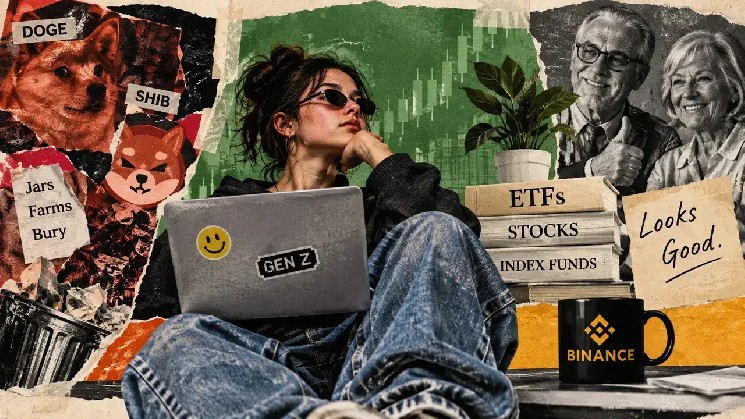
    The contrast with earlier crypto cycles is stark. Products like Pickle Finance, with its “Jars” and “Farms” compounding returns across protocols, and ShibaSwap, using terms like “Bury” for staking with tokens named SHIB, LEASH, and BONE, created a vernacular that made decentralized finance sound, in the report’s words, “like a pension designed during a prolonged supermarket incident.” A decade of such experimentation fostered an assumption that generations raised on Dogecoin would embrace financial complexity.

    Instead, the data shows younger users allocating a growing share of equity capital to unleveraged ETFs, trading less frequently than older cohorts, and confining leveraged exposure to a small slice of net investment. This does not signal an abandonment of crypto: a 2023 FINRA Foundation and CFA Institute survey found 55% of US Gen Z investors owned cryptocurrency, and CryptoSlate has previously documented broader young American appetite for crypto assets. Rather, it suggests that using crypto infrastructure and seeking maximum financial risk are distinct preferences.

    For a user whose first financial interface was an exchange app, Binance does not represent a rebellious alternative to a traditional brokerage; it is simply the financial infrastructure they know. Once stocks and ETFs appear within that interface, there is no imperative for their investment taste to mirror the branding of crypto’s earlier years. Gen Z is not replicating 1990s wealth management—semiconductor exposure, AI stocks, tokenized equities, and 24-hour markets are modern tools—but they are applying an old-fashioned instinct: buy, hold, and avoid making every position dependent on leverage. The crypto industry spent years making finance stranger to attract younger users; the youngest users may have taken the interface and left some of the weirdness behind.

    Frequently Asked Questions

    How does Gen Z’s ETF usage compare to older generations on Binance?

    In early August, ETFs accounted for 25% of Gen Z’s direct-equity trading volume, more than double the 9.5% seen among millennials. Gen Z was also the only cohort to grow its ETF holder base in July (+2.9%), while millennial and Gen X holders declined.

    Are Gen Z investors avoiding leverage entirely?

    No. Gen Z accounts do trade leveraged products and perpetuals, but they treat them as short-term tactical tools. Leveraged and inverse ETFs represented over 9% of turnover in July but less than 3% of net inflows, and perpetual net flows were under 1% of gross volume, indicating rapid position cycling rather than capital allocation.

    Why are so many Gen Z users in emerging markets using Binance for traditional equities?

    Over 90% of Binance’s TradFi users across all generations are based in emerging markets where accessing US securities through domestic brokers is difficult. Binance offers a familiar, pre-funded interface with fractional shares and extended trading hours, effectively serving as the most accessible brokerage for these users.

  • REX Launches 2x Leveraged ETF Tied to Bitcoin Treasury Firm Strive

    REX Launches 2x Leveraged ETF Tied to Bitcoin Treasury Firm Strive

    Key Highlights

    • REX Shares and Tuttle Capital Management launched the T-REX 2X Long ASST Daily Target ETF (ticker: ASSX) on Cboe, offering 200% daily leveraged exposure to Strive shares.
    • Strive, a Bitcoin treasury company, holds 25,000 BTC—ranking as the fifth-largest publicly traded corporate Bitcoin holder—and recently acquired 469 BTC via its SATA perpetual preferred stock.
    • The fund resets leverage daily and does not hold Bitcoin directly; Strive shares closed Friday at $30.09, up 6.4%, above the $29.40 average analyst price target.

    REX and Tuttle Debut Double-Leveraged Strive ETF on Cboe

    REX Shares and Tuttle Capital Management have expanded their lineup of single-stock leveraged exchange-traded funds with the launch of the T-REX 2X Long ASST Daily Target ETF, which began trading Friday on Cboe Global Markets under the ticker ASSX. The fund is engineered to deliver twice the daily percentage change of Strive (ticker: ASST) shares before fees and expenses, providing traders with a magnified bet on the Bitcoin treasury company’s equity performance rather than on the cryptocurrency itself.

    Mechanics and Distinction From Spot Bitcoin ETFs

    Unlike the spot Bitcoin ETFs that have dominated inflows this year, ASSX holds no Bitcoin and does not seek to track the price of BTC. Instead, it uses swap agreements and other derivatives to achieve 200% daily exposure to Strive’s share price. Because the fund resets its leverage at the end of each trading session, returns over periods longer than a single day can diverge materially from two times the cumulative performance of Strive stock—a characteristic common to all daily-reset leveraged ETFs and a critical risk factor for investors holding beyond intraday horizons.

    Strive’s Bitcoin Treasury Profile

    Strive, founded by Vivek Ramaswamy and Anson Frericks, operates as both an asset manager and a corporate Bitcoin accumulator. According to data from BitcoinTreasuries.NET, the company holds approximately 25,000 BTC, placing it fifth among publicly traded corporate holders behind MicroStrategy (now Strategy), Marathon Digital, Riot Platforms, and Hut 8. Strive financed its most recent acquisition of 469 BTC through sales of its SATA perpetual preferred stock, a structure designed to avoid shareholder dilution while expanding the treasury.

    Why This Matters

    The launch of ASSX signals growing sophistication in the crypto-adjacent ETF ecosystem, moving beyond direct spot exposure into derivative instruments tied to Bitcoin-correlated equities. Strive’s unique model—combining asset management with a corporate treasury strategy—creates a distinct risk-return profile: its share price reflects both Bitcoin’s volatility and the market’s valuation of its capital-allocation decisions. For traders, ASSX offers a tool to express high-conviction, short-term views on Strive specifically, while the broader suite of 2x ETFs from REX and Tuttle—covering Strategy (MSTR), BitMine (BITF), Cipher Mining (CIFR), Circle (CRCL), and SharpLink (SBET)—enables sector-wide leveraged plays. With Strive shares trading above the consensus 12-month price target of $29.40 (per S&P Global), the market appears to be pricing in continued treasury expansion, though the daily-reset mechanism makes ASSX unsuitable for passive long-term holders.

    Frequently Asked Questions

    Does ASSX hold Bitcoin directly?
    No. ASSX does not hold Bitcoin or track its price. It seeks 200% of the daily performance of Strive (ASST) shares through derivative contracts.
    How does the daily leverage reset affect returns?
    Because ASSX resets its 2x leverage daily, holding the fund for more than one trading day can result in returns that differ significantly from twice Strive’s cumulative performance due to compounding effects, especially in volatile markets.
    What other 2x leveraged ETFs do REX Shares and Tuttle Capital Management offer?
    The firms also provide 2x ETFs linked to Strategy (MSTR), BitMine (BITF), Cipher Mining (CIFR), Circle (CRCL), and SharpLink (SBET).
  • Analyst Behind Viral Model Reveals Bitcoin’s Next Bullish Target

    Analyst Behind Viral Model Reveals Bitcoin’s Next Bullish Target

    Key Highlights

    • Bitcoin has closed above the 50-week moving average (~$79,000), with the next technical target at the 100-week moving average (~$89,000).
    • Analyst PlanB declares the Bitcoin bear market over, citing August’s close at $78,571 and recovery across multiple market indicators.
    • Profitable Bitcoin supply surged from 50% to 72%, while the monthly RSI climbed from 41 to 51, signaling strengthening momentum.

    Bitcoin Breaks Key Technical Barrier as PlanB Signals Bear Market End

    Bitcoin’s price action has crossed a critical threshold, closing above the 50-week moving average near $79,000 and trading around $81,000 at the time of analysis. Widely followed pseudonymous analyst PlanB highlighted the development, stating, “Bitcoin closed above the 50-week moving average. The next target is the 100-week moving average, around $89,000.” This technical milestone positions the asset for a potential test of the longer-term 100-week average, a level historically associated with major trend transitions.

    Multiple On-Chain and Momentum Indicators Confirm Recovery

    Beyond the moving average crossover, PlanB emphasized a confluence of supporting data points. The analyst noted that August concluded with Bitcoin at $78,571, marking a turning point after which various market indicators began to recover. Notably, the percentage of Bitcoin supply in a profitable state has jumped significantly from 50% to 72%, reflecting a broad improvement in holder economics. Simultaneously, the monthly Relative Strength Index (RSI) has risen from 41 to 51, crossing above the neutral 50 threshold and indicating a shift from bearish to bullish momentum on the macro timeframe.

    Analyst Concludes Bottom Is Likely In

    Synthesizing these technical and on-chain metrics, PlanB assessed that the bear market in Bitcoin has ended and that the cryptocurrency may have already passed its cycle bottom. The combination of price reclaiming the 50-week moving average, expanding profitable supply, and improving momentum oscillators constructs a technical framework that supports bullish expectations for the upcoming period. While the analyst’s commentary carries weight in the crypto community, the standard disclaimer applies: This is not investment advice.

    Why This Matters

    The 50-week and 100-week moving averages are among the most watched long-term trend filters in Bitcoin technical analysis. A sustained close above the 50-week average has historically preceded extended uptrends, while the 100-week average often acts as a “line in the sand” between bull and bear market regimes. The simultaneous improvement in realized profitability metrics—from 50% to 72% of supply in profit—suggests a reduction in unrealized losses across the network, which typically reduces selling pressure. The monthly RSI reclaiming 50 adds a momentum confirmation that has been absent during the recent consolidation phase. Together, these factors align with a classic market structure shift from accumulation to markup, though macroeconomic risks and regulatory developments remain external variables.

    Frequently Asked Questions

    What are the specific price levels for the 50-week and 100-week moving averages mentioned by PlanB?
    The 50-week moving average sits around $79,000, which Bitcoin has now closed above. The next target, the 100-week moving average, is approximately $89,000.
    What on-chain metric showed the most dramatic improvement according to the analysis?
    The percentage of Bitcoin supply in a profitable state increased from 50% to 72%, a 22-percentage-point jump indicating significantly healthier holder economics across the network.
    Does PlanB’s analysis constitute a price prediction or investment recommendation?
    No. The analysis presents a technical assessment based on moving averages, profitability ratios, and momentum indicators. The source explicitly includes the disclaimer: “This is not investment advice.”
  • Fetch.ai Loses $2M After Security Flaw Discovered

    Fetch.ai Loses $2M After Security Flaw Discovered

    Key Highlights

    • Fetch.ai suffered an approximately $2 million exploit targeting its TokenConversionManagerV3 smart contract via a flawed conversionIn() function and a leaked private key.
    • The breach drained the contract’s entire FET token balance, prompting a market pause with reported trading volume dropping to $0 amid trader uncertainty.
    • Security firm SlowMist Team flagged the vulnerability, underscoring persistent risks in smart contract authorization logic across the crypto ecosystem.

    Fetch.ai TokenConversionManagerV3 Exploit Drains $2 Million in FET Tokens

    Decentralized autonomous agent platform Fetch.ai disclosed a significant security breach late this week, confirming a loss of roughly $2 million after an attacker exploited a critical vulnerability in its TokenConversionManagerV3 contract. The incident, first highlighted by blockchain security auditor SlowMist Team on CryptoTwitter, has reignited concerns over authorization logic flaws in production-grade smart contracts.

    Technical Breakdown: Authorization Flaw in conversionIn() Function

    According to the technical analysis, the vulnerability resided in the contract’s conversionIn() function, which lacked sufficient access-control checks. The attacker leveraged a leaked private key to authorize a malicious transaction, effectively bypassing intended safeguards and draining the contract’s full FET token balance. SlowMist Team’s alert emphasized that the flaw was not in the underlying cryptography but in the contract’s failure to validate caller permissions before executing high-value state changes.

    Market Reaction: Trading Volume Flatlines as Community Awaits Response

    Immediate market data reflects acute uncertainty. Fetch.ai’s reported trading volume plummeted to $0 across major tracking platforms, signaling a de facto pause in liquidity as traders and liquidity providers assess the fallout. Price discovery has stalled, with order books thinning out ahead of any official remediation announcement. The project’s reputation for enabling autonomous economic agents—its core value proposition—now faces scrutiny over the robustness of the infrastructure supporting those agents.

    Why This Matters: Smart Contract Security Under the Microscope

    The Fetch.ai exploit is the latest in a string of high-profile incidents where insufficient authorization logic—rather than cryptographic breaks—led to direct asset loss. As decentralized finance (DeFi) and agent-based economies scale, the attack surface of upgradeable, multi-contract systems expands. Auditors and developers are increasingly focusing on formal verification of access-control patterns and private-key management hygiene for privileged roles. The community will closely monitor Fetch.ai’s post-mortem, patch timeline, and whether an independent audit is commissioned before the contract family is redeployed.

    Frequently Asked Questions

    What exactly was exploited in the Fetch.ai TokenConversionManagerV3 contract?

    The attacker exploited a missing authorization check in the conversionIn() function, using a leaked private key to authorize a transaction that drained the contract’s entire FET balance.

    How much was lost and what is the current market status?

    Approximately $2 million in FET tokens was drained. Following the exploit, Fetch.ai’s trading volume dropped to $0, indicating a temporary market pause while stakeholders await the project’s response.

    Who discovered the vulnerability and what are the next steps?

    Blockchain security firm SlowMist Team identified and publicized the vulnerability on CryptoTwitter. The community is now awaiting Fetch.ai’s official post-mortem, security patch, and potential third-party audit before confidence can be restored.

  • Bitcoin Still Far From ‘Digital Gold,’ Says Bybit’s Ben Zhou

    Bitcoin Still Far From ‘Digital Gold,’ Says Bybit’s Ben Zhou

    Key Highlights

    • Bybit CEO Ben Zhou states Bitcoin remains a “considerable distance” from achieving mature ‘digital gold’ status due to persistent volatility.
    • Zhou suggests stablecoins may prove more effective than Bitcoin for everyday transactional use, signaling a potential divergence in crypto utility.
    • Bitcoin’s market-cap dominance has surged to 45%, reflecting shifting trader sentiment amid fluctuating stablecoin demand.

    Bybit CEO Ben Zhou Questions Bitcoin’s ‘Digital Gold’ Maturity Amid Volatility Concerns

    In a recent statement reported by prominent crypto commentator @WuBlockchain, Bybit Chief Executive Officer Ben Zhou offered a sobering assessment of Bitcoin’s evolution as a store-of-value asset. Zhou emphasized that the flagship cryptocurrency is still a “considerable distance from being considered mature ‘digital gold’,” arguing that its ongoing price volatility creates a significant barrier for traditional financial institutions seeking a reliable store of value. The remarks, delivered from the helm of one of the world’s leading cryptocurrency exchanges, underscore the persistent gap between Bitcoin’s narrative as a sovereign hedge and its current market behavior.

    Volatility Cited as Primary Obstacle to Institutional Adoption

    Zhou elaborated that Bitcoin’s price instability remains the core impediment preventing traditional financial players from embracing the asset as a dependable reserve. “He noted that its current volatility makes it difficult for traditional financial institutions to view it as a reliable store of value,” the report detailed. This perspective carries particular weight given Bybit’s position as a major liquidity venue; the exchange’s leadership has a front-row view of institutional order flow and risk-appetite dynamics. The CEO’s commentary suggests that until Bitcoin’s volatility profile compresses meaningfully, the “digital gold” moniker remains aspirational rather than descriptive for the conservative capital allocators who dominate traditional finance.

    Stablecoins Positioned as Superior Transactional Medium

    Beyond the store-of-value debate, Zhou introduced a functional distinction between asset classes within the crypto ecosystem. He “pointed out that stablecoins might be more effective for everyday transactions, indicating a potential shift in how cryptocurrencies are utilized in commerce.” This observation aligns with growing on-chain data showing stablecoins like USDT and USDC settling trillions in annual transaction volume, far outpacing Bitcoin’s base-layer throughput for payments. The Bybit executive’s framing implies a bifurcating future: Bitcoin as a volatile, long-duration investment asset, and fiat-pegged stablecoins as the pragmatic rails for daily commerce and cross-border settlement.

    Market Structure Reflects Diverging Trader Sentiment

    The comments arrive against a backdrop of notable market structure shifts. The source highlights that “Bitcoin’s market-cap dominance has recently surged to 45%, reflecting traders’ sentiments amidst fluctuating demand for stablecoins.” This dominance metric, often viewed as a barometer of risk appetite within the digital asset sector, suggests capital is rotating toward Bitcoin even as its volatility profile remains elevated. The interplay between rising BTC dominance and stablecoin demand fluctuations creates a complex signaling environment for market participants attempting to forecast the asset’s next structural move.

    Why This Matters

    Ben Zhou’s assessment cuts to the heart of Bitcoin’s identity crisis thirteen years after its inception. While proponents champion BTC as “digital gold,” the CEO of a top-tier exchange—tasked with managing risk for millions of users—publicly disputes its current fitness for that role. This tension has direct implications for regulatory frameworks, exchange-traded product designs, and corporate treasury strategies. If the primary gateway for institutional crypto access views Bitcoin as too volatile for conservative allocation, the timeline for sovereign wealth fund and pension fund adoption extends significantly. Simultaneously, the explicit endorsement of stablecoins for payments reinforces regulatory scrutiny on that sector, as policymakers globally draft frameworks for payment stablecoins. Traders and investors must now navigate a market where the leading asset’s narrative (store of value) conflicts with its observed behavior (high-beta risk asset), while the assets actually functioning as money (stablecoins) face the steepest regulatory headwinds.

    Frequently Asked Questions

    What specific volatility metrics did Ben Zhou reference?

    The source does not cite specific volatility metrics or timeframes referenced by Zhou. His assessment appears qualitative, based on observed market behavior and institutional feedback channels available to Bybit as a major exchange operator.

    How does Bitcoin’s 45% market-cap dominance relate to Zhou’s comments?

    The 45% dominance figure is presented as concurrent context reflecting current trader sentiment. It suggests capital concentration in Bitcoin despite the volatility concerns Zhou raised, highlighting a potential disconnect between market positioning and institutional readiness.

    Did Zhou specify a timeline or conditions for Bitcoin achieving ‘digital gold’ maturity?

    No. The source indicates Zhou stated Bitcoin is a “considerable distance” from that status but does not report any specific milestones, volatility thresholds, or time horizons he associated with achieving maturity.

  • VanEck Labels Metaplanet ‘Bad,’ Calls Executive Pay a ‘Shareholder Trap’

    VanEck Labels Metaplanet ‘Bad,’ Calls Executive Pay a ‘Shareholder Trap’

    Key Highlights

    • VanEck rates Metaplanet’s executive compensation “Bad” due to a 14.7% option pool driving shareholder dilution, far exceeding the 4.0% peer average among Digital Asset Treasury companies.
    • Metaplanet’s officer exposure stands at 8.2% (10.4x the 0.8% average) and its largest individual officer position at 3.8% (5.9x the 0.6% average), with no performance conditions beyond continued service.
    • VanEck proposes canceling approximately 273 million shares added via an “Evergreen” mechanism, replacing rights with a smaller shareholder-approved plan tied to Bitcoin per fully diluted share, and adopting a written equity-grant timing policy.

    VanEck Flags Metaplanet’s Executive Compensation as “Bad”

    Global investment manager VanEck has published a comparative analysis of executive compensation across the 10 largest Digital Asset Treasury companies (DATs), placing Metaplanet in the “Bad” category. The firm’s report highlights that Metaplanet’s compensation structure adds to shareholder dilution, citing a 14.7% option pool on a fully diluted basis, officer exposure of 8.2%, and a largest individual officer position of 3.8%.

    Peer Comparison: Strategy, BitMine, and Others Rated “Good”

    By contrast, six peers — Strategy, BitMine, Hyperliquid Strategies, Sharplink, Tron, and Bit Digital — earned a “Good” rating. VanEck attributes this to fixed pools, mandatory shareholder approval for increases, and officer exposure of 1% or less. For context, Strategy maintains a fixed 8.35 million-share pool (approximately 2% of fully diluted shares) with executive exposure of 0.5%. BitMine’s pool sits at 3.2% with officer exposure around 1%. Three companies — Twenty One Capital, Strive, and Forward Industries — were placed in the “Acceptable” band due to weaker safeguards.

    Metaplanet’s Dilution Mechanics and Historical Context

    Often dubbed Japan’s MicroStrategy, Metaplanet’s compensation framework originated when the company was a struggling hotel operator and was designed to protect executive pay from dilution. After its pivot to a Bitcoin treasury strategy, the mechanism remained, allowing the executive option pool to expand as the firm issued shares to fund Bitcoin purchases. By mid‑2026 the pool had reached 319.5 million potential shares (about 20% of the company) on a fully diluted basis. On 18 August 2026 Metaplanet removed the automatic “Evergreen” mechanism but retained the enlarged pool. Then on 11 September it rolled back the conversion ratio to its pre‑September 2025 level, cutting the pool by 41% to 188.2 million shares. However, 82.8 million shares had already been issued to insiders, leaving 105.4 million potential new shares (roughly 7% of the company). Compared with the other nine DATs, Metaplanet’s 14.7% plan pool is 3.7x the 4.0% peer average, officer exposure is 10.4x the 0.8% average, and its largest officer position is 5.9x the 0.6% average. Unlike Strategy, BitMine, and Strive, Metaplanet’s rights carry no performance conditions beyond continued service.

    VanEck’s Proposed Remediation Steps

    To address these concerns, VanEck has outlined four structural changes: first, cancel approximately 273 million shares added through the adjustment mechanism; second, replace the remaining rights with a smaller shareholder‑approved plan; third, link compensation to Bitcoin per fully diluted share; and fourth, adopt a written equity‑grant timing policy. VanEck estimates that, before the recent reductions, management dilution could have absorbed roughly 20% of the economic value created through Bitcoin purchases, leaving shareholders with about 80% in its analysis.

    Market Context: Bitcoin Holdings and Stock Performance

    Metaplanet’s Bitcoin holdings have reached 43,000 BTC, valued at $3.5 billion. The company’s stock traded at ¥243.00 after a 2.10% gain in the most recent session, though it has declined nearly 50% year‑to‑date, amplifying existing investor concerns about dilution and governance.

    Why This Matters

    The VanEck report underscores a growing focus on governance quality within the Digital Asset Treasury sector. As more companies adopt Bitcoin‑centric balance sheets, the alignment of executive incentives with shareholder value becomes critical. Metaplanet’s legacy compensation structure — designed for a different business model — illustrates how unchanged mechanisms can lead to excessive dilution, eroding the very value creation that the treasury strategy aims to deliver. The peer group’s “Good” ratings demonstrate that fixed pools, shareholder approval gates, and performance‑linked grants are achievable standards. VanEck’s specific remediation proposals provide a concrete roadmap for Metaplanet and a benchmark for other DATs evaluating their own compensation frameworks.

    Frequently Asked Questions

    Why did VanEck rate Metaplanet’s executive compensation “Bad”?
    VanEck assigned the “Bad” rating because Metaplanet’s 14.7% option pool is 3.7 times the peer average, officer exposure is 10.4 times the average, and its largest officer position is 5.9 times the average. Additionally, the rights lack performance conditions beyond continued service.
    What is the “Evergreen” mechanism and what did Metaplanet do about it?
    The “Evergreen” mechanism automatically increased the option pool as the company issued shares. Metaplanet removed this automatic feature on 18 August 2026 but retained the enlarged pool that had already accumulated.
    What changes does VanEck propose for Metaplanet?
    VanEck recommends canceling roughly 273 million shares added via the adjustment mechanism, replacing the remaining rights with a smaller shareholder‑approved plan, linking compensation to Bitcoin per fully diluted share, and implementing a written equity‑grant timing policy.
  • Bitcoin Rejected at $82K: 3 Reasons Behind Sunday Pullback

    Bitcoin Rejected at $82K: 3 Reasons Behind Sunday Pullback

    Key Highlights

    • Bitcoin rallied from $75,000 to nearly $82,000 last week before stalling at resistance amid escalating Middle East tensions.
    • The U.S. State Department warned of rapid escalation between Saudi Arabia and Iran-backed Houthis, prompting travel advisories and reported high-alert status for Iranian forces.
    • Technical indicator TD Sequential flipped to a sell signal at $81,500, suggesting short-term momentum is overextended, according to analyst Ali Martinez.

    Bitcoin’s Recovery Rally Hits Geopolitical and Technical Headwinds

    Bitcoin staged a sharp recovery last week, climbing from a low of $75,000 to within striking distance of $82,000 — its highest level since early March. The rally unfolded despite a confluence of macroeconomic pressures, including fallout from the CLARITY Act legislative setback and a hawkish Federal Reserve outlook that had previously weighed on risk assets. Buyers stepped in aggressively on Friday and Saturday, erasing the post-Senate vote decline in a matter of sessions. However, the upward momentum stalled just shy of the $82,000 mark as fresh geopolitical risks emerged from the Middle East, introducing a new layer of uncertainty for global markets.

    U.S. Warns of Rapid Escalation in Saudi-Houthi Conflict

    Reports over the weekend indicated a significant deterioration in regional security. The U.S. State Department issued a statement confirming that Iranian-supported Houthis have engaged in hostilities against Saudi Arabia, including targeting civilian airports. “Iranian-supported Houthis have engaged in hostilities against Saudi Arabia, including civilian airports. This military conflict has the potential to escalate rapidly,” said the US State Department. The statement also warned Americans to “seriously reconsider travel to and through the region.” Saudi authorities reported intercepting and destroying a ballistic missile fired at Riyadh on Saturday evening, with no casualties reported. Meanwhile, BBC sources noted that energy infrastructure along the Red Sea coast was also targeted.

    Adding to the tension, the X account Daily Iran News, which commands over 500,000 followers, claimed that Iran had issued “Code 100” — its highest alert level — for all armed forces, encompassing the Islamic Revolutionary Guard Corps (IRGC), the regular Army, and security forces. In response to the deteriorating situation, former President Donald Trump reportedly cut short his weekend at Camp David to return to the White House, while Israeli Prime Minister Benjamin Netanyahu also departed the U.S. earlier than planned.

    TD Sequential Flashes Sell Signal as Momentum Stretches

    On the technical front, the rally’s exhaustion coincides with a key indicator turning bearish. Analyst Ali Martinez observed that the TD Sequential, which had flashed a buy signal when Bitcoin touched $75,000, flipped to a sell signal on Saturday evening just as the price tapped $81,500. “That suggests short-term momentum may be getting stretched, and I’m watching closely for signs that it’s time to lock in some profits,” he added. The confluence of a technical sell trigger and heightened geopolitical risk has created a dual barrier for Bitcoin’s next leg higher, with traders now monitoring whether the asset can consolidate above $80,000 or faces a pullback toward the $78,000–$79,000 support zone.

    Why This Matters

    The intersection of geopolitical instability and technical resistance underscores Bitcoin’s evolving role as a macro-sensitive asset. While often framed as a hedge against monetary debasement, Bitcoin remains acutely responsive to global risk sentiment — particularly when energy markets and major power dynamics are involved. The Saudi-Houthi escalation threatens to disrupt oil flows through the Red Sea, potentially reigniting inflation fears and complicating the Federal Reserve’s policy path. For crypto markets, the TD Sequential sell signal adds a layer of technical discipline to the narrative-driven volatility, reminding participants that rapid, news-fueled rallies often require consolidation before sustainable trend continuation. The coming days will test whether Bitcoin can decouple from traditional risk-off impulses or remains tethered to the broader geopolitical cycle.

    Frequently Asked Questions

    What caused Bitcoin’s rally to stall near $82,000?

    The rally stalled due to a combination of escalating Middle East hostilities between Saudi Arabia and Iran-backed Houthis, which triggered risk-off sentiment, and a technical sell signal from the TD Sequential indicator at $81,500, suggesting short-term momentum was overextended.

    What is the significance of the U.S. State Department’s warning?

    The State Department confirmed active hostilities involving Iranian-backed Houthis targeting Saudi civilian infrastructure and warned the conflict could escalate rapidly, advising Americans to seriously reconsider travel to the region — signaling heightened concern over a broader regional war.

    What does the TD Sequential sell signal imply for Bitcoin’s next move?

    According to analyst Ali Martinez, the sell signal indicates short-term momentum is stretched, increasing the probability of a consolidation or pullback. He noted he is watching for signs to lock in profits, implying a cautious near-term outlook unless price action invalidates the signal.

  • Ethereum Revenue Gap Widens as Robinhood Chain Expands

    Ethereum Revenue Gap Widens as Robinhood Chain Expands

    Key Highlights

    • Robinhood Chain generated $4.5 million in daily transaction fees on September 3, while Ethereum received only $400 for data posting and proof costs.
    • Digital Asset analysis reveals a widening revenue gap where Layer 2 fee revenue largely remains within the L2 ecosystem rather than flowing to Ethereum’s base layer.
    • Traders are monitoring Ethereum’s key support levels and its strategic response as Layer 2 growth challenges the traditional L1 revenue model.

    Robinhood Chain Fee Surge Exposes Ethereum Revenue Disparity

    A new analysis by Digital Asset has thrown a spotlight on the evolving economic relationship between Ethereum and its Layer 2 scaling solutions. On September 3, Robinhood Chain — the Layer 2 network launched by the retail brokerage’s crypto division — collected an estimated $4.5 million in daily transaction fees. In stark contrast, the Ethereum mainnet received only $400 for data posting and proof verification costs associated with that same activity. The finding underscores a structural shift in where value accrues within the modular blockchain stack.

    Layer 2 Economics Decouple from Base Layer Revenue

    The data reveals a growing divergence: as Layer 2 networks like Robinhood Chain, Arbitrum, Optimism, and Base attract higher transaction volumes, the bulk of fee revenue is captured by the L2 sequencers and their respective ecosystems. Ethereum’s role has increasingly narrowed to that of a settlement and data availability layer, compensated only for the marginal cost of calldata and zero-knowledge proof verification. This dynamic raises fundamental questions about the long-term sustainability of Ethereum’s revenue model, which historically relied on execution fees burned via EIP-1559 to create deflationary pressure on ETH supply.

    Market Context: Ethereum Navigates Technical Resistance

    The revenue analysis arrives as Ethereum’s price action tests critical resistance levels amid mixed macro signals. Traders are weighing the implications of diminishing L1 fee capture against the network’s broader value proposition as a neutral settlement layer. While total value locked across Ethereum Layer 2s continues to climb — surpassing $40 billion across major rollups — the native token’s fee-burn mechanism has seen reduced activity during periods of low L1 congestion. Analysts note that unless Ethereum implements protocol-level changes such as EIP-7781 (proposed slot time reduction) or increases blob throughput via EIP-4844 expansions, the revenue gap may widen further.

    Why This Matters

    The revenue disparity highlights a pivotal tension in Ethereum’s rollup-centric roadmap. The network’s long-term thesis — that scaling through Layer 2s would expand total blockspace demand and ultimately benefit ETH holders through increased settlement demand — is being tested in real time. If L2s successfully internalize sequencing revenue while contributing minimally to base-layer fees, Ethereum may need to explore alternative value capture mechanisms, such as native staking yield enhancements, MEV redistribution, or protocol-owned liquidity strategies. Meanwhile, Robinhood Chain’s fee performance signals strong retail adoption of its low-cost environment, potentially accelerating the onboarding of mainstream users into self-custodied DeFi — a development that could expand the total addressable market for onchain applications even as the revenue split evolves.

    Frequently Asked Questions

    How much did Robinhood Chain earn in fees on September 3 compared to Ethereum?
    Robinhood Chain collected approximately $4.5 million in daily transaction fees, while Ethereum received only $400 for data posting and proof verification costs related to that L2 activity.
    Why does Ethereum receive so little revenue from Layer 2 transactions?
    Ethereum’s role in the modular stack is limited to data availability and settlement. L2 sequencers batch transactions and post only compressed calldata or validity proofs to Ethereum, paying base-layer fees only for that marginal footprint — not for the execution fees users pay on the L2.
    What are traders watching regarding Ethereum’s response to this trend?
    Market participants are monitoring Ethereum’s key technical support levels, upcoming protocol upgrades (such as increased blob capacity and potential slot time reductions), and whether the network can adapt its value capture model to remain economically sustainable as L2 activity grows.