Tag: Digital asset regulation

  • Democrats Killed the Clarity Act

    Democrats Killed the Clarity Act

    Key Highlights:

    • No Senate Democrat voted last week to advance the Clarity Act, according to the source.
    • The legislation would have created rules for digital assets and aimed to reduce transaction costs for everyday Americans.
    • The source argues that Democratic tax proposals would increase costs for overtime, tips and Social Security recipients.

    Clarity Act stalls after Senate Democrats oppose advancement

    The Clarity Act failed to move forward last week after not a single Senate Democrat voted to advance the digital-asset legislation, according to the source. The bill was designed to establish clearer rules for digital assets and help lower transaction costs for everyday Americans.

    The vote came amid continued Democratic rhetoric about household costs and affordability. The source argues that Democrats’ opposition to the Clarity Act conflicted with those priorities and prevented the legislation from progressing.

    Read more: How months of work on the Clarity Act all fell apart

    Debate centers on household costs and taxes

    The source frames the policy debate through the impact that legislation could have on working families. It asks, Will this help single moms like the one who raised me? The argument is that policies affecting digital-asset transactions and taxes should be assessed by their effect on Americans trying to retain more of their income.

    According to the source, Democrats have long said they aim to support Americans in these circumstances, but their votes in Washington have repeatedly been portrayed as taking money from hardworking families. It specifically claims that Democrats voted to raise taxes on overtime, tips and Social Security.

    The source further states that, if Democrats’ proposals prevailed, Americans could pay hundreds of dollars more per month in taxes. Those claims are presented as part of a broader argument that voters want to keep more of their own money and that lawmakers should prioritize affordability in decisions involving taxation and digital-asset regulation.

    Why This Matters

    The Clarity Act vote highlights the continuing political dispute over how digital assets should be regulated and whether clearer rules could reduce transaction costs for consumers. The legislation’s failure to advance also shows that disagreements over taxes, affordability and financial regulation remain central to the Senate debate.

    Frequently Asked Questions

    What is the Clarity Act?

    The Clarity Act is legislation intended to establish rules for digital assets and help reduce transaction costs for everyday Americans.

    What happened to the bill in the Senate?

    According to the source, not a single Senate Democrat voted to advance the Clarity Act last week, and the bill did not move forward.

    Which tax areas does the source say are affected?

    The source says Democrats voted to raise taxes on overtime, tips and Social Security, and argues that Americans could pay hundreds of dollars more each month if Democrats’ proposals prevailed.
  • Michael Saylor Issues Statement Following Recent Developments

    Michael Saylor Issues Statement Following Recent Developments

    Key Highlights

    • Strategy founder Michael Saylor unveiled a comprehensive policy framework advocating for Bitcoin’s integration into banking and insurance systems, including custody services and balance-sheet adoption.
    • Saylor proposes a “digital rights declaration” establishing five fundamental rights for digital asset creation, issuance, holding, transfer, and use, alongside simplified disclosure rules scaled to project size.
    • The framework calls for regulatory differentiation between client custody, Bitcoin-backed lending, and bank proprietary positions, while criticizing the Basel 1,250% risk weighting and the Clarity Act’s restrictive approach.

    Saylor Outlines Five-Pillar Digital Rights Framework

    Strategy founder and Executive Chairman Michael Saylor has published a sweeping policy framework for the digital economy, arguing that Bitcoin should be more broadly integrated into the banking and insurance systems. In his published article, Saylor stated that artificial intelligence will significantly increase the productivity of individuals and businesses, and that the digital asset era needs a “digital rights declaration.” According to Saylor, individuals and companies should have five fundamental rights regarding the creation, issuance, holding, transfer, and use of digital assets.

    Simplifying Issuance and Enabling Digital Dollar Competition

    Saylor, who advocates for simplifying the rules regarding digital asset issuance, said that applying different disclosure obligations based on project size could lower the cost of accessing finance for companies. Saylor suggested that this approach could help approximately 10 million new companies access capital. Saylor also stated that a clear regulatory path should be created to allow banks, fintech companies, and technology platforms to issue digital dollar products. He argued that organizations issuing digital dollars should also be able to compete on terms of yield.

    Bitcoin as “Digital Capital”: Banking and Insurance Integration

    Saylor, who described Bitcoin as “digital capital,” called for banks to be allowed to offer Bitcoin custody services and provide Bitcoin-backed loans. He also said that a viable regulatory framework should be created so that insurance companies can incorporate Bitcoin into their balance sheets and product designs. Saylor argued that the 1,250% risk weighting applied to some crypto asset risks under Basel regulations is too strict. He stated that regulations should differentiate between client-based custody services, Bitcoin-backed loans, and banks’ own Bitcoin positions, adding that bank adoption of Bitcoin could be a significant catalyst for the sector’s growth.

    Tokenized Securities, Privacy, and the Clarity Act Critique

    Saylor, also touching upon tokenized securities, said that simply moving existing securities onto the blockchain is not enough. He argued that investors should be able to store their assets directly, transfer them freely, and choose different custody or lending service providers. Regarding privacy, Saylor stated that ordinary and legitimate transactions under $10,000 should not be automatically reported to government agencies simply because they involve the transfer of money or digital assets. According to Saylor, the U.S. Securities and Exchange Commission (SEC), the Commodity Futures Trading Commission (CFTC), the U.S. Treasury Department, banking regulators, and the White House will play a key role in advancing reforms over the next two years. Saylor, who also criticized the Clarity Act, argued that the regulation placed too much emphasis on restrictions.

    Why This Matters

    Saylor’s framework arrives amid intensifying debate over U.S. digital asset legislation, including the Financial Innovation and Technology for the 21st Century Act (FIT21) and stablecoin bills advancing in Congress. His proposals directly address three structural friction points: the Basel Committee’s punitive 1,250% risk weight for Group 2 cryptoassets, which discourages bank balance-sheet engagement; the lack of a clear charter for insurers to hold Bitcoin as a reserve asset; and the absence of a scaled disclosure regime that would lower compliance costs for smaller token issuers. By explicitly naming the SEC, CFTC, Treasury, federal banking agencies, and the White House as the entities that must drive reform over the next two years, Saylor is mapping a lobbying and legislative roadmap that aligns with Strategy’s corporate strategy of accumulating Bitcoin while advocating for the institutional infrastructure to support it. The critique of the Clarity Act signals industry concern that current legislative drafts may over-index on enforcement tools at the expense of market-making clarity.

    Frequently Asked Questions

    What are the five fundamental digital rights Saylor proposes?

    Saylor outlines rights covering the creation, issuance, holding, transfer, and use of digital assets, framed as a “digital rights declaration” for individuals and companies.

    How does Saylor propose to change Basel capital rules for Bitcoin?

    He argues the current 1,250% risk weighting is excessive and urges regulators to differentiate between client custody services, Bitcoin-backed loans, and banks’ own proprietary Bitcoin positions.

    Which U.S. agencies does Saylor identify as critical for implementing reforms?

    Saylor names the SEC, CFTC, U.S. Treasury Department, federal banking regulators, and the White House as the key entities that will drive policy changes over the next two years.

  • Federal Reserve Proposes Stablecoin Rules Under the GENIUS Act

    Federal Reserve Proposes Stablecoin Rules Under the GENIUS Act

    Key Highlights

    • The Federal Reserve Board proposed two rules on September 24 to implement the GENIUS Act, requiring payment stablecoin issuers to fully back tokens with permissible reserve assets and meet new capital and risk-management standards.
    • The first proposal mandates full reserve backing using short-term Treasury bills and other high-quality liquid assets, while the second creates a tailored application process for Board-supervised banks seeking to issue payment stablecoins.
    • A 60-day public comment period begins upon publication in the Federal Register, marking the central bank’s most concrete step yet to supervise a stablecoin market that has become core digital-asset infrastructure.

    Federal Reserve Unveils Dual Rulemaking to Operationalize GENIUS Act Stablecoin Framework

    The Federal Reserve Board took its most decisive regulatory action to date on payment stablecoins on September 24, releasing two proposed rules at 2:30 p.m. Eastern time that translate the Guiding and Establishing National Innovation for U.S. Stablecoins Act (GENIUS Act) into enforceable supervisory standards. The proposals provide banks and nonbank issuers with the first detailed look at how the central bank intends to oversee a market that has evolved into critical plumbing for digital-asset transactions. By setting explicit reserve composition, capital adequacy, and application requirements, the Fed aims to establish a clear legal pathway for depository institutions to enter the dollar-pegged token business while maintaining financial stability safeguards.

    Full Reserve Backing and Standardized Capital Requirements

    The first proposal targets Board-supervised payment stablecoin issuers directly, mandating that reserve assets match or exceed the value of outstanding coins at all times. Permissible reserves are limited to short-term Treasury bills and certain other high-quality, liquid assets, a design intended to eliminate credit and liquidity mismatches that have plagued previous stablecoin models. In addition to asset composition rules, the proposal imposes standardized capital requirements calibrated to the credit and operational risks inherent in stablecoin issuance and redemption activities. Risk-management standards prescribed by the GENIUS Act are also codified, covering governance, cybersecurity, and third-party dependency oversight. The same rulemaking extends to firms that safekeep reserve assets on behalf of issuers, establishing custodial standards, and clarifies the range of permissible stablecoin-related activities for Board-supervised banking organizations.

    Tailored Application Pathway for Depository Institutions

    The second proposal addresses a persistent industry demand: a transparent, predictable process for banks that wish to issue payment stablecoins. Applicants must submit a comprehensive business plan, detailed financial projections, and supporting documentation demonstrating compliance with the reserve, capital, and risk-management frameworks. The draft rule also establishes procedural protections, including a defined process for administrative appeals, hearings, and final determinations, giving institutions greater certainty about supervisory timelines and outcomes. By formalizing this pathway, the Fed signals that stablecoin issuance is a permissible banking activity subject to the same rigorous entry standards as other novel financial products.

    Why This Matters: Regulatory Convergence and Global Competitiveness

    The Federal Reserve’s move does not occur in isolation. It coincides with parallel legislative efforts such as the CLARITY Act, which seeks to resolve market-structure oversight gaps for digital assets more broadly, and with an international regulatory tightening cycle. In Europe, the Markets in Crypto-Assets Regulation (MiCA) has already imposed stringent reserve, governance, and disclosure requirements on stablecoin issuers, while the Bank of England and other central banks are advancing their own supervisory regimes. The Fed’s proposals therefore serve a dual purpose: they domesticize the GENIUS Act’s federal framework for issuers and reserve custodians under the Board’s jurisdiction, and they position U.S. regulated entities to compete on a level playing field with foreign counterparts operating under comparable or stricter regimes. The 60-day comment period, which begins upon Federal Register publication, will be closely watched by banks, fintechs, and stablecoin incumbents such as Circle and Paxos, all of which must assess the operational and economic feasibility of compliance before the rules are finalized.

    Frequently Asked Questions

    What assets qualify as permissible reserves under the Fed’s first proposal?

    Permissible reserves include short-term Treasury bills and certain other high-quality, liquid assets. The proposal explicitly requires that the value of these reserves fully covers outstanding payment stablecoins at all times.

    How does the application process work for banks that want to issue payment stablecoins? Under the second proposal, Board-supervised banks must submit a business plan, financial information, and other required documents. The rule establishes a process for appeals, hearings, and final determinations on applications.

    When does the public comment period end?

    The comment period closes 60 days after both proposals are published in the Federal Register. The exact calendar date will depend on the publication date.

  • SEC Commissioner Hester Peirce to Step Down October 2

    SEC Commissioner Hester Peirce to Step Down October 2

    Key Highlights

    • SEC Commissioner Hester Peirce, known as “Crypto Mom,” resigned effective October 2, 2025, leaving the commission with only two sitting members: Chairman Paul Atkins and Commissioner Mark Uyeda.
    • Peirce’s departure removes the leader of the SEC’s Crypto Task Force at a critical juncture as the agency advances token-classification FAQs and proposed Regulation Crypto Assets.
    • The White House has not yet named a successor, and confirmation timelines typically span six to twelve months, creating an extended leadership vacuum at the five-member commission.

    Peirce Announces Departure After Eight-Year Tenure

    SEC Commissioner Hester Peirce announced her resignation on September 25, posting her resignation letter on X with the caption “T minus 7,” a countdown to her final day at the agency on October 2. Peirce, widely known as “Crypto Mom” for her persistent push for clearer, rules-based digital-asset regulation, has served on the commission since January 2018. Her departure will leave the SEC with just two sitting commissioners, Chairman Paul Atkins and Commissioner Mark Uyeda, and no successor yet named by the White House.

    Eight Years of Dissent and Crypto Task Force Leadership

    Peirce spent more than eight years as the commission’s most consistent advocate for written crypto rules, frequently dissenting from what she characterized as enforcement-first decisions, including the agency’s earlier refusals to approve spot Bitcoin exchange-traded funds. In January 2025 she took charge of the Crypto Task Force, the group behind much of the SEC’s digital-asset policy work, including its warnings on securities risk in crypto yield vaults and onchain lending. Her second term expired on June 5, 2025, but SEC rules allow a commissioner to serve up to about 18 months past a term’s end when no replacement has been confirmed.

    Resignation Letter Emphasizes Regulatory Philosophy

    In the letter addressed to President Trump, Peirce called her tenure “the honor of my professional lifetime” and wrote that “maximizing people’s freedom to choose what is best for themselves and their families within sensible regulatory parameters designed to give them the confidence to transact with others is a delicate and vitally important task for the regulator.” She said she leaves confident that the agency’s work will continue under Atkins and Uyeda.

    A Two-Member Commission and the Road Ahead

    The resignation reduces the commission to two Republican members and removes the Crypto Task Force’s leader at a moment when the agency’s crypto agenda is running at full speed. The agency already carried a vacant seat after Democratic Commissioner Caroline Crenshaw departed in January, so Peirce’s exit leaves two empty spots on the five-member commission. The announcement landed the same day the SEC published new token-classification FAQs, part of a rulemaking push that has included its proposed Regulation Crypto Assets. The White House has not named a successor, and confirmation timelines can run six to twelve months. Peirce is expected to join Regent University School of Law in Virginia as an associate professor in November.

    Why This Matters

    Peirce’s departure creates significant uncertainty for the SEC’s digital-asset regulatory agenda at a pivotal moment. With only two commissioners remaining, the commission lacks a quorum for certain rulemaking actions, potentially slowing the progress of proposed Regulation Crypto Assets and other pending initiatives. The Crypto Task Force, which Peirce led since January 2025, has been instrumental in shaping the agency’s approach to token classification, yield products, and lending protocols. Her absence may alter the trajectory of enforcement priorities and rulemaking timelines. The extended vacancy period—potentially six to twelve months before a successor is confirmed—means the SEC will operate with a skeletal leadership structure during a period of intense industry scrutiny and legislative activity around digital assets. Market participants should monitor White House nomination signals and Senate Banking Committee scheduling for clues about the agency’s future direction.

    Frequently Asked Questions

    When does Hester Peirce’s resignation take effect?

    Peirce’s resignation takes effect on October 2, 2025, as indicated by her “T minus 7” countdown posted on September 25.

    Who will lead the SEC’s Crypto Task Force after Peirce’s departure?

    The source material does not specify a successor for the Crypto Task Force leadership role. With only Chairman Paul Atkins and Commissioner Mark Uyeda remaining, the task force’s future leadership structure remains uncertain.

    What is Hester Peirce’s next professional role?

    Peirce is expected to join Regent University School of Law in Virginia as an associate professor starting in November 2025.

  • Democrats ‘chose visceral hatred for’ Donald Trump Over crypto Clarity Act, Lummis Says

    Democrats ‘chose visceral hatred for’ Donald Trump Over crypto Clarity Act, Lummis Says

    Key Highlights

    • Senator Cynthia Lummis blamed Senate Democrats for blocking a procedural vote on bipartisan crypto market structure legislation last week, calling the outcome “dismayed, dumbfounded and saddened.”
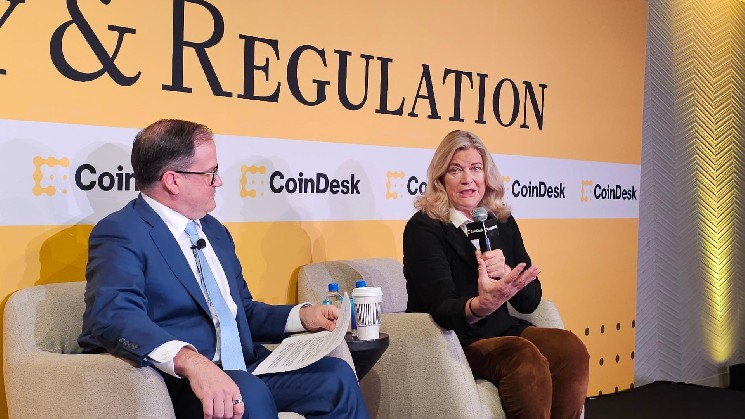
    • Speaking at CoinDesk’s Policy & Regulation event, Lummis alleged Democrats prioritized opposition to President Donald Trump over passing the bill, which had grown from 300 to over 600 pages after Democratic requests for provisions such as bankruptcy protections.
    • The legislation was the product of cross-party negotiations, but failed to advance before the midterm election cycle, leaving digital asset regulatory clarity in limbo.

    Lummis Points Finger at Democratic Opposition to Trump

    Senator Cynthia Lummis (R-Wyo.) delivered a sharp rebuke of her Democratic colleagues on Tuesday, arguing that partisan animosity toward President Donald Trump derailed a carefully negotiated crypto market structure bill that had achieved rare bipartisan consensus. Addressing attendees at CoinDesk’s Policy & Regulation event in Washington, D.C., Lummis said she was “dismayed, dumbfounded and saddened” that the Senate could not advance a key procedural vote on the measure last week.

    The Wyoming Republican framed the failure as a deliberate choice by Democrats to deny the incoming administration a legislative win ahead of the midterm elections. The problem was, as I see it, Democrats hate President [Donald] Trump more than they like good policy, and the way I see it is they chose their visceral hatred for President Trump and denied the opportunity to pass important policy legislation before a midterm, Lummis said. They chose that … pin it on the Democrats.

    Bill Expanded Significantly After Democratic Input

    Lummis emphasized that the legislation was not a partisan product but the result of extensive negotiations between members of both parties. She noted the bill had ballooned from roughly 300 pages to more than 600 after Democrats requested additional provisions addressing issues such as bankruptcy protections, among other items. Those concessions, she argued, demonstrated Republican willingness to accommodate Democratic priorities, only for the bill to stall at the procedural stage.

    The stalled measure represents the most comprehensive attempt to date to establish a clear regulatory framework for digital asset markets in the United States. Its failure to advance leaves critical questions unresolved regarding the classification of tokens, the roles of the SEC and CFTC, consumer protections, and the treatment of digital assets in bankruptcy proceedings — issues the expanded text had sought to address.

    Why This Matters

    The collapse of the bipartisan crypto market structure bill underscores how broader political dynamics — particularly the polarized response to President Trump — can override substantive policy agreement on emerging technologies. With the legislation now stalled, regulatory uncertainty continues to hamper the digital asset industry, driving activity offshore and complicating compliance for U.S.-based firms. The next opportunity for comprehensive crypto legislation will likely depend on the composition of the next Congress and whether either party chooses to revive the negotiated text or pursue a new approach. For now, the SEC and CFTC will continue to rely on existing enforcement authorities, and market participants will operate without the statutory clarity the bill was designed to provide.

    Frequently Asked Questions

    What specific provisions did Democrats request that expanded the bill?

    According to Senator Lummis, Democrats asked for provisions addressing bankruptcy protections, among other items, which caused the bill to grow from roughly 300 pages to over 600 pages.

    Was the crypto market structure bill a partisan or bipartisan effort?

    Lummis described the bill as a bipartisan product resulting from negotiations between members of both parties, though it ultimately failed to advance due to what she characterized as Democratic opposition to President Trump.

    What happens next for crypto regulation in the Senate?

    With the procedural vote blocked before the midterm elections, the legislation is effectively stalled. Future progress will depend on the next Congress’s composition and priorities, and whether lawmakers choose to revive this negotiated text or start anew.

  • Clarity Act Replaced: What the Bill Contained and What Comes Next

    Clarity Act Replaced: What the Bill Contained and What Comes Next

    Key Highlights

    • The Clarity Act would have granted the Commodity Futures Trading Commission (CFTC) full supervisory authority over crypto commodity spot markets, including Bitcoin and Ethereum trading.
    • The legislation aimed to define regulatory buckets for blockchain-native assets, curb illicit finance, and provide limited legal protections for decentralized finance (DeFi) software developers.
    • With the bill stalled, the Securities and Exchange Commission (SEC) is moving to fill the regulatory vacuum, signaling continued enforcement-focused oversight of the digital asset sector.

    The Clarity Act’s Regulatory Blueprint

    The Clarity Act represented a comprehensive attempt to resolve the United States’ fragmented approach to digital asset regulation by formally designating the Commodity Futures Trading Commission as the primary supervisor of crypto commodity spot markets. Since Bitcoin (BTC) at $81,656.52 and Ethereum’s ether (ETH) at $2,643.82 were classified as commodities, the bulk of cryptocurrency trading activity occurs in spot markets that have operated without a dedicated, hands-on federal regulator—except in cases involving market manipulation. The bill would have elevated the CFTC, the SEC’s sister agency overseeing derivatives, to direct supervisory authority over these markets, addressing a structural gap unique to the American regulatory framework where securities and derivatives oversight remain separated across independent agencies.

    Defining Asset Categories and Developer Protections

    Beyond market structure, the legislation sought to establish clear taxonomic buckets for blockchain-native assets, assigning each to the appropriate regulatory regime. The bill also incorporated provisions targeting illicit finance risks and, in a notably contentious measure, proposed limited legal shields for software developers building decentralized finance protocols. These protections aimed to prevent developers from facing prosecution based solely on how third parties utilize their open-source code—a provision that sparked significant debate across industry and policy circles.

    Legislative Failure and the Enforcement Vacuum

    The Clarity Act ultimately stalled due to provisions unrelated to its core regulatory mission, leaving a policy void that the SEC has moved quickly to occupy. Rather than waiting for congressional action, the securities regulator has intensified its enforcement posture, leveraging existing securities laws to assert jurisdiction over a broad swath of digital asset activity. This development effectively replaces a potential legislative framework—designed with industry input and clear statutory boundaries—with a case-by-case enforcement approach that many market participants argue creates greater uncertainty for compliant actors.

    Why This Matters

    The collapse of the Clarity Act underscores the persistent inability of Congress to pass bespoke digital asset legislation, leaving regulatory authority contested between the SEC and CFTC. The U.S. remains an outlier among major economies in maintaining separate securities and derivatives regulators, a structure that complicates the classification of hybrid assets like cryptocurrencies. In the absence of statutory clarity, the SEC’s enforcement-first strategy is likely to continue shaping market behavior, potentially driving activity offshore or into less transparent venues while courts adjudicate the boundaries of the agency’s jurisdiction on a case-by-case basis.

    Frequently Asked Questions

    What would the Clarity Act have changed for crypto regulation?
    The bill would have granted the CFTC full supervisory powers over crypto commodity spot markets—where Bitcoin and Ethereum primarily trade—while creating defined regulatory categories for blockchain assets, adding anti-illicit finance measures, and offering limited liability protections for DeFi software developers.
    Why did the legislation fail?
    The bill was derailed by unrelated provisions that had little to do with its primary regulatory objectives, though the source does not specify which particular sections caused the breakdown.
    How is the SEC responding to the legislative vacuum?
    The SEC is actively using its existing enforcement authority to police the digital asset sector, effectively filling the regulatory gap left by the Clarity Act’s failure through litigation and regulatory actions rather than new rulemaking.
  • NYDFS’s Asrow Addresses Stablecoin Regulation at Stablecon

    NYDFS’s Asrow Addresses Stablecoin Regulation at Stablecon

    At the recent Stablecon conference, New York Department of Financial Services (NYDFS) Acting Superintendent Asrow emphasized the critical role of inter-agency collaboration in shaping effective stablecoin regulation. The remarks, delivered on September 16, 2026, reinforce New York’s position as a pioneer in digital asset oversight, building on more than a decade of experience regulating virtual currencies.

    Regulatory Leadership and Collaborative Approach

    The stablecoin sector continues to expand as digital assets transform traditional financial infrastructure. Acting Superintendent Asrow’s address at Stablecon signals NYDFS’s commitment to evolving its regulatory framework through coordination with fellow regulators. This strategy aims to create a resilient environment that encourages responsible innovation while maintaining rigorous consumer protections—a proactive posture that contrasts with the more tentative regulatory timelines observed in other jurisdictions.

    Key Takeaways

    • NYDFS is spearheading stablecoin regulatory development.
    • Acting Superintendent Asrow presented at Stablecon on September 16, 2026.
    • The discussion centered on the necessity of collaboration among regulatory bodies.
    • New York leverages over ten years of virtual currency supervisory experience.
    • The framework prioritizes user safety alongside innovation enablement.

    Market Context and Implications

    The broader cryptocurrency market is currently navigating mixed momentum across various digital assets. In this environment, regulatory clarity from influential bodies like NYDFS plays a pivotal role in shaping trader sentiment and industry dynamics. As these frameworks mature, they are expected to bolster market confidence and accelerate stablecoin adoption across diverse platforms.

    NYDFS regulates financial services and products in New York, including virtual currencies. Its stablecoin framework is widely regarded as a benchmark for other jurisdictions, reflecting the state’s dual mandate to advance the digital asset ecosystem and safeguard consumers.

    Forward-Looking Considerations

    Market participants should closely monitor how NYDFS’s evolving regulatory model influences approaches in other regions. As other regulators observe New York’s proactive measures, they may adopt comparable frameworks, potentially driving increased interest and investment in stablecoins and reshaping the market landscape in the months ahead.

  • Final CLARITY Act Draft Ends Ripple Supply Debate, Attorney Says

    Final CLARITY Act Draft Ends Ripple Supply Debate, Attorney Says

    Attorney Bill Morgan stated that the newly released final text of the CLARITY Act resolves a long-standing debate in the cryptocurrency sector. He asserted that XRP will be classified as a commodity in secondary markets irrespective of the volume of supply Ripple continues to hold.

    “Deal with it Bitcoin maxis,”

    Morgan wrote, referencing critics who have long argued that Ripple’s substantial XRP holdings should disqualify the token from commodity status.

    What the Final Draft Actually Does

    Senate Republicans released the finalized 635-page CLARITY Act text Sunday night ahead of Tuesday’s cloture vote, describing it as their “last, best and final” offer to Democrats. The draft reflects 126 changes requested by Democrats during negotiations.

    Ethics Provisions and Divestiture Requirements

    The most significant update centers on ethics provisions backed by President Trump. Federal officials covered under the bill would be required to either divest significant digital asset holdings or place them into a qualified blind trust.

    State attorneys general would gain authority to enforce bans on officials issuing, sponsoring, or holding major stakes in digital assets. Exchanges would be barred from listing any digital asset issued in violation of those rules. Penalties for violations would run 20% of the transaction value or $500,000, whichever is greater, with the rules taking effect within 360 days of enactment.

    Stablecoin Oversight and Circuit Breaker Mechanism

    Other changes include a new “circuit breaker” mechanism giving federal regulators, specifically the Treasury, authority to intervene on stablecoin yield if community banks experience significant deposit flight into stablecoins.

    Narrowed Protections and Conflict-of-Interest Rules

    The Blockchain Regulatory Certainty Act’s protections were narrowed to cover only the Bank Secrecy Act and civil enforcement, removing language that previously extended protections to certain criminal cases.

    The bill also adds tighter restrictions on conflicts of interest and affiliate trading involving digital commodity exchanges, brokers, and dealers. It clarifies that state consumer protection laws remain fully applicable and that developer protections do not exempt anyone from derivatives law or affect prediction markets.

  • CLARITY Act Seeks Emergency Meeting With Senate Democrats Today Before Sept. 15 Vote

    CLARITY Act Seeks Emergency Meeting With Senate Democrats Today Before Sept. 15 Vote

    Senate Democrats are scheduled to convene on Sunday as pressure mounts ahead of a critical vote on the CLARITY Act. According to individuals familiar with the discussions, Senate Minority Leader Chuck Schumer initiated the caucus meeting to align members on strategy.

    Democrats Navigate Internal Divisions on CLARITY Act

    The gathering comes at a pivotal moment for the legislation, which has sparked debate within the Democratic ranks over its regulatory framework for digital assets. Lawmakers are weighing concerns from constituent groups, industry stakeholders, and progressive advocates who argue the bill lacks sufficient consumer protections.

    Schumer’s decision to call the meeting signals the leadership’s urgency to secure a unified position before the measure reaches the floor. The closed-door session will allow senators to address amendments, procedural tactics, and the political ramifications of supporting or opposing the act in an election year.

    While the exact agenda remains confidential, sources indicate the discussion will focus on bridging differences between members who view the legislation as a necessary step toward market clarity and those demanding stronger safeguards against fraud and market manipulation.

  • xLiquida Announces Plans for Tokenized UK Government Bonds

    xLiquida Announces Plans for Tokenized UK Government Bonds

    xLiquida Announces Tokenized UK Government Bonds Ahead of Mainnet Launch

    Blockchain platform xLiquida is generating significant attention with its announcement to launch tokenized UK government bonds, marking a pivotal milestone on the road to its mainnet debut. The development, highlighted by prominent CryptoTwitter commentator @arbitrum, underscores the platform’s ambition to bridge traditional finance with the blockchain ecosystem. By introducing these tokenized instruments, xLiquida aims to attract new users and investors while making crypto-based financial products more accessible.

    Platform Advances Programmable Economy Vision

    While the broader crypto market contends with mixed signals, xLiquida’s strategic pivot toward tokenizing UK government bonds stands out as a notable exception. The move demonstrates the platform’s commitment to innovative financial solutions and its goal of creating a more programmable economy. This initiative has the potential to draw significant interest from institutional investors seeking exposure to blockchain-based traditional assets. Market participants are monitoring the rollout closely, particularly against the backdrop of ongoing regulatory discussions surrounding digital assets.

    Key Developments at a Glance

    • xLiquida is preparing for its mainnet launch.
    • Tokenized UK government bonds are slated for imminent introduction.
    • The initiative aims to enhance the programmable economy.
    • The move could attract traditional finance participants to the crypto sector.
    • The announcement aligns with evolving regulatory framework discussions.

    Market Context and Token Metrics

    Currently, xLiquida reports no trading volume, suggesting the market is still digesting the news. The absence of significant price movement reflects the cautious sentiment prevalent across the wider cryptocurrency landscape. However, the announcement of tokenized government bonds could catalyze increased trading activity in the future, representing a potential inflection point for the platform.

    xLiquida’s core focus remains on bridging traditional finance with blockchain technology through innovative financial products. The introduction of tokenized government bonds aligns with broader financial sector trends where digital assets continue gaining traction. As regulatory bodies increase scrutiny of such developments, compliance will be crucial for the platform’s long-term success.

    What Traders and Investors Are Monitoring

    Market participants should track xLiquida’s mainnet launch timeline and the subsequent performance of the tokenized bond offerings. The potential for heightened institutional interest could trigger meaningful shifts in market dynamics. Additionally, monitoring regulatory developments will be essential, as evolving frameworks could significantly impact the broader acceptance and adoption of tokenized assets within traditional finance.