Category: Coins

Digital assets, cryptocurrencies, blockchain, and currency news.

  • Kraken Parent Payward Bets Billions on Becoming Financial Infrastructure, Not Just a Crypto Exchange

    Kraken Parent Payward Bets Billions on Becoming Financial Infrastructure, Not Just a Crypto Exchange

    Key Highlights

    • Payward, the parent company of Kraken, is pursuing a regulated infrastructure strategy rather than consolidating all products under a single Kraken-branded exchange platform.
    • Architect Partners describes this as an “Everything Financial Infrastructure” model designed to power financial products across multiple brands, customer segments, and partner channels.
    • Kraken averaged approximately $1.1 billion in daily spot trading volume during the first four months of 2026, while Binance held 38.7% of top-10 centralized exchange spot volume in Q2 and Coinbase reported an 8.6% share of overall crypto trading volume in Q1.

    Payward Charts Infrastructure-First Path Distinct From Coinbase Model

    Digital-asset investment bank Architect Partners reports that Payward, the holding company behind the Kraken cryptocurrency exchange, is pursuing a fundamentally different business architecture than its primary U.S. rival, Coinbase. Rather than concentrating all products and services inside a single Kraken-branded platform, Payward is building regulated infrastructure capable of supporting multiple brands and serving outside financial institutions.

    According to Architect Partners, this approach represents a distinct aggregation layer for the digital-asset economy. “Payward appears to be choosing a different aggregation layer: the regulated infrastructure stack that can power financial products across multiple brands, customer segments, and partner channels,” the firm said. “In our view, Payward is helping define the next evolution beyond the ‘Everything Exchange’: an ‘Everything Financial Infrastructure’ model.”

    Market Position and Competitive Landscape

    The infrastructure strategy unfolds against a backdrop of significant market-share disparities among centralized exchanges. CoinGecko data indicates that Kraken averaged about $1.1 billion in daily spot trading volume during the first four months of 2026. By comparison, Binance controlled 38.7% of spot trading volume across the top-10 centralized exchanges in the second quarter of 2026, while Coinbase reported an 8.6% share of overall cryptocurrency trading volume in the first quarter.

    These figures underscore the scale challenge Kraken faces as a standalone exchange venue. Payward’s response, according to the Architect Partners analysis, is to monetize the underlying technology and regulatory licenses across a broader ecosystem of partners and brands rather than relying exclusively on direct retail exchange revenue.

    Legacy Finance Constraints Drive Blockchain Infrastructure Thesis

    Payward’s thesis centers on structural inefficiencies in the traditional financial system. The company argues that decades-old technology and market conventions continue to constrain legacy finance. Securities settlement remains slow, markets close overnight and on weekends, and banks, brokers, custodians, and clearing houses maintain separate records that require costly reconciliation.

    Kraken co-CEO Arjun Sethi articulated the cost of these boundaries. “Each boundary creates another intermediary, delay and fee,” Sethi said. In his view, blockchain-based systems offer an alternative by enabling assets to function simultaneously as investments, collateral, and programmable instruments on shared infrastructure.

    Why This Matters

    The divergence between Payward’s infrastructure-first model and Coinbase’s platform-centric approach highlights a strategic fork in the maturation of the digital-asset industry. As regulatory clarity improves in major jurisdictions, the value proposition may shift from operating a single branded exchange to providing the compliant rails—licensing, custody, settlement, and programmable asset logic—that allow traditional financial institutions, fintechs, and other brands to embed digital-asset functionality natively. If successful, Payward could generate revenue from a wider surface area of the financial system while reducing dependence on volatile retail trading volumes. The model also positions the company to benefit from the anticipated tokenization of real-world assets, which requires precisely the kind of multi-brand, regulated infrastructure Payward is building.

    Frequently Asked Questions

    How does Payward’s strategy differ from Coinbase’s?

    Coinbase concentrates its products and services within a single Coinbase-branded platform for retail and institutional users. Payward is building a regulated infrastructure stack intended to power financial products across multiple brands, customer segments, and third-party partner channels rather than funneling all activity through the Kraken exchange brand.

    What market-share data contextualizes Kraken’s position?

    CoinGecko data shows Kraken averaged roughly $1.1 billion in daily spot trading volume in the first four months of 2026. Binance held 38.7% of top-10 centralized exchange spot volume in Q2 2026, and Coinbase reported an 8.6% share of overall crypto trading volume in Q1 2026.

    What is the “Everything Financial Infrastructure” model described by Architect Partners?

    Architect Partners uses the term to describe Payward’s approach of providing a regulated, programmable infrastructure layer—covering custody, settlement, compliance, and asset issuance—that can be white-labeled or embedded by multiple brands and financial institutions, moving beyond the single-brand “Everything Exchange” paradigm.
  • Altcoin Eliminates Token Inflation, Price Surges

    Altcoin Eliminates Token Inflation, Price Surges

    Key Highlights

    • Ethena Protocol will halt all $USDe token incentives and inflation by end of September, marking a full transition to a sustainable yield model.
    • $ENA token price surged to $0.28, leading altcoin gains, as markets reacted to the incentive wind-down and a new Binance partnership.
    • Ethena is expanding its basis trade strategy into tokenized equity markets via Binance-issued bStocks, diversifying $USDe yield sources beyond crypto perpetual futures.

    Ethena Ends $USDe Incentive Program, Shifts to Sustainable Yield Model

    Ethena Labs, the issuer of the synthetic dollar $USDe and governance token $ENA, has confirmed that all token incentives and associated inflation supporting $USDe growth will cease completely by the end of September. The protocol announced that incentive emissions have already been reduced by approximately 85% since the initial airdrop in 2024, and no new tokens will be issued for this purpose moving forward. In a statement, the Ethena team thanked the community of users and liquidity providers whose participation helped $USDe reach its current scale, framing the decision as a deliberate stepping stone to shift the protocol from a growth-promoting phase to a more sustainable, long-term operational model.

    Market Reaction Drives $ENA Price Surge

    The announcement coincided with a sharp rally in the $ENA token. According to data from HTX (formerly Huobi), $ENA emerged as one of the leading performers in the altcoin sector during the session, with its price climbing to $0.28. Market observers attribute the positive price action not only to the clarity provided by the incentive wind-down—which removes future sell pressure from token emissions—but also to a strategic partnership unveiled days earlier that could fundamentally diversify the protocol’s revenue base.

    Strategic Pivot: Expanding Basis Trade into Tokenized Equities

    Binance Partnership Unlocks Traditional Finance Yield

    On September 25, Ethena revealed a collaboration with Binance to expand its core “basis trade” strategy beyond cryptocurrency perpetual futures markets into equity perpetual futures. Under the new framework, Ethena plans to purchase bStocks—tokenized equity certificates issued by Binance-affiliated entities—and hedge the directional risk by shorting USDT-margined perpetual futures on the same underlying equities on the Binance platform. This mechanism aims to capture the funding rate spread between the spot tokenized equity and its perpetual future, effectively porting the protocol’s proven delta-neutral strategy from crypto-native assets into traditional equity indices and stocks.

    Diversifying $USDe’s Return Stack

    The move represents a significant evolution in $USDe’s yield generation. Historically, the synthetic dollar’s returns have been derived almost exclusively from funding rates in cryptocurrency perpetual futures markets (primarily BTC and ETH). By integrating tokenized equities via Binance, Ethena accesses a vastly larger, less correlated pool of funding rate premiums tied to traditional financial markets. This diversification could stabilize $USDe yields during periods of low crypto volatility and reduce the protocol’s concentration risk in digital asset derivatives.

    Why This Matters

    Ethena’s decision to sunset incentives signals a maturation milestone for the largest synthetic dollar protocol in DeFi, which currently manages over $3 billion in $USDe supply. The transition to a zero-inflation model tests whether $USDe can maintain its peg and market share purely on organic yield from basis trades—a critical proof point for the viability of non-custodial, censorship-resistant stablecoins. Simultaneously, the Binance equity integration bridges DeFi with traditional finance (TradFi) infrastructure, leveraging tokenized real-world assets (RWAs) to unlock new yield frontiers. If successful, this template could accelerate institutional adoption of on-chain synthetic dollars and establish a new paradigm for delta-neutral strategies spanning crypto and equity markets. The next key milestone will be the actual deployment of capital into bStocks positions and the resulting impact on $USDe’s yield profile in Q4 2024.

    Frequently Asked Questions

    When do $USDe token incentives officially end?

    All token incentives and inflation for $USDe will cease by the end of September 2024. The protocol confirmed that emissions have already been reduced by roughly 85% since the 2024 airdrop, and no new incentive tokens will be issued after the cutoff.

    How does the new Binance equity basis trade work?

    Ethena will buy bStocks (tokenized equity certificates from Binance-affiliated issuers) and simultaneously short the corresponding USDT-margined perpetual futures on Binance. This delta-neutral position aims to harvest the funding rate premium from equity perpetual futures, adding a TradFi-linked revenue stream to $USDe’s yield.

    What does the incentive wind-down mean for $ENA holders?

    The cessation of token emissions removes a major source of future sell pressure on $ENA, which the market interpreted positively—driving the token to $0.28 and making it a top altcoin gainer. However, $ENA’s long-term value will depend on the protocol’s ability to generate sustainable fee revenue from its expanded basis trade operations to fund buybacks or staking yields.

  • Binance Deal Boosts Circle in Stablecoin Race With Tether, Analysts Say

    Binance Deal Boosts Circle in Stablecoin Race With Tether, Analysts Say

    Key Highlights

    • Binance processed $5 million to $10 billion in daily USDC spot trading volume throughout 2026, capturing 10-20 times more activity than most other exchanges which typically stay below $500 million daily.
    • USDC’s market capitalization reaches approximately $74 billion, remaining the second-largest dollar stablecoin behind Tether’s USDT at roughly $140 billion.
    • Circle is expanding beyond issuance with its Circle Payments Network and a $400 million acquisition of Singapore-based Tazapay to build payment infrastructure across emerging markets.

    Binance Drives USDC Trading Dominance in 2026

    Binance has cemented its position as the primary venue for USDC spot trading throughout 2026, consistently capturing the largest share of daily volume according to data from market research firm Kaiko. The exchange processed between $5 million and $10 billion in USDC spot trading activity each day, a figure that dwarfs the competition. Most other trading venues typically remain below $500 million in daily USDC volume, making Binance’s throughput roughly 10 to 20 times greater than its nearest rivals.

    “Throughout 2026, Binance has consistently captured the largest share of $USDC spot trading activity, processing $5 million-$10 billion in daily volume, roughly 10-20 times more than most other trading venues, which typically stay below $0.5 billion,” said Anastasia Melachrinos, head of research at Kaiko.

    Exchange Landscape Remains Static as Binance Expands

    Kaiko’s analysis indicates that other major exchanges have largely maintained their previous USDC trading ranges, suggesting that Binance itself has been the primary driver of the volume increase. The concentration of activity on a single platform underscores the exchange’s outsized influence on stablecoin liquidity and market structure. As Binance continues to push USDC adoption in emerging markets, researchers expect this dominance to intensify further.

    “As Binance accelerates $USDC’s reach in emerging markets, that dominance is likely to grow even further,” Melachrinos said.

    Circle Counters Tether with Infrastructure Play

    The trading dynamics unfold against a backdrop of intensifying competition between the two leading dollar-pegged stablecoins. USDC currently holds a market capitalization of about $74 billion, positioning it as the second-largest U.S. dollar stablecoin behind Tether’s USDT, which commands roughly $140 billion. Industry observers see a clear mutual incentive for both Binance and Circle, USDC’s issuer, to expand the stablecoin’s footprint through the exchange’s global user base and infrastructure.

    “There is a clear incentive on both sides to grow $USDC through Binance’s user base and infrastructure,” said Martins Benkitis, co-founder and CEO of Gravity Team.

    Circle has been actively building beyond its core issuance business. The company’s Circle Payments Network aims to connect financial institutions for stablecoin-based payments, while its recently announced $400 million acquisition of Singapore-based Tazapay would add local banking relationships and payment rails across emerging markets. This strategy arrives as the stablecoin competitive landscape broadens beyond the traditional Circle-Tether duopoly, with major banks and payment companies including Visa, Mastercard, and Stripe pushing further into stablecoin payments and infrastructure.

    Why This Matters

    The concentration of USDC trading volume on Binance highlights the evolving market structure of stablecoin liquidity, where a single centralized exchange acts as the primary price discovery venue for a major digital asset. For Circle, the partnership with Binance and the Tazapay acquisition represent a strategic pivot toward becoming a payments infrastructure company, not just a stablecoin issuer. This shift coincides with increasing regulatory clarity in major jurisdictions and the entry of traditional financial giants like Visa and Stripe, signaling a maturation of the stablecoin sector from speculative trading instruments to settlement layers for global commerce. The coming months will test whether Circle’s infrastructure investments can translate USDC’s trading dominance into broader adoption for cross-border payments and institutional settlement.

    Frequently Asked Questions

    How much USDC trading volume does Binance handle compared to other exchanges?
    Binance processes $5 million to $10 billion in daily USDC spot trading volume, which is roughly 10-20 times more than most other trading venues that typically stay below $500 million daily, according to Kaiko research.
    What is Circle’s strategy beyond stablecoin issuance?
    Circle is building the Circle Payments Network to connect financial institutions for stablecoin payments and has announced a $400 million acquisition of Singapore-based Tazapay to gain local banking relationships and payment rails across emerging markets.
    How does USDC’s market cap compare to USDT?
    USDC has a market capitalization of about $74 billion, making it the second-largest U.S. dollar stablecoin behind Tether’s USDT at roughly $140 billion.
  • Bitget Hacker Moves $83 Million in Stolen XRP That Ripple Cannot Freeze

    Bitget Hacker Moves $83 Million in Stolen XRP That Ripple Cannot Freeze

    Key Highlights

    • Circle and Tether froze approximately $320,000 in USDC and USDT stablecoins linked to the Bitget exchange hack, leveraging built-in blacklist controls.
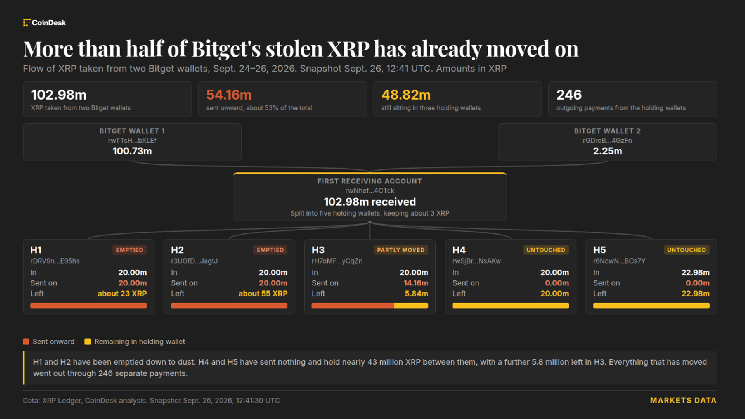
    • The attacker moved roughly 54 million XRP from the original five holding wallets overnight, reducing the balance from 70 million to 49 million tokens in eight hours.
    • XRP traded near $1.54 on Saturday, down 4% in 24 hours but retaining a 9% weekly gain, with the stolen haul valued at approximately $160 million.

    Stablecoin Issuers Intervene to Block Illicit Funds

    Circle and Tether, the operators behind the leading dollar-pegged stablecoins USDC and USDT, have taken swift action to mitigate the fallout from the massive Bitget crypto exchange breach. The companies froze roughly $320,000 worth of stablecoins associated with the hacker’s wallet addresses. Both tokens possess programmable controls that allow the issuers to blacklist specific addresses, effectively preventing the frozen assets from being transferred or redeemed. This intervention highlights the centralized enforcement layer that exists within major fiat-backed stablecoins, a feature often cited by regulators and critics alike.

    Attacker Accelerates XRP Distribution Across Wallets

    On-chain data shows the perpetrator significantly sped up the movement of stolen XRP tokens during the early hours of Saturday. At 04:32 UTC, approximately 70 million XRP remained in the original five accounts identified as the initial holding points for the stolen funds. Roughly eight hours later, that aggregate balance had dropped to 49 million, indicating a rapid dispersal strategy. The transfers reveal the attacker distributing the assets across a growing number of wallets, a common tactic to obfuscate the trail and complicate recovery efforts.

    Transaction Patterns Suggest Automated Scripting

    Analysis of the transfer flows shows certain payments replicating routes previously used by the first wallet. In one notable instance, an attempted transfer of about 521,000 XRP failed because the sending account lacked sufficient funds. Approximately one hour later, a second wallet executed an identical transfer of 521,000 XRP to the same intended recipient. This pattern suggests the use of automated scripts or predetermined routing logic rather than purely manual intervention, with the attacker managing multiple wallets in parallel to drain the holdings.

    Market Absorbs Supply Overhang Amid Price Resilience

    Despite the significant movement of stolen funds, XRP markets displayed relative stability on Saturday. The token traded around $1.54, representing a 4% decline over the preceding 24 hours but maintaining a weekly gain of approximately 9%, according to data from CoinGecko. At the prevailing price, the original XRP haul—estimated at roughly 100 million tokens based on the 54 million moved and 49 million remaining—was worth approximately $160 million. That figure equates to roughly 4% of XRP’s reported $4.4 billion in daily trading volume, suggesting the market possesses sufficient liquidity to absorb potential sell pressure, though actual price impact will depend on the depth of buy orders at the time of execution.

    Why This Matters

    The Bitget hack and subsequent fund movements underscore several critical dynamics in the crypto ecosystem. First, the ability of Circle and Tether to freeze assets demonstrates the “off-switch” capability inherent in centralized stablecoins, providing a rapid response mechanism for illicit flows that does not exist for native blockchain assets like XRP. Second, the speed and sophistication of the XRP laundering—evidenced by automated multi-wallet distribution and retry logic—illustrates the operational maturity of modern cybercriminal groups targeting exchanges. Finally, the market’s muted price reaction reflects XRP’s deep liquidity and the market’s growing desensitization to large-scale exchange breaches, though the ultimate impact hinges on whether the attacker opts for rapid liquidation via decentralized exchanges or slower over-the-counter channels.

    Frequently Asked Questions

    How much XRP was stolen in the Bitget hack?

    Based on on-chain analysis, the original haul held in five primary wallets totaled approximately 119 million XRP (70 million remaining at 04:32 UTC plus 49 million moved subsequently). At Saturday’s price of $1.54, the total value was roughly $160 million.

    Can Circle and Tether freeze XRP tokens?

    No. Circle and Tether can only freeze assets issued on their respective contracts—USDC and USDT. XRP is a native asset on the XRP Ledger and does not have a centralized freeze function. The $320,000 freeze applied only to stablecoin balances held in the hacker’s wallets.

    Will the stolen XRP dump crash the price?

    The stolen amount represents about 4% of XRP’s reported daily trading volume ($4.4 billion). While a sudden market sale could cause short-term slippage, the depth of the order books across major exchanges suggests the market could absorb the supply without a catastrophic price collapse, especially if distributed over time or via OTC desks.

  • Serious Fraud Allegations Against Joe Biden’s Son Rock Cryptocurrency Market

    Serious Fraud Allegations Against Joe Biden’s Son Rock Cryptocurrency Market

    Key Highlights

    • Hunter Biden denies allegations that the LAPTOP memecoin team earned tens of millions of dollars, stating no tokens have been sold from the project wallet.
    • LAPTOK’s market value has fallen below $25 million, representing a roughly 99.9% decline from its launch valuation.
    • Biden demands public disclosure of the wallet address allegedly used for the contested sales, challenging the methodology behind the “eight-figure” profit claims.

    Hunter Biden Confronts LAPTOP Memecoin Profit Allegations Amid 99.9% Price Collapse

    The Solana-based memecoin LAPTOP, which drew immediate attention for its associative link to Hunter Biden, son of former U.S. President Joe Biden, has re-entered public scrutiny following a catastrophic price decline and fresh allegations of insider enrichment. According to on-chain data and market analytics, the token’s market capitalization has plummeted below $25 million, erasing approximately 99.9% of its peak launch value. The collapse has fueled speculation that the project’s founding team may have realized an “eight-figure” profit—defined as at least $10 million—through early token liquidations.

    Biden Denies Team Token Sales, Demands On-Chain Evidence

    In a direct response to the profit calculations circulating among crypto analysts and media outlets, Hunter Biden categorically rejected the assertion that the project team had cashed out tens of millions of dollars. He maintained that the wallet controlled by the LAPTOP team has not executed any token sales to date. Biden further challenged the provenance of the profit estimates, demanding that the individual or entity responsible for the “eight-figure” calculation publicly reveal the specific wallet address allegedly used for these transactions. His intervention marks a rare direct engagement by a political figure’s family member with the mechanics of a cryptocurrency project.

    Previous Statements and Ongoing Account Review

    Biden referenced his prior characterization of the post-launch market dynamics as “appalling”, indicating that the relevant financial accounts and token distributions were undergoing active review. This statement suggests an internal acknowledgment of the severity of the price action and the reputational risk attached to the project’s performance. The LAPTOP team had previously issued denials regarding insider selling, attributing the extreme volatility to structural factors rather than malicious dumping.

    Technical Defense: Liquidity Constraints and Sniper Bot Activity

    The project’s defenders have pointed to two primary technical catalysts for the price implosion. First, critically low liquidity during the initial trading window meant that even modest sell orders exerted disproportionate downward pressure on the token price. Second, the pervasive use of automated “sniper bots”—high-speed trading algorithms designed to frontrun launches and extract value from liquidity pools—amplified price swings and distorted organic price discovery. Regarding tokenomics, the team clarified that the 30% allocation reserved for founders is subject to a six-month cliff followed by a linear unlock schedule extending over two years, a standard vesting mechanism intended to align long-term incentives.

    Why This Matters

    The LAPTOP episode underscores the persistent intersection of political branding, memecoin speculation, and regulatory gray zones in the digital asset ecosystem. Tokens leveraging political figures—whether endorsed, tacitly permitted, or entirely unauthorized—continue to attract speculative capital despite extreme risk profiles. The near-total value destruction here serves as a case study in the dangers of low-float, high-fully-diluted-valuation launches compounded by predatory algorithmic trading. For regulators and consumer advocates, the incident reinforces concerns about market manipulation, insider enrichment, and the lack of recourse for retail participants in unregistered token offerings. The demand for on-chain transparency—specifically the public verification of wallet addresses—highlights the unique auditability of public blockchains, a feature that remains underutilized in dispute resolution.

    Frequently Asked Questions

    Has Hunter Biden confirmed any personal financial gain from the LAPTOP token?

    No. Hunter Biden has explicitly denied that the project team—including by implication himself—has sold any tokens from the designated project wallet or realized profits from the launch. He has challenged accusers to produce the specific wallet address used for alleged sales.

    What caused the LAPTOP token to lose 99.9% of its value?

    The project attributes the collapse to extremely low initial liquidity and aggressive trading by automated “sniper bots,” which exploited the thin order books. The team denies that insider selling drove the decline, noting that founder allocations remain locked under a multi-year vesting schedule.

    Is the LAPTOP token officially affiliated with the Biden family or the former administration?

    The token is described as “linked to” Hunter Biden in market discourse, but no official governmental or institutional endorsement has been documented. The project appears to be an independent memecoin leveraging political association for marketing momentum, a common pattern in the current memecoin landscape.

  • Peter Brandt Labels XRP “Fool Coin” in Controversial Comments

    Peter Brandt Labels XRP “Fool Coin” in Controversial Comments

    Key Highlights

    • Veteran trader Peter Brandt reiterated his long-standing skepticism toward XRP, labeling it a “dumb coin” and questioning its tokenomics despite Ripple’s expanding bank partnerships.
    • Brandt draws a sharp fundamental distinction between Bitcoin as a “store of value” and XRP as a transaction-focused asset, arguing utility alone does not drive token price appreciation.
    • The trader expressed a more favorable view on Ethereum and Solana, calling Ethereum a “good asset” with upside potential, while maintaining Bitcoin as his preferred core portfolio holding.

    Brandt Doubles Down on XRP Skepticism Amid Ripple Progress

    Senior market trader Peter Brandt has reaffirmed his bearish stance on XRP, stating that recent developments within the Ripple ecosystem—including widespread collaborations with global banking institutions—have failed to alter his fundamental assessment of the asset. During a recent interview, Brandt was pressed on whether Ripple’s institutional momentum and technological advancements warranted a reassessment. He responded by maintaining his skepticism, emphasizing that structural questions surrounding the token’s supply dynamics and value accrual mechanism remain unresolved.

    A Fundamental Taxonomy: Store of Value vs. Transaction Utility

    Central to Brandt’s thesis is a categorical distinction between crypto assets based on their primary utility. He characterizes Bitcoin primarily as a “store of value,” acknowledging its current speculative trading nature while attributing to it monetary properties akin to digital gold. In contrast, he views XRP as an asset designed explicitly for transactional throughput and cross-border settlement. This classification leads him to a blunt appraisal: he directly referred to XRP as a “dumb coin,” arguing that its transactional efficiency does not inherently translate into investment merit.

    Utility Does Not Equal Value Accrual

    When challenged on XRP’s proven ability to facilitate cheap, rapid transactions, Brandt conceded the technical point but rejected the investment conclusion. He cited the U.S. dollar as a parallel: a fiat currency used globally for highly effective transactions that no holder expects to appreciate in value solely because of its velocity. “Just because something can be used in transactions doesn’t automatically mean it has to be more valuable,” Brandt stated. He posited that the critical unanswered question for XRP is at what inflection point transactional volume converts into genuine economic value for the token itself, rather than merely benefiting the Ripple network infrastructure.

    Diverging Views on Ethereum and Solana

    Brandt’s critique does not extend uniformly across the altcoin landscape. He spoke positively of Ethereum, describing it as a “good asset” and expressing confidence that both Ethereum and Solana possess the potential to reach higher valuation levels. He places these networks in a separate category from both Bitcoin and XRP—platforms upon which applications are built—suggesting they warrant a distinct valuation framework. Ultimately, Brandt disclosed a personal portfolio preference heavily weighted toward Bitcoin, reinforcing his conviction in the premier cryptocurrency’s monetary role over utility-focused alternatives.

    Why This Matters

    Peter Brandt’s commentary carries weight due to his decades-long track record in commodity and futures trading, offering a traditional market perspective on digital asset classification. His insistence on separating “store of value” narratives from “utility token” mechanics highlights a persistent debate in crypto valuation methodologies. As Ripple continues to secure regulatory clarity—most notably the July 2023 court ruling that XRP is not inherently a security—and expands its On-Demand Liquidity (ODL) corridors with financial institutions, the market is actively testing whether enterprise adoption creates token holder value. Brandt’s dollar analogy underscores a critical tokenomics question: velocity and utility are necessary but not sufficient conditions for price appreciation without a mechanism capturing that value (e.g., fee burns, staking yields, or supply constraints). Meanwhile, his endorsement of Ethereum and Solana reflects growing institutional comfort with smart contract platforms as programmable settlement layers, a narrative driving ETF filings and allocation shifts in 2024.

    Frequently Asked Questions

    What specific concerns did Peter Brandt raise about XRP’s tokenomics?
    Brandt highlighted “question marks regarding the total supply and whether it would expand in the future,” suggesting uncertainty over XRP’s emission schedule and escrow release mechanism undermines its credibility as a scarce store of value.
    How does Brandt differentiate Bitcoin from XRP and Ethereum?
    He categorizes Bitcoin as a “store of value” asset, XRP as a transaction-focused utility token, and Ethereum (alongside Solana) as an application platform layer—arguing each requires a distinct valuation framework rather than a one-size-fits-all approach.
    Does Peter Brandt hold any XRP or recommend it as an investment?
    No. Brandt explicitly maintained his skepticism, called XRP a “dumb coin,” and stated he prefers Bitcoin for the majority of his cryptocurrency portfolio. The source includes a disclaimer: “This is not investment advice.”
  • Bullish Targets Wall Street’s Tokenized Stock Ownership Gap

    Bullish Targets Wall Street’s Tokenized Stock Ownership Gap

    Key Highlights

    • Five major financial infrastructure firms formed the Issuer Sponsored Token Coalition on Sept. 24 to create tokens tied directly to official shareholder registers, not just price-tracking wrappers.
    • The SEC’s new five-year Innovation Exemption, effective Sept. 17, requires tokenized securities to convey the same legal rights as traditional shares—voting, dividends, and corporate actions—to qualify.
    • Equiniti, which Bullish agreed to acquire in May, brings nearly 3,000 issuer clients and 20 million shareholders, while Alpaca already backs over 94% of tokenized U.S. stocks with $1.5 billion in custody.

    Wall Street’s Tokenization Pivot: From Price Mirrors to Legal Ownership

    A consortium of financial infrastructure heavyweights—Bullish, Equiniti, Alpaca, Apex Fintech Solutions, and Drivewealth—launched the Issuer Sponsored Token Coalition on September 24 with a singular objective: to replace the crypto wrappers that merely track stock prices with onchain tokens that represent actual, legally recognized share ownership. The distinction is not semantic. As Drivewealth CEO Naureen Hassan put it plainly: “Much of what’s marketed today as ‘tokenized equity’ isn’t equity at all. Investors think they own the share, and they don’t.”

    Current tokenized-stock models typically operate by having a broker hold real shares in custody and mint tokens against them on a 1:1 basis. While these tokens can deliver economic exposure and, in some configurations, pass along dividends, the token holder often does not appear on the company’s official shareholder register. That absence leaves voting rights, proxy participation, and corporate actions such as stock splits in a legal gray zone. Issuer-sponsored tokenization takes a fundamentally different approach: the public company and its transfer agent are directly involved, anchoring the token to the canonical ownership record so that the full bundle of shareholder rights travels with the digital asset.

    Regulatory Catalyst and the Infrastructure Bridge

    The coalition’s formation coincides with a pivotal regulatory development. On September 17, the U.S. Securities and Exchange Commission opened a five-year Innovation Exemption permitting certain Tokenized Securities Venues to operate permissioned automated market makers and liquidity pools for tokenized National Market System stocks. The exemption carries a critical condition: qualifying tokens must provide the same rights and privileges as traditional shares. Tokens that merely mirror a stock’s price do not qualify, effectively setting a regulatory floor that the coalition is structured to meet.

    The membership roster reads like a map of Wall Street’s plumbing. Equiniti, which the crypto exchange Bullish agreed to acquire in May, serves nearly 3,000 issuer clients and more than 20 million shareholders. As a transfer agent, Equiniti maintains the official shareholder books, making it the essential bridge between an issuer’s records and whatever eventually lives onchain. On the brokerage side, Alpaca reported through mid-2026 that it accounted for roughly 94% of tokenized U.S. stocks and ETFs, backed by more than $1.5 billion in underlying shares held in custody. Apex Fintech Solutions contributes clearing and broker-dealer infrastructure, while Drivewealth supplies U.S. stock access to investing platforms worldwide.

    Technical Standards and the Path to Launch

    The group’s immediate agenda targets the hard problems of interoperability: technical standards, settlement workflows, custody models, and the integration of traditional market infrastructure with blockchain rails. Members will meet with public-company issuers at the New York Stock Exchange on October 27 to advance those discussions. Notably, no new tokenized stock launched alongside the coalition’s announcement—a deliberate signal that the industry is prioritizing legal and operational certainty over speed to market. Before Wall Street can put real shares onchain, it first has to ensure that a token claiming to represent ownership actually does.

    Why This Matters

    The Issuer Sponsored Token Coalition represents the most concerted effort yet to align blockchain-based capital markets with existing securities law and market structure. By anchoring tokens to the official shareholder register—maintained by transfer agents like Equiniti—the model seeks to eliminate the legal ambiguity that has plagued earlier tokenization attempts. The SEC’s Innovation Exemption provides a regulatory sandbox, but its requirement for full rights parity raises the bar: only tokens that convey voting, dividends, and corporate-action participation will qualify. If the coalition succeeds in standardizing settlement, custody, and interoperability across its members’ combined infrastructure, it could establish the blueprint for a new class of permissioned, institutionally native digital securities. The October 27 meeting at the NYSE will be an early test of issuer appetite and the practical feasibility of migrating shareholder records onto distributed ledgers without disrupting the existing equity ecosystem.

    Frequently Asked Questions

    What is the difference between current tokenized stocks and issuer-sponsored tokenization?

    Current models typically involve a broker holding shares in custody and minting tokens that track the stock’s price and may pass dividends, but the token holder is not listed on the company’s official shareholder register. Issuer-sponsored tokenization ties the token directly to that register—maintained by the transfer agent—so voting rights, proxies, stock splits, and other corporate actions travel with the token.

    Which firms formed the Issuer Sponsored Token Coalition and what do they bring?

    The coalition comprises Bullish, Equiniti, Alpaca, Apex Fintech Solutions, and Drivewealth. Equiniti (being acquired by Bullish) serves nearly 3,000 issuers and 20+ million shareholders as a transfer agent. Alpaca backs roughly 94% of tokenized U.S. stocks with over $1.5 billion in custody. Apex provides clearing and broker-dealer infrastructure, and Drivewealth powers U.S. stock access for global platforms.

    What does the SEC’s Innovation Exemption require for tokenized securities?

    The five-year exemption, effective September 17, allows qualified Tokenized Securities Venues to operate permissioned automated market makers and liquidity pools for tokenized National Market System stocks. The key condition: tokens must provide the same rights and privileges as traditional shares—including voting, dividends, and corporate actions. Price-tracking tokens that do not confer legal ownership do not qualify.

  • Polygon Price Rises 12% Since 100M POL Burn — Can It Hold Above $0.11?

    Polygon Price Rises 12% Since 100M POL Burn — Can It Hold Above $0.11?

    Key Highlights

    • Polygon permanently burned 100 million $POL tokens—approximately 1% of total supply—worth roughly $10.22 million on September 23.
    • $POL has surged nearly 12% since the burn, trading near $0.113, but faces immediate resistance at the $0.115 level.
    • The burn introduces a community-governed, fee-funded mechanism linking future token removal directly to Polygon network activity.

    Polygon Executes Major $POL Token Burn, Removing 1% of Supply

    Polygon has completed a significant token burn, permanently removing 100 million $POL from circulation on September 23. The transaction, confirmed by Polygon Foundation CEO Sandeep Nailwal, destroyed tokens valued at approximately $10.22 million at the time of execution. This reduction represents roughly 1% of the token’s total supply and marks the activation of a new deflationary mechanism designed to tie future burns directly to network usage fees.

    Fee-Funded Burn Mechanism Links Supply Reduction to Network Activity

    The burned tokens originated from network fees accumulated within Polygon’s fee-collection system. Beyond the immediate supply reduction, the event inaugurates a process allowing the community to trigger subsequent fee-funded burns. This governance feature creates a direct feedback loop: as transaction activity on the Polygon network generates fees, the community can vote to destroy a portion of those fees, dynamically adjusting supply in response to real-time demand for blockspace.

    $POL Price Action Tests Critical Resistance at $0.115

    Since the burn, $POL has appreciated approximately 11.6%, climbing to the $0.113 area at the time of writing. The token briefly touched $0.11497 during the most recent session but failed to sustain momentum above the $0.115 threshold. Technical analysts identify this level as the nearest hurdle for buyers; a decisive break could open a path toward the $0.12 price level. However, the $0.12–$0.125 zone may present stiffer resistance, as the market previously staged a sharp rejection there earlier in September.

    Support Levels and Demand Dynamics Will Determine Next Move

    On the downside, the $0.107–$0.110 range serves as the first critical support. Holding this band would signal that buyers remain committed to the post-burn recovery. A breakdown below that area could see price retrace toward $0.102, near the launch point of the current advance. While the burn strengthens Polygon’s supply-reduction narrative, sustained price appreciation remains contingent on sufficient demand to defend and build upon recent gains.

    Why This Matters

    Polygon’s shift to a programmatic, fee-based burn model represents a maturation of tokenomics for a major Layer 2 scaling solution. Unlike one-time manual burns, the new mechanism embeds deflationary pressure into the protocol’s ongoing operations, aligning tokenholder incentives with network adoption. For investors and developers, the key metric to monitor will be whether rising Polygon network activity—measured in transaction fees—translates into consistent community-approved burns that meaningfully contract supply over time. The immediate price test at $0.115 will also serve as an early gauge of market confidence in this revised economic design.

    Frequently Asked Questions

    How many $POL tokens were burned and what was their value?

    Polygon permanently destroyed 100 million $POL tokens, worth approximately $10.22 million at the time of the September 23 transaction.

    What makes this burn different from previous token burns?

    This burn activates a recurring, community-governed process that allows future burns to be funded directly from network transaction fees, linking supply reduction to actual Polygon network usage.

    What are the key price levels to watch for $POL after the burn?

    Immediate resistance sits at $0.115; a break could target $0.12, though the $0.12–$0.125 region has previously rejected price. Key support lies between $0.107 and $0.110, with a deeper floor near $0.102.

  • Fed Moves to Tighten Stablecoin Rules With Two New GENIUS Act Proposals

    Fed Moves to Tighten Stablecoin Rules With Two New GENIUS Act Proposals

    Key Highlights

    • The Federal Reserve proposed two rules on Thursday to establish oversight for payment stablecoin issuers under the GENIUS Act, opening a 60-day public comment period.
    • The first proposal mandates full backing of stablecoins with approved reserve assets such as short-term U.S. Treasury bills and sets capital requirements for credit and operational risks.
    • The second proposal outlines application procedures for Fed-supervised banks seeking to issue payment stablecoins, including business plan submissions, financial disclosures, and appeals processes.

    Federal Reserve Unveils Dual Regulatory Framework for Stablecoin Oversight

    The Federal Reserve announced two proposed rules Thursday aimed at establishing a comprehensive supervisory framework for payment stablecoin issuers operating under the Guiding and Establishing National Innovation for US Stablecoins ($GENIUS) Act. The proposals, published for public comment, represent the central bank’s most detailed regulatory action to date on dollar-denominated stablecoins since the legislation was signed into law by President Donald Trump on July 18, 2025. The public comment period will close 60 days after publication in the Federal Register, giving market participants, legal experts, and consumer advocates a structured window to shape the final rulemaking.

    Reserve Asset Requirements and Capital Standards Detailed

    The first proposal targets payment stablecoin issuers supervised by the Federal Reserve, requiring them to fully back their tokens with approved reserve assets. Eligible assets include short-term U.S. Treasury bills and other high-quality liquid assets, a design intended to ensure immediate redeemability even under severe market stress. Beyond asset composition, the rule sets explicit capital requirements for credit and operational risks and introduces risk management standards tailored to stablecoin activities. A companion provision addresses firms that hold assets backing stablecoins, clarifying which stablecoin-related activities are permissible for banks under Federal Reserve supervision.

    Bank Application Process and Supervisory Clarifications

    The second proposal focuses on the authorization pathway for Fed-supervised banks that wish to issue payment stablecoins. Applicant institutions must submit detailed business plans, financial information, and supporting documentation for review. The framework also establishes formal procedures for appeals and hearings related to application decisions, embedding due process into the supervisory architecture. Together, the two proposals create a dual-track regime: one governing the ongoing operational and financial integrity of stablecoin issuers, the other governing entry into the business by depository institutions.

    Governor Barr Emphasizes Redemption Stability and Public Input

    Federal Reserve Governor Michael Barr underscored the core objective of the rulemaking in a statement accompanying the release. He said stablecoins can only remain stable if users can quickly redeem them at full value. This should hold even during market stress or when the issuer and related companies face financial strain. He went on to add,

    “I support the proposed rulemaking as a step in that direction within the framework provided by the $GENIUS Act, particularly as the rulemaking identifies key questions on which public feedback will be important. I am encouraged by provisions for reserve asset limitations, as well as transparent and standardized capital requirements. It will be useful to have public input on both of these aspects of the proposal, and in particular on whether the rule adequately addresses interest rate and foreign currency risks.”

    Barr’s remarks highlight two areas where the Federal Reserve is explicitly seeking feedback: the calibration of reserve asset limitations and the design of capital requirements, with particular attention to interest rate and foreign currency risk exposures that could affect stablecoin stability.

    Why This Matters

    The Federal Reserve’s proposals arrive amid a rapidly converging regulatory landscape for stablecoins in the United States. The $GENIUS Act, enacted in July 2025, established the federal statutory framework, but implementation depends on coordinated rulemaking across multiple agencies. The Treasury Department last month issued proposed definitions covering who may issue U.S. stablecoins and which entities fall under the law’s compliance obligations. The Federal Deposit Insurance Corporation (FDIC) initiated its own regulatory process in December 2024, while several agencies in June 2025 proposed applying existing customer identification and verification requirements to stablecoin issuers. The Fed’s dual proposals now add the prudential supervisory layer—capital, liquidity, risk management, and entry standards—specifically for institutions under its jurisdiction. The 60-day comment period will be closely watched by issuers such as Circle and Tether, banking organizations evaluating stablecoin entry, and congressional overseers monitoring whether the regulatory architecture balances innovation with financial stability.

    Frequently Asked Questions

    What reserve assets are permitted under the Federal Reserve’s first proposal?

    The proposal requires payment stablecoin issuers to fully back tokens with approved reserve assets, specifically short-term U.S. Treasury bills and other high-quality liquid assets.

    Which institutions are covered by the two proposed rules?

    The first proposal applies to payment stablecoin issuers supervised by the Federal Reserve and firms holding backing assets. The second proposal governs Fed-supervised banks that apply to issue payment stablecoins.

    How long is the public comment period and when does it end?

    The public comment period runs for 60 days after the proposals are published in the Federal Register; the exact closing date will be determined by the publication date.

  • Sequans Completes Bitcoin Treasury Exit, Sells Final 314 BTC

    Sequans Completes Bitcoin Treasury Exit, Sells Final 314 BTC

    Key Highlights

    • Sequans Communications (NYSE: SQNS) has sold its remaining 314 Bitcoin, completing a treasury exit that leaves the company with no cryptocurrency holdings and a debt-free balance sheet outside government-backed research financing.
    • The Paris-based semiconductor firm reported product revenue growth exceeding 80% year-over-year in Q2 2026, with its six-month product backlog more than tripling compared to the prior year.
    • CEO Dr. Georges Karam framed the exit as a strategic refocus on the company’s core 5G/4G cellular IoT and software-defined radio chip business, contrasting with a broader corporate trend of Bitcoin accumulation by firms such as Strive and Strategy.

    Sequans Closes Bitcoin Chapter to Sharpen Semiconductor Focus

    Sequans Communications, the French designer of 5G and 4G cellular Internet of Things chips and software-defined radio transceivers, announced on September 24 that it has finalized its Bitcoin treasury strategy by selling the 314 Bitcoin remaining on its balance sheet as of June 30, 2026. The transaction concludes a wind-down first signaled when the company redeemed its convertible debt in May 2026. Sequans now holds what it describes as a strong cash position, a simplified capital structure, and no debt outside of government-financed research programs, positioning the firm as a pure-play semiconductor company.

    CEO Emphasizes Disciplined Execution and Financial Clarity

    Dr. Georges Karam, Chief Executive Officer of Sequans, characterized the move as a deliberate step to strengthen the company’s financial foundation. “The completion of our Bitcoin treasury strategy marks an important milestone for Sequans and reflects the disciplined execution of a strategy designed to strengthen our financial foundation,” said Dr. Georges Karam, CEO of Sequans. He added that the proceeds, combined with the earlier debt redemption, give management the flexibility to concentrate fully on the company’s long-term growth roadmap. “By eliminating our convertible debt, monetizing our remaining Bitcoin holdings in a measured and opportunistic manner, and emerging with a very strong balance sheet, we have positioned the Company to focus entirely on executing our long-term semiconductor growth strategy,” Karam said.

    Exit Runs Counter to Corporate Accumulation Trend

    The decision places Sequans at odds with a still-expanding corporate Bitcoin trend. Earlier in September, Strive increased its treasury to 26,355 BTC with a 1,355-Bitcoin purchase, while Strategy—formerly known as MicroStrategy—added another 950 Bitcoin in its first acquisition since August. Sequans, founded in 2003 and headquartered near Paris, explicitly framed its departure as a return to a pure-play semiconductor profile rather than a directional bet on Bitcoin’s price trajectory.

    Core Business Momentum Accelerates Amid 5G eRedCap and RF Transceiver Push

    The treasury exit coincides with accelerating operational performance. Sequans reported product revenue growth of more than 80% year-over-year in the second quarter of 2026, while its six-month product backlog at quarter-end more than tripled versus the same period a year earlier. The company is advancing its 5G eRedCap platform and building commercial momentum for a recently launched RF transceiver. In Q2 2026, Sequans secured a first drone design win and cited growing interest across defense, drone, and space markets for its portfolio, which spans LTE-M, NB-IoT, Cat 1bis, and 5G RedCap and eRedCap platforms.

    Why This Matters

    Sequans’ Bitcoin exit signals a maturation phase for corporate treasury strategies that experimented with cryptocurrency as a reserve asset during 2020–2022. While high-profile accumulators such as Strategy continue to treat Bitcoin as a primary treasury asset, Sequans’ reversal underscores a segment of public companies prioritizing balance-sheet simplicity and investor clarity over speculative upside. The move also highlights how semiconductor firms exposed to the 5G IoT transition—particularly in RedCap and eRedCap segments targeting industrial, defense, and aerospace applications—are converting design-win pipelines into revenue at scale. With a debt-free structure and a backlog tripling year-over-year, Sequans presents a case study in capital reallocation from alternative assets back into core R&D and go-to-market execution.

    Frequently Asked Questions

    How many Bitcoin did Sequans sell in its final tranche?

    Sequans sold 314 Bitcoin, which represented the full remaining balance held on its books as of June 30, 2026.

    Is Sequans completely debt-free after this transaction?

    The company states it is debt-free outside of government-financed research obligations, having redeemed its convertible debt in May 2026 and now monetized all cryptocurrency holdings.

    What are Sequans’ primary growth drivers following the Bitcoin exit?

    Management is focused on its 5G eRedCap platform, a new RF transceiver for software-defined radio, and expanding design wins in defense, drone, and space markets, supported by a product backlog that has more than tripled year-over-year.