Author: Evan Mercer

  • BitMine’s Staked ETH Equals Nearly 12% of Ethereum’s Active Stake — Who Controls It?

    BitMine’s Staked ETH Equals Nearly 12% of Ethereum’s Active Stake — Who Controls It?

    BitMine Immersion Technologies Nears 12% of Ethereum’s Active Stake Without Validator Transparency

    BitMine Immersion Technologies has accumulated a staked $ETH position equivalent to nearly 12% of Ethereum’s active stake, yet the company has not disclosed which entities control the validators behind that stake. As of Sept. 7, BitMine reported 5.07 million $ETH staked, representing approximately 85% of its 5.93 million $ETH holdings and valued at roughly $12.6 billion based on prices in its latest filing. With about 43.03 million $ETH actively securing the network, BitMine’s staked amount translates to an 11.8% share of Ethereum’s active stake.

    Economic Exposure vs. Consensus Influence

    While the scale of BitMine’s economic exposure is clear, measuring its actual influence over Ethereum’s consensus requires details on how those assets are distributed among validator operators and who holds the signing keys used to propose blocks and attest to transactions. BitMine has not provided that breakdown.

    Its Sept. 8 operational update stated only that “a portion” of its $ETH was already staked through MAVAN, its institutional staking platform. The company also indicated that, at scale, it would stake $ETH through “MAVAN and its staking partners,” leaving the split between BitMine’s own infrastructure and outside operators undisclosed.

    BitMine’s Economic Stake Outruns Its Validator Disclosures

    The distinction grows more consequential as BitMine approaches its goal of owning 5% of Ethereum’s total supply and directs most of those holdings toward staking. Ethereum’s proof-of-stake system assigns consensus influence through validators, whose signing keys authorize block proposals and attestations. Ownership of the $ETH funding those validators does not by itself reveal who can exercise those duties.

    This separation matters because Ethereum’s security model becomes increasingly sensitive as signing authority concentrates. The network requires attestations representing two-thirds of staked $ETH to finalize checkpoints, while an operator controlling at least one-third could prevent finality by withholding its votes. BitMine’s 11.8% economic position remains well below that threshold. Public disclosures also provide no basis for assigning the full percentage to BitMine, MAVAN, or any single staking provider.

    Shifting Operator Relationships Add Complexity

    An earlier quarterly filing described BitMine as the principal node operator while also outlining its reliance on outside infrastructure. Its latest disclosures add further participants without showing how validator responsibilities are divided. BitMine ended a management-services agreement with Ethereum Tower on Sept. 3 and appointed its affiliate American Validator the following day to advise MAVAN Holdings. American Validator will receive a fee equal to 1.5% of rewards generated from company-staked $ETH, but the agreement does not identify it as the operator of the entire validator fleet or assign it signing authority.

    MAVAN’s documentation similarly separates the destination of withdrawn $ETH from validator operations, allowing users to designate where funds ultimately return while using its staking infrastructure.

    Need for Granular Validator Cohort Data

    A clearer concentration assessment would require BitMine to disclose the validator cohorts operated by each provider, their signing-key arrangements, and how infrastructure is distributed across software clients and hosting environments. Those details could become more important if BitMine continues expanding MAVAN beyond its own treasury.

    The company says the platform has grown to serve institutional investors, custodians, and ecosystem partners, potentially putting more third-party $ETH onto infrastructure associated with the BitMine staking business. For Ethereum investors, the next number to watch therefore extends beyond how much $ETH BitMine stakes. Its growing validator business will determine whether the company eventually provides enough operational data to show where the corresponding consensus authority actually resides.

  • BlueMoon Exploit Kit Spreads to Four Hacking Groups in Days

    BlueMoon Exploit Kit Spreads to Four Hacking Groups in Days

    BlueMoon Exploit Kit Rapidly Adopted by Four Hacking Groups, Proofpoint Warns

    A single piece of attack code designed to chain three unpatched vulnerabilities in Chrome and Windows has fallen into the hands of at least four separate hacking crews within days of its creation. Researchers at cybersecurity firm Proofpoint have dubbed the toolkit BlueMoon exploit kit, and they confirm it has already been deployed against U.S. nonprofits, aerospace contractors, a Vietnamese manufacturer, and organizations across Singapore and Indonesia — a dispersion pattern suggesting the tool moved from a single developer to multiple threat groups almost immediately after it was built.

    Key Takeaways

    • Proofpoint identified the BlueMoon exploit kit in use by at least four hacking groups, some linked to Chinese state interests, beginning around August 28.
    • The kit chains two Chromium V8 flaws with a Windows kernel privilege escalation bug to install attacker-chosen malware.
    • All three vulnerabilities — tracked as CVE-2026-85046, a Chromium V8 sandbox escape, and CVE-2026-85880 — received patches within roughly 24 hours of disclosure.
    • Targets span U.S. NGOs, mining and aerospace firms, a Vietnamese manufacturer, and entities in Singapore and Indonesia.
    • The attacks exploited a Chromium patch gap between public source fixes and their rollout into stable Chrome and Edge releases, a window researchers say AI-assisted analysis may have helped attackers close faster.

    Active Use of BlueMoon Exploit Kit by Multiple Hacking Groups

    At least four distinct hacking groups deployed a nearly identical version of the BlueMoon exploit kit, according to Proofpoint, with some of those groups tied to Beijing’s intelligence apparatus. That represents an unusually crowded field for a single exploit chain — fully weaponized Chrome attacks have historically remained in the hands of one or two well-resourced operators, not four simultaneously.

    China-Aligned Groups Among Attackers

    Proofpoint traced the first wave of attacks to TA412, a China-aligned state-sponsored actor the U.S. government formally indicted in 2024 for acting on behalf of China’s civilian foreign intelligence service. That activity began on August 28. A second China-linked group, UNK_LateNight, targeted U.S. aerospace companies, while UNK_DoubleCheck and UNK_QuietRacket rounded out the list of known operators using the same toolkit.

    Targets Span U.S., Southeast Asia, and Strategic Industry Sectors

    The victim list reads like a cross-section of strategic industries rather than a single vertical. TA412 hit NGOs, mining companies, and physical commodity trading firms inside the U.S. UNK_LateNight went after aerospace contractors. UNK_DoubleCheck targeted a Vietnamese manufacturing entity, and UNK_QuietRacket focused on Singapore and Indonesia. Proofpoint said it remains unclear whether other, still-unidentified groups also obtained access to the kit — a detail that leaves the true scope of exposure somewhat open-ended.

    Technical Composition and Exploited Vulnerabilities of BlueMoon

    BlueMoon works by stringing together three separate bugs into one attack path: two flaws in Chromium’s V8 JavaScript engine, followed by a Windows kernel privilege escalation. Once chained, the exploit lets attackers run remote code inside a browser and then escalate to full system control on the underlying machine.

    Chaining Chromium V8 and Windows Kernel Flaws

    The first V8 flaw, tracked as CVE-2026-85046, is a type-confusion bug that gives attackers arbitrary memory access inside the browser’s sandbox. Paired with it is a second V8 issue, a sandbox escape that corrupts WebAssembly metadata to run embedded shellcode — Google doesn’t assign CVE numbers to V8 sandbox escapes, so this flaw has no separate CVE identifier. Once code execution is achieved inside the browser, the attackers pivot to CVE-2026-85880, a local privilege escalation vulnerability in older versions of Windows, letting the malicious code run with full system rights.

    Vulnerabilities Identified and Patched Recently

    All three bugs exploited by BlueMoon have been patched within roughly 24 hours of Proofpoint’s disclosure. The Windows flaw was addressed as part of Microsoft’s September 2026 Patch Tuesday release. The affected Windows versions include Windows 10’s October 2018 Update, Windows 10 version 2004, Windows Server 2019, Windows Server 2022, and the initial release of Windows 11 — a spread that covers systems many organizations are still running years after their original release.

    Rapid Spread Fueled by Chromium Patch Gap and AI-Driven Discovery

    BlueMoon’s speed and visibility are what make it stand out. Most espionage-grade browser exploits are used sparingly and kept quiet on purpose, because burning a rare zero-day fast shortens its useful life. BlueMoon did the opposite: it was built, deployed, and shared across multiple threat actors within days, despite leaving detection signals that made it easy to spot.

    Exploiting Delays in Browser Patch Deployment

    Proofpoint pointed to the Chromium patch gap as a likely driver of that urgency. Chromium is open source, meaning fixes land in the public codebase before they’re incorporated into stable releases of Chrome, Edge, and other Chromium-based browsers. That gap gives attackers a window to reverse-engineer the published fix and build a working exploit before most users actually receive the patched browser.

    “Both V8 vulnerabilities were ‘patch-gap’ zero-days at the time of the observed activity,” Proofpoint said, noting they were already fixed upstream but still exploitable in the latest stable Chrome and Chromium-based browsers available to the public.

    AI Lowers Barriers to Exploit Development

    The other likely factor is speed of discovery itself. Proofpoint suggested that AI vulnerability discovery tools can spot exploitable flaws faster than manual human analysis alone, shrinking the time between a patch appearing in public source code and a working exploit chain going live.

    “A fully weaponized Chrome exploit chain has historically been a high-value, rare capability. BlueMoon was developed, deployed rapidly, and shared across multiple threat actors within days in a manner that had high detection signals. This may reflect a reduced cost and barrier to entry for this class of capability, as AI agents increasingly enable threat actor exploit development.”

    That combination — an open-source patch gap plus AI-accelerated reverse engineering — has implications well beyond this one kit. If high-value browser exploit chains can now be built and shared across multiple threat actors within days rather than months, the economics of cyber espionage shift. Capabilities that used to be scarce and closely guarded by top-tier state actors could become more accessible to a wider range of groups, including financially motivated ones, well before defenders finish rolling out patches everywhere they’re needed.

    Proofpoint warned that despite the visibility of the attacks and the fact that all three flaws are now fixed, BlueMoon may not disappear quietly.

    “Given its ease of adoption, it is likely to proliferate further and be adopted by espionage-motivated and financially motivated threat actors as patched versions are fully rolled out across all Chromium-based browsers,” the researchers said

    — a reminder that patch availability and patch adoption are two very different things, and the gap between them is exactly what BlueMoon was built to exploit.

    Frequently Asked Questions

    What is the BlueMoon exploit kit?

    BlueMoon is an exploit kit that chains three vulnerabilities in Chromium-based browsers and older Windows versions to install malware of the attacker’s choosing.

    Which vulnerabilities does BlueMoon exploit?

    It exploits two Chromium V8 engine vulnerabilities — including a type confusion bug tracked as CVE-2026-85046 — and a Windows kernel local privilege escalation tracked as CVE-2026-85880.

    Who are the known attackers using BlueMoon?

    At least four hacking groups, including China-aligned state-sponsored actors such as TA412 and UNK_LateNight, are using BlueMoon, according to Proofpoint.

    Are patches available to protect against BlueMoon?

    Yes, all three vulnerabilities exploited by BlueMoon were patched within the past 24 hours of disclosure, but browser and system patch adoption is still catching up across affected organizations.

  • Cardano Short Positions Surge: Could $0.20 Spark a Violent ADA Rebound?

    Cardano Short Positions Surge: Could $0.20 Spark a Violent ADA Rebound?

    Cardano Price Analysis: ADA Holds Key Support as Derivatives Signal Bearish Bias

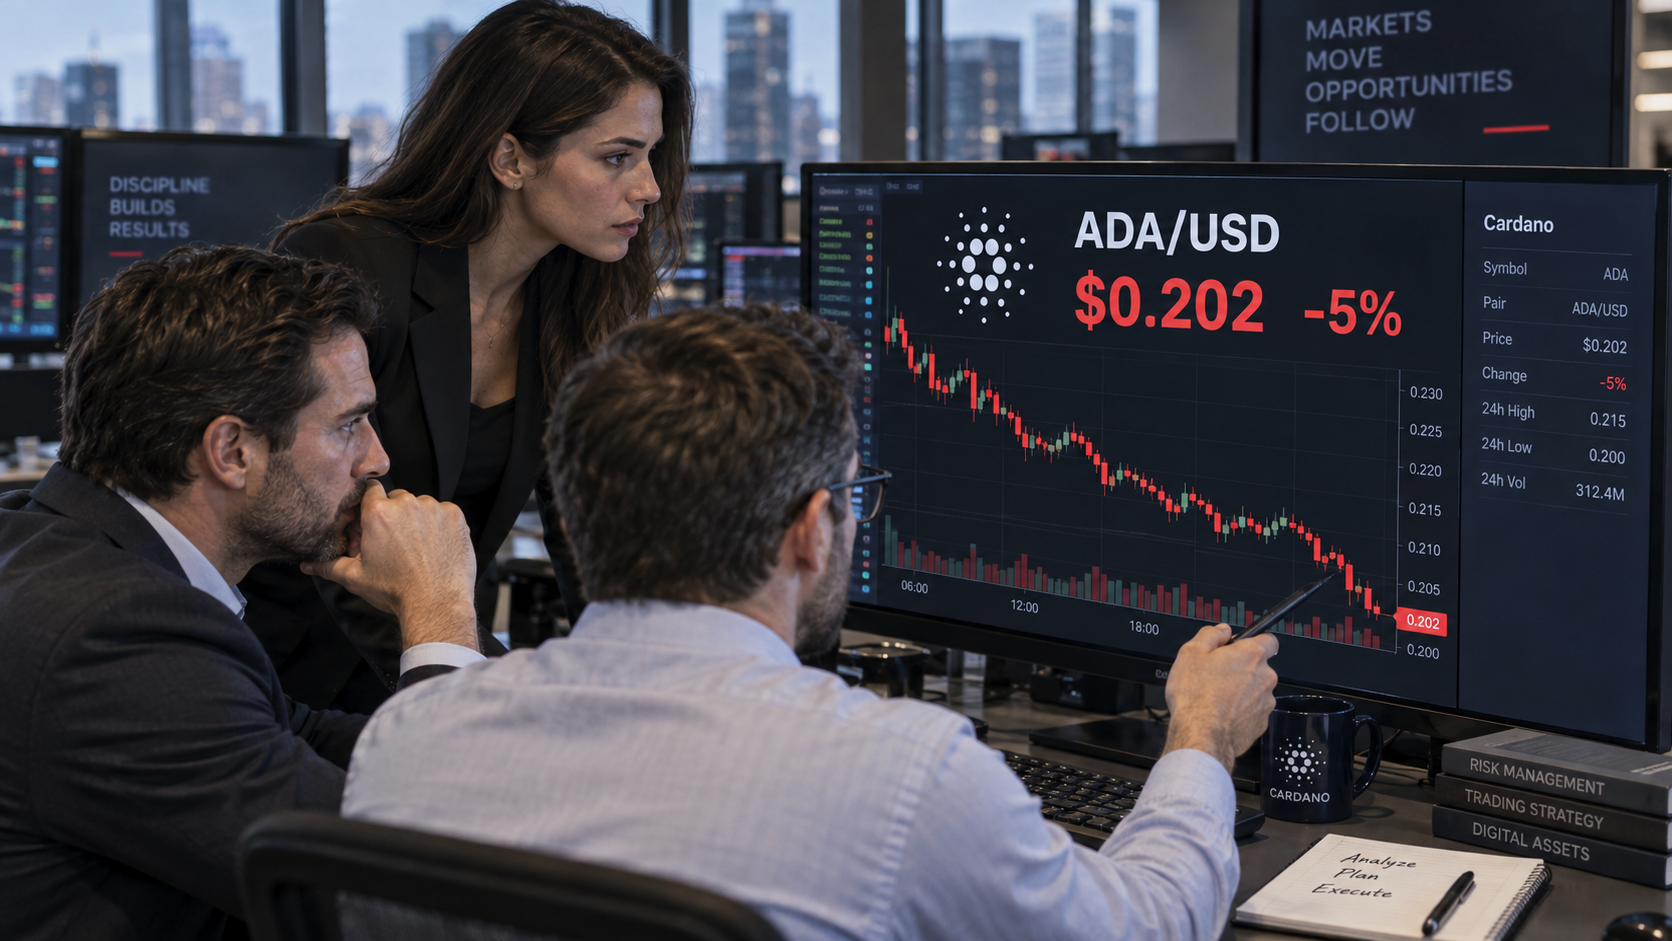
    Cardano (ADA) extended its weekly decline on Friday, trading just above a critical support cluster after shedding more than 8% since the start of the week. Weak derivatives positioning, cautious on-chain signals, and fading momentum point to a bearish near-term outlook, with a decisive close below $0.195–$0.200 potentially opening the door to a deeper correction toward $0.173.

    Derivatives Traders Position for Further Downside

    Cardano’s derivatives market shows traders increasingly betting on additional losses. According to CoinGlass data, ADA’s long-to-short ratio stood at 0.93 on Friday, approaching its lowest level in a month. A reading below 1.0 indicates that short positions outnumber longs, reflecting expectations of further price decline.

    The imbalance suggests leveraged traders remain cautious despite ADA’s modest bounce from weekly lows. Adding to the bearish tone, funding rates turned negative at -0.0006%. Negative funding means short holders are paying long holders, signaling stronger demand for bearish exposure and reinforcing the message from the long-to-short ratio.

    If funding stays negative while ADA tests support, volatility could increase. However, heavily concentrated short positioning also creates conditions for a short squeeze should price rebound sharply.

    On-Chain Activity Rises Without Clear Direction

    CryptoQuant’s market summary paints a similarly cautious picture. Large whale orders are appearing in ADA’s futures market, indicating major traders remain active. Both spot and futures markets show signs of increased activity or “heating,” yet several other metrics remain neutral.

    Together, these readings suggest Cardano traders are becoming more active but have not established a convincingly bullish direction.

    Technical Outlook: ADA Defends Key Moving Averages

    Cardano changed hands around $0.202 on Friday after the 8% weekly slide. Despite the pullback, ADA remains above its 100-day EMA at $0.200 and 50-day EMA at $0.198. These moving averages provide an immediate cushion and preserve a neutral-to-slightly-constructive technical structure, though the broader trend stays constrained by the 200-day EMA near $0.241.

    • RSI: Just below 50, signaling balanced momentum between buyers and sellers.
    • MACD: Slightly negative and below its zero line, indicating weak bullish momentum.

    Upside Barriers

    ADA’s first resistance is the 50% Fibonacci retracement at $0.213. A break above could allow buyers to target the 61.8% retracement at $0.231. Stronger resistance sits between $0.236 and $0.245, a zone that includes the 200-day EMA at $0.241 and could present a substantial challenge. A sustained close above this cluster would be needed to signal a more convincing bullish trend reversal.

    Downside Risks

    Immediate support spans from the 100-day EMA at $0.200 to the 50-day EMA at $0.198, reinforced by the 38.2% Fibonacci retracement at $0.195. A decisive close below this zone would weaken ADA’s technical structure and raise the risk of a move toward $0.173. If selling pressure intensifies, the next major horizontal support lies near $0.150.

  • XRP Leads All Blockchains in 2026 RWA Inflows with $3.6B

    XRP Leads All Blockchains in 2026 RWA Inflows with $3.6B

    XRP Ledger Dominates 2026 Real-World Asset Inflows with $3.6 Billion

    The XRP Ledger (XRPL) has recorded the largest real-world asset (RWA) inflow of any blockchain network in 2026, according to data from RWA.xyz, a leading provider of tokenized RWA analytics. The network has attracted $3.6 billion in RWA inflows since the beginning of the year, placing it at the top of the global rankings for 2026.

    XRP Leads Global RWA Rankings Despite Price Weakness

    This milestone comes even as XRP’s price has fallen 27.19% year-to-date, despite an August rebound, while the broader cryptocurrency market remains in a bear phase. The divergence highlights a notable trend: capital continues to flow into the XRPL’s RWA ecosystem even as the native token’s market performance struggles.

    For context, the $3.6 billion inflow puts XRPL approximately $1 billion ahead of BNB Chain, which ranks second with $2.6 billion. Stellar follows in third with $2.5 billion, while Solana takes fourth with $2.2 billion. Ethereum ranks fifth with $1.2 billion, giving XRPL a $2.4 billion lead over the largest smart-contract platform in 2026 RWA inflows.

    2026 Growth Surges 16x Over 2025 Levels

    The network has already surpassed its full-year 2025 RWA inflow record by more than 16 times, with three months remaining in 2026. At the start of 2025, the XRP ecosystem’s RWA market stood at just $5 million, growing to $226.8 million by year-end — an increase of $221 million. By comparison, the $3.6 billion added in 2026 represents a 16.2x multiple of the previous year’s total growth.

    Importantly, the $3.6 billion figure excludes stablecoins. The XRPL’s stablecoin market has grown by more than $1 billion this year, driven largely by RLUSD. When stablecoins are included, the network’s total tokenized-asset growth is even more substantial.

    JMWH and CRX Digital Assets Drive 89% of Non-Stablecoin Growth

    Excluding stablecoins, commodities and asset-backed credit account for the vast majority of XRPL’s RWA expansion. Two key issuers dominate:

    • Justoken’s JMWH has contributed $2.229 billion in tokenized commodities.
    • CRX Digital Assets has added approximately $1 billion in asset-backed credit.

    Together, these two asset classes represent $3.229 billion — or 89% of the total $3.6 billion in non-stablecoin RWA inflows. This diversification beyond stablecoins gives the XRPL a broader base of institutional and real-world asset activity.

    Total Flows Reach $4.4 Billion With Stablecoins; Ranking Shifts

    When stablecoins are factored in, total year-to-date flows on the XRPL rise to $4.4 billion, reflecting nearly $1 billion in stablecoin growth led by RLUSD. However, including stablecoins changes the competitive landscape: at $4.4 billion, XRPL ranks third globally in total 2026 flows.

    TRON leads with $11.9 billion, followed by HyperEVM at $6 billion. The shift underscores the outsized role stablecoins play in aggregate flow metrics, while XRPL’s lead in non-stablecoin RWAs remains unchallenged.

  • 125B SHIB Tokens Leave BitGo as Price Tests $0.00000515 Support

    125B SHIB Tokens Leave BitGo as Price Tests $0.00000515 Support

    Shiba Inu Tests Critical $0.00000515 Support as 125.33 Billion SHIB Tokens Move from BitGo

    Shiba Inu ($SHIB) is trading near a pivotal technical level as a significant on-chain transfer adds a fresh catalyst to the price action. As of early September 11, 2026, the token is priced at approximately $0.00000510, testing the key $0.00000515 support zone, which aligns with the 0.5 Fibonacci retracement level.

    Technical Setup: Can $SHIB Defend $0.00000515?

    The token recently closed near the $0.00000503–$0.00000504 range on September 10 and is attempting a modest recovery. The ability to reclaim and hold above $0.00000515 with active buying pressure will determine whether the current recovery structure remains intact.

    If support holds, the next major upside target is $0.00000583, followed by the $0.0000059–$0.00000615 fair value gap (FVG). A sustained breakout above this FVG would reinforce bullish momentum and bring the $0.00000670 level into focus as the next significant resistance.

    Source: TradingView

    125.33 Billion SHIB Transfer from BitGo Adds On-Chain Catalyst

    On September 10, exactly 125,334,083,223 $SHIB tokens—valued at approximately $678,000—were transferred from a BitGo-affiliated wallet to a newly created address. The receiving wallet continues to hold the full amount.

    Notably, this transaction was not an exchange deposit, making its immediate impact on selling pressure ambiguous. The move reverses a recent trend of large SHIB inflows into BitGo and coincides with net exchange outflows totaling roughly 160 billion SHIB over the prior 24 hours. Analysts suggest the transfer may reflect an OTC settlement or custody change rather than preparation for market selling.

    Downside Risk: Key Levels to Watch if Support Fails

    At press time, SHIB trades at $0.000005083, down 2.71% in the last 24 hours. If buyers fail to defend the current zone, the first critical downside level is $0.00000492. A break below this mark would weaken the recovery structure and expose $0.00000455 as the next support.

    Further downside below $0.00000455 would undermine the bullish case significantly. However, the most important level remains $0.00000409. A clear break below this threshold would signal a failure of the bullish recovery and negate much of the recent technical structure, reducing the likelihood of a return toward $0.00000583 and the FVG zone.

    Source: CoinMarketCap

    Summary of Key Price Levels

    • Immediate Support: $0.00000515 (0.5 Fibonacci)
    • First Upside Target: $0.00000583
    • Major Resistance Zone (FVG): $0.0000059–$0.00000615
    • Extended Target: $0.00000670
    • First Downside Risk: $0.00000492
    • Secondary Support: $0.00000455
    • Recovery Invalidator: $0.00000409

    Traders are now monitoring whether SHIB can defend the $0.00000515 level and convert the BitGo-related on-chain activity into sustained buying interest. The next 24–48 hours will be decisive for the token’s near-term trajectory.

  • Bitcoin Price Analysis: BTC Drops Below $75K After $82K Rejection

    Bitcoin Price Analysis: BTC Drops Below $75K After $82K Rejection

    Bitcoin Tests Critical Daily Support After $82,000 Rejection Amid Global Market Pressure

    Bitcoin is approaching a decisive technical juncture after failing to sustain its September advance above $82,000. The cryptocurrency has pulled back to approximately $76,900 as sellers regained control following the latest rejection at resistance.

    Daily Structure Faces Key Test at Change in State of Delivery

    The retreat has brought Bitcoin back toward a crucial area on the daily chart. The previous advance followed roughly 32 days of upward price delivery from the August low near $62,200, but momentum has now weakened significantly.

    Price is currently testing a daily Change in State of Delivery (CISD) near $77,150. A decisive move around this level could determine whether the recent rally remains intact or shifts into a deeper corrective phase. The CISD matters because it marks a potential change in the direction of daily price delivery. A decisive close below that level would confirm weakening short-term structure, a risk that has become more pronounced after Bitcoin briefly traded above $82,000 on September 3 before retreating.

    Key Technical Levels Define Near-Term Outlook

    The chart now places $81,468 as nearby resistance, while the broader trading range remains between $76,000 and $82,000. As a result, the $76,000 level has emerged as a key technical threshold. A firm break below it would strengthen the bearish outlook and increase the risk of a deeper decline.

    The current support area is particularly important. A confirmed loss of the $76,000-$77,000 region would place $75,000 as the first major downside test. Lower chart levels then become increasingly relevant. The 0.5 Fibonacci retracement sits near $72,000, while the 0.62 retracement lies around $69,500-$70,000. The chart also highlights liquidity around the broader $69,000 area. These levels represent deeper retracements of the August-to-September rally rather than guaranteed destinations. Their importance would increase only after a confirmed daily structural breakdown.

    The current setup centers on whether the previous 32-day upward delivery remains intact. A sustained loss of support would mark a clear deterioration from that earlier structure.

    Global Macro Pressure Adds Weight to Technical Test

    The technical test is unfolding alongside broader pressure across global markets. Japan’s Nikkei fell 2.2% Friday as Japanese government bond yields continued rising. The 10-year JGB yield climbed to 2.98%, while Brent crude briefly reached $109.97. The U.S. 10-year Treasury yield also touched 4.979%.

    Meanwhile, the Bank of Japan is expected to raise its policy rate by 25 basis points to 1.25% next week. Higher Japanese rates reduce the attractiveness of yen-funded carry trades. Reuters has previously linked yen strength with concerns about carry-trade unwinding and tighter liquidity conditions. Those developments add pressure to risk assets while Bitcoin remains close to technical support.

    Bullish Scenario Requires Reclaim of Key Levels

    However, the downside scenario still requires confirmation. Holding the $76,000-$77,000 region would preserve the possibility of another consolidation or accumulation phase. A recovery above $80,000 would provide the first sign that buyers are regaining control.

    In such a scenario, the next resistance levels would remain at $81,468 and the broader $82,000 zone. A sustained break above $82,000 would restore the upward structure that weakened after the September rejection. The chart does not directly confirm $100,000 as an immediate target, though that level remains a longer-term psychological objective if upward momentum returns.

    For now, daily closes around $76,000-$77,000 remain the key signal. They will determine whether the rejection develops below $75,000 or stabilizes before another recovery attempt.

  • Bitcoin Price Surges Despite Hot US Inflation Data

    Bitcoin Price Surges Despite Hot US Inflation Data

    Bitcoin Price Spikes, Shrugs Off Hot US Inflation Data

    Bitcoin’s price rose on Friday despite data revealing that U.S. inflation had accelerated, defying typical market expectations that higher inflation would pressure risk assets.

    Bitcoin Trades Near $79,000 Amid Inflation Surprise

    The largest cryptocurrency by market capitalization was recently trading close to $78,749 after jumping 2% over a 24-hour period. At one point on Friday morning in New York, bitcoin rose as high as $79,607.

    The price spike came after the release of August consumer price index data showing U.S. consumer prices accelerated, reinforcing expectations that the Federal Reserve will raise interest rates at its meeting next week.

    Core Inflation Exceeds Forecasts

    The consumer price index, excluding food and energy, climbed 0.3% in August from a month earlier, which was higher than expected. Inflation in the U.S. has been difficult to tame due to the war with Iran, which has lifted oil prices, in turn raising the costs of food, gasoline, and other goods.

    Higher inflation typically means the Federal Reserve will raise interest rates, which in turn could stop bitcoin’s price climbing higher. According to CME’s FedWatch tool, traders think there is an 85% chance interest rates will be higher by next week.

    Fed Policy Outlook and Bitcoin’s Rate Sensitivity

    Bitcoin has typically performed well in a low interest rate environment because it means people can buy more of the cryptocurrency with increased liquidity. The Federal Reserve will meet next week and reveal what it will do with borrowing costs.

    Federal Reserve Chairman Kevin Warsh, who took the helm in January, last month gave his first speech as head of the U.S. central bank and said he had more work to do to fight inflation.

    Political Context: Affordability Crisis and Midterm Elections

    The U.S. is currently in the grips of an affordability crisis and rising oil prices are a hot topic ahead of the midterm elections. U.S. President Donald Trump has reassured voters that prices will get under control and repeatedly put pressure on the central bank to lower interest rates.

    Recent Catalysts: Regulatory Clarity and Treasury Policy

    Bitcoin in August had its biggest run in years following positive regulatory news and an announcement from the U.S. Treasury. Treasury Secretary Scott Bessent announced the department would double the size of its long-dated bond buybacks, helping non-yielding assets like bitcoin and gold. The cryptocurrency then benefited from President Trump urging lawmakers to get key crypto legislation, the Clarity Act, over the line.

    This post first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.

  • Treasury Buys $5.2 Billion in Bonds as Bitcoin ETF Flows Remain Negative

    Treasury Buys $5.2 Billion in Bonds as Bitcoin ETF Flows Remain Negative

    Treasury Buyback Targets Off-the-Run Liquidity as Yields Climb

    The U.S. Treasury purchased $5.187 billion of long-dated government bonds on Sept. 10, marking the first operation under its expanded buyback program. The move came as Bitcoin investors monitored markets for signs of improving liquidity, but initial cross-market signals pointed in the opposite direction.

    Treasury’s daily nominal yield curve showed the 10-year yield rising 12 basis points from 4.83% to 4.95%. The real yield curve, which adjusts for expected inflation, saw the 10-year real yield climb 9 basis points from 2.46% to 2.55%. Higher real yields increase the return hurdle for non-yielding assets like Bitcoin. Simultaneously, U.S. spot Bitcoin ETFs recorded another net outflow of roughly $282 million, underscoring that regulated-fund demand and broader financing costs remained unfavorable.

    Operation Details and Market Mechanics

    The buyback targeted off-the-run securities—older Treasury issues that trade less actively than the newest benchmark bonds. Treasury’s official results showed $10.489 billion of securities offered against a $6 billion maximum, with 23 of 40 eligible issues accepted. Maturities ranged from February 2037 through August 2046.

    The $6 billion figure was a ceiling. Treasury describes itself as a price-sensitive buyer in its buyback guidance, allowing it to accept less than the maximum when offers do not meet its criteria. Accepted securities are retired after settlement, managing the composition of Treasury’s own debt rather than conducting a Federal Reserve monetary-policy purchase.

    Research from the Federal Reserve Bank of New York explains that off-the-run bonds trade less frequently, rely more on dealer intermediation, and can benefit from a predictable buyer. The study also characterizes the program as modest relative to overall Treasury market volumes and dealer holdings. The accepted amount demonstrates the operation found more than $5 billion of eligible offers at acceptable prices, though it does not establish whether bid-ask spreads, dealer capacity, or economy-wide financing costs improved—those outcomes require separate market evidence.

    Bitcoin ETF Outflows Persist

    U.S. spot Bitcoin ETFs recorded a net outflow of $282.7 million on Sept. 10, according to Farside Investors. ETF flows signal demand through regulated funds rather than proving one-for-one selling in the spot market. Even with that caveat, the latest outflow offered no evidence that easier conditions were reaching Bitcoin funds.

    CryptoSlate’s Bitcoin market page recorded a Sept. 10 reference close of $76,568 before recovering to around $77,800 at press time. That rebound left the asset near the $76,000 support cluster identified in recent market coverage, while real yields and ETF flows still pointed to pressure.

    Concurrent Macro Forces Complicate Causal Reading

    The buyback shared the session with several macro forces that influence bond yields and risk appetite, preventing a clean causal reading of the Treasury operation. The Bureau of Labor Statistics reported final-demand producer prices rose 0.4% in August and 5.4% year-over-year. Goods prices increased 1.1%, led partly by a 4.2% rise in energy. Persistent pipeline inflation can keep market rates elevated as investors demand more compensation for inflation risk and anticipate tighter monetary policy.

    The European Central Bank added another tightening signal by raising its three key rates 25 basis points on Sept. 10. It also noted its asset-purchase and pandemic-program portfolios continued to decline as maturing principal was no longer reinvested.

    August U.S. consumer inflation data is scheduled for 8:30 a.m. ET on Sept. 11, according to the BLS release calendar. That release is the next immediate test: inflation data consistent with cooling price pressure could pull nominal and real yields lower, while an upside surprise could extend the higher-yield backdrop.

    Transmission Signals Needed for Convincing Case

    CryptoSlate’s analysis identified accepted purchases and subsequent funding conditions—rather than the headline ceiling—as the meaningful test. The completed purchase supplies the first half of that test; the second half must come from markets.

    A convincing transmission signal would combine lower real yields with evidence that easier cash conditions persist beyond settlement. Renewed spot Bitcoin ETF inflows across more than one session would add demand-side confirmation. Bitcoin holding above the recent support cluster while those macro and flow measures improve would strengthen the case further.

    Conversely, a continued squeeze would produce the reverse pattern: elevated real yields, repeated ETF outflows, and Bitcoin losing support while Treasury continues buying selected off-the-run bonds. Each indicator can move for its own reasons, so the case depends on alignment rather than any single print.

    Treasury’s purchase may improve liquidity in a specific corner of the government-bond market. The first post-operation readings showed that benefit had yet to appear in the financial conditions most relevant to Bitcoin.

    Related Reading

    Bitcoin traders bet borrowed money on a rally as oil surges ahead of Friday’s inflation test

  • Riot Games Holds Sponsorship Talks With Polymarket, Kalshi

    Riot Games Holds Sponsorship Talks With Polymarket, Kalshi

    Riot Games Explores Prediction Market Sponsorships Ahead of League of Legends World Championship

    Riot Games has entered discussions with prediction market operators Kalshi and Polymarket regarding potential esports sponsorship agreements, according to a Bloomberg report published on September 11. The talks come weeks before the League of Legends World Championship kicks off in October.

    Riot Evaluates Emerging Prediction Market Space

    The Tencent-owned developer, which operates competitive tournaments for League of Legends and Valorant, has not committed to either platform. Sources familiar with the private discussions told Bloomberg that any agreement would involve Riot’s esports business.

    “Prediction markets are an emerging space that we’re evaluating with a focus on safeguarding competitive integrity, potential value for teams, impact on the fan experience, and alignment with our broader ecosystem goals,” Riot Games spokesperson Joe Hixson told Bloomberg.

    Kalshi declined to comment on the discussions, while Polymarket did not respond to Bloomberg’s request for comment.

    Official Esports Data Requirement Through GRID

    Any prediction market sponsor approved by Riot would be required to obtain official betting data through GRID Esports, one person familiar with the discussions told Bloomberg. GRID already maintains ties to Polymarket, having partnered with the prediction market operator in June. That agreement granted Polymarket access to official esports data and included plans for faster streams, a redesigned esports section, and data taken directly from game servers.

    The requirement would place official game data within any sponsorship arrangement as Riot considers bringing prediction markets closer to its competitive ecosystem.

    Massive Esports Betting Market Drives Interest

    League of Legends and Valorant tournaments draw millions of viewers globally, with esports audiences skewing younger than those of traditional sports. Riot has previously cited Sportradar data showing betting tied to its two major titles reached $10.7 billion in 2024. Most of that activity took place through unregulated markets and unlicensed bookmakers, according to Riot.

    The company began permitting sponsorships from traditional sports betting operators in 2025, subject to restrictions intended to protect competitive integrity. Prediction markets already offer contracts on esports matches, allowing traders to take positions on game outcomes without a formal sponsorship relationship with Riot.

    Kalshi has been recruiting for an esports-focused position tasked with forming league partnerships and increasing its presence in the sector. Polymarket had employees working on esports by at least 2025, according to LinkedIn information cited by Bloomberg.

    Prediction Markets Expand Across Professional Sports

    The Riot discussions would extend a series of deals bringing prediction markets into professional sports and entertainment. At the end of August, Kalshi secured an exclusive U.S. Open partnership with the U.S. Tennis Association. The agreement gave the company prediction market partner status and restricted competing platforms from advertising at the tournament venue and across its television coverage.

    Kalshi had already gained FIFA World Cup exposure through an agreement with ADI Predictstreet, FIFA’s official prediction market partner for the 2026 tournament. The World Cup partnership placed Kalshi branding alongside ADI Predictstreet across stadium, television and digital coverage during the competition.

    Polymarket has pursued a similar strategy, signing agreements spanning Major League Baseball, the Bundesliga and other sports properties. Its Bundesliga agreement made Polymarket the league’s exclusive U.S. prediction market partner and included the use of market data during pay-per-view programming.

    NBA star LeBron James became one of the latest prominent athletes connected with the company when he confirmed a Polymarket partnership through a video posted on X on September 5. The initial campaign is expected to focus on American football, according to CNBC.

    Record Trading Volumes Fuel Competition

    Prediction market operators have been competing for sports users as trading activity across the sector has climbed. Combined monthly volume across Kalshi, Polymarket and Polymarket US reached a record $50.59 billion in July, with Kalshi accounting for $37.7 billion.

    Integrity Concerns Shape Riot’s Evaluation

    Riot’s consideration of prediction market sponsors comes as sports organizations take different positions on partnerships with the sector. The National Football League has held back from signing prediction market sponsorships, citing concerns over inadequate regulation and ongoing legal challenges, Bloomberg reported earlier this month.

    Riot has its own concerns because betting activity can create integrity risks around professional matches. Its evaluation of prediction markets is therefore considering competitive integrity alongside the possible financial benefits for esports teams and effects on fans, according to Hixson.

    Sponsorship income remains an important source of revenue for esports organizations. NewZoo estimates that sponsorships can account for as much as 60% of an organization’s revenue, while the industry has historically struggled to generate sufficient income from merchandise and ticket sales.

    Prediction market companies have spent heavily to place their brands around major sporting events while developing systems intended to detect prohibited trading. Kalshi uses its proprietary Poirot detection system and has worked with Solidus Labs, IC360 and the Wharton Forensic Analytics Lab on surveillance and integrity controls. Polymarket has developed Vergence AI, an integrity monitoring system created with support from Palantir and TWG AI.

    Regulatory Battles Continue Across States

    Sports contracts remain one of the main sources of regulatory pressure on Kalshi and Polymarket in the United States. State gaming regulators and attorneys general have argued that contracts tied to game winners, player statistics and other sporting outcomes amount to sports betting and should fall under state gambling laws. Prediction market operators have countered that their event contracts are derivatives subject to federal oversight.

    The dispute has produced different outcomes across U.S. courts. A Washington state judge in July granted a preliminary injunction blocking Kalshi from offering sports prediction markets to residents after finding the state was likely to succeed in arguing that the products violated local gambling laws. Kalshi has faced similar challenges in New York and Michigan, while lawsuits involving prediction market regulation have spread across numerous states.

    Baltimore sued both Kalshi and Polymarket in August, accusing the companies of offering unlicensed sports betting. The city’s case against Kalshi named Coinbase, Robinhood and Webull over their role in distributing sports event contracts.

    Despite the legal disputes, sports have become a major source of activity for prediction markets. During the 2026 FIFA World Cup, monthly sports prediction volume reached $9.5 billion on Kalshi and $5.3 billion on Polymarket, according to Defirate data reported in June.

    Riot’s discussions are taking place weeks before the League of Legends World Championship begins in October. No sponsorship agreement with either Kalshi or Polymarket has been announced.

  • Bitcoin Trades Now Face Liquidation Risk After a Stock Crash

    Bitcoin Trades Now Face Liquidation Risk After a Stock Crash

    RWA Perpetual Futures Volume Surges to $799.5 Billion

    Monthly volume on real-world-asset (RWA) perpetual futures climbed from $85 billion in January to a record $799.5 billion in August, with equities representing 62.3% of that total across both decentralized and centralized venues, according to CoinMarketCap data.

    Unified Portfolio Margin Reshapes DeFi Trading

    Trading venues are shifting away from single-asset margin models toward unified portfolio accounts. In this structure, a trader’s entire holdings collateralize every position simultaneously, moving well beyond the traditional single stablecoin deposit.

    DeFi trading originally required depositing USDC as margin for crypto perpetuals. Hyperliquid’s portfolio margin now allows spot balances and perpetual positions to offset each other directly, with assets like HYPE and BTC eligible as non-stablecoin collateral. Backpack expanded this pool on September 3 by adding equity holdings, enabling shares in SPCX to support perpetual trades, dollar borrowing, and spot-margin positions within one unified account. Synthetix built a dedicated liquidity vault this year to handle ETH-denominated collateral, market-making, and liquidations in concert.

    Katana CEO Matthew Fisher said that unified margin adds leverage to the system. He argued that it also lets sophisticated trading firms net risk across an entire book, turning the same tool into something that can support genuine hedging alongside larger directional bets.

    Collateral Risk: A Second Liquidation Trigger

    A stablecoin-margined Bitcoin long carries only BTC’s price as the risk variable. Fisher’s point is that collateral built from anything else introduces a second, independent trigger.

    If Bitcoin falls, the position loses money as expected. If the collateral backing that position falls instead, the margin ratio deteriorates on its own, even with Bitcoin unchanged. Fisher described a trader who can end up liquidated while the underlying derivative is still profitable, purely because the asset propping it up has dropped far enough.

    Fisher frames adding yield-bearing collateral as reconciling two separate clocks. Yield accrues on a smooth, near-continuous schedule, while the asset’s price still moves tick by tick, and the margin engine has to stay accurate about both at the moment a liquidation might trigger.

    Liquidation Challenges: Pricing vs. Selling

    Every crypto venue can already tell a trader what their tokenized gold, staked ETH, or equity position is worth at any given moment, but Fisher noted that knowing the price solves only half the problem.

    He said:

    “The challenge is basically liquidating the new collateral safely.”

    Even an asset as liquid as Bitcoin or gold needs a route into a stable settlement asset that works quickly and without meaningful slippage once a forced sale begins. That distinction between knowing what something is worth and being able to sell enough of it fast enough is where Hyperliquid’s design becomes evident. Its documentation routes portfolio-margin liquidations through a dedicated backstop liquidator, a different track from the ordinary market process used for perpetuals.

    Seized collateral converts through a time-weighted average price with a 10-minute half-life, because spot order books have less consistent liquidity than perpetual markets. Synthetix built its liquidity vault around the identical problem, assigning it the combined role of market maker, liquidator, and collateral converter for every non-stablecoin asset it accepts.

    Real-World Test: SK Hynix Incident Exposes Weakness

    Galaxy’s research on an August incident described a Seoul pre-market print for SK Hynix that came in 29.96% below the prior close and fed directly into a tokenized perpetual contract margined in USDC on Hyperliquid. That triggered roughly $60 million of leveraged long liquidations across nearly a thousand accounts. Galaxy concludes that correct price discovery is not the same as sound liquidation design.

    Fisher expects DeFi to eventually rediscover the same collateral hierarchy traditional finance built over decades: cash first, then government debt, high-quality credit, other debt, equities, and only then more volatile or illiquid assets. Wrapping something in an ERC-20 standard makes it transferable, though it says nothing about how that asset behaves under real selling stress. What determines an asset’s place on that ladder remains the same two things traditional finance has always weighed: volatility and how easily it can be sold once a sale becomes mandatory.

    TradFi’s Collateral Hierarchy vs. DeFi Innovation

    Fisher’s read on the competitive landscape runs counter to the usual crypto assumption that DeFi always innovates first and traditional finance follows years later. Banks and prime brokers have accepted securities, gold, and money-market fund shares as collateral for decades, complete with established haircut methodologies and stress-testing frameworks. Tokenization functions as an infrastructure upgrade to a practice institutions already run, well short of a new discipline they need to learn from scratch.

    Recent moves support that reading. Nasdaq has agreed to invest $100 million in Kraken parent Payward to help build infrastructure for tokenized assets trading outside conventional market hours, and US market plumbing is separately extending toward round-the-clock clearing and settlement.

    The Collateral Arms Race: Bull and Bear Cases

    The bull case sees RWA perpetual volume continuing to grow, tokenized Treasuries and equities building genuinely deep order books, and backstop liquidation vaults proving they can convert seized collateral profitably through real stress events. Under that path, decentralized exchanges come to resemble on-chain prime brokers, offering spot holdings, perpetuals, lending, and collateral management inside one account. Bitcoin benefits directly, since traders can hold it spot while shorting perpetuals or borrowing against it without ever selling.

    The bear case envisions a crowded trade that reverses sharply with collateral assets gapping down together. Spot order books prove unable to absorb seized positions anywhere near their oracle-marked value, echoing what happened during the SK Hynix incident at far larger scale.

    That risk sits more concentrated than headline volume implies. DEX share of RWA perpetual trading fell from roughly 45% in December to just 13% by August. Hyperliquid’s HIP-3 markets carry most of the remaining DeFi share, with a single deployer behind nearly all of that volume. In that scenario, venues cut loan-to-value ratios, shrink collateral caps, and retreat toward stablecoin-first margin. Bitcoin ends up absorbing much of the shock anyway, since forced liquidations in less liquid collateral often settle through crypto’s deepest, most liquid derivatives market, regardless of where the stress began.

    The harder question for DeFi now is whether it can sell a tokenized asset fast enough, at scale, the one moment it has to.