Tag: $USDe

  • Ethena Unlocks $150T Market, Benefiting USDe Holders

    Ethena Unlocks $150T Market, Benefiting USDe Holders

    Key Highlights

    • Ethena launched its RWA basis trading expansion on Binance, utilizing bStocks and USDT-denominated perpetuals to target an 11% average yield—nearly double short-term U.S. Treasury returns.
    • The protocol’s basis trade allocation has surged from 1% during the 2024 crypto winter to approximately 20% of $USDe’s yield backing, with Ethena projecting the equity perpetuals market to dwarf the $15B+ crypto perpetuals opportunity.
    • $ENA token rallied 105% in two weeks (from $0.13 to $0.28) as analysts anticipate $USDe’s $4.8B supply growth will drive value accrual to the governance token.

    Ethena Activates RWA Basis Trading on Binance to Unlock Equity Perpetuals Yield

    Ethena Labs officially commenced its real-world asset (RWA) basis trading expansion on Friday, deploying $USDe reserve capital onto the Binance exchange to capture equity perpetual funding rates. In a statement, the protocol described the move into equity and RWA perpetuals as the “Most exciting update to the $USDe collateral backing since launch.” The initiative follows final plans announced last month, positioning Ethena to access a total addressable market exceeding $150 trillion—vastly larger than the $2.5 trillion crypto derivatives landscape.

    Mechanics of the Binance Equity Basis Trade

    Under the arrangement, Ethena will execute delta-neutral basis trades using Binance’s bStocks—spot-tokenized equities and exchange-traded funds—paired with USDT-denominated perpetual futures contracts on the same underlying assets. A basis trade involves simultaneously buying the spot asset and shorting its equivalent perpetual future to harvest the funding rate and price differential. According to Ethena, this specific equity basis trade on Binance has delivered an average annualized return of 11% over the past six months, nearly doubling the yield available on short-term U.S. Treasury bills.

    Binance was selected as the inaugural venue for several structural advantages. The exchange’s equity perpetuals market has demonstrated 30% month-over-month growth, and critically, Binance offers lower auto-deleveraging (ADL) priority for eligible delta-neutral accounts—including Ethena’s—adding a meaningful layer of risk mitigation for $USDe holders.

    $USDe Reserve Diversification Strategy and Competitive Positioning

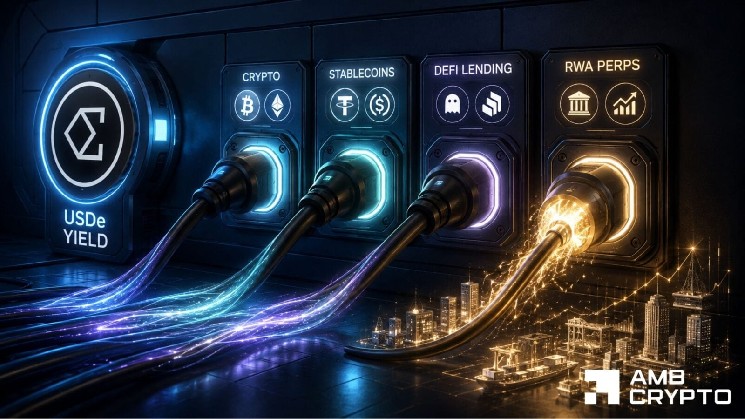
    $USDe, Ethena’s synthetic dollar, functions as a yield-bearing stablecoin that redistributes a portion of reserve earnings back to holders. Unlike Circle’s USDC or Tether’s USDT, which concentrate reserves almost exclusively in U.S. Treasuries yielding approximately 4% and retain nearly all interest income, Ethena diversifies across multiple yield sources. These include DeFi lending protocols such as Aave and Morpho, crypto-native basis trades, institutional bitcoin lending, liquid stablecoins, and syndicated corporate loans (RWA). The equity perpetuals basis trade now represents the latest—and highest-yielding—addition to this diversified reserve stack.

    The shift has been rapid. During the crypto market trough in June and July 2024, basis trades accounted for merely 1% of $USDe’s yield backing. As of publication, that share has climbed toward 20%, and Ethena anticipates the equity perpetuals opportunity will ultimately surpass the $15 billion-plus in crypto perpetuals capacity the protocol captured during the previous market cycle. Total $USDe supply currently stands at $4.8 billion.

    Why This Matters: Stablecoin Yield Wars and Token Value Accrual

    The expansion signals a structural evolution in the stablecoin sector. Traditional fiat-backed stablecoins operate as passive treasury vehicles, capturing the risk-free rate for shareholders. Ethena’s model attempts to compress the spread between institutional-grade yield sources and retail stablecoin holders by tokenizing access to sophisticated basis trades previously reserved for hedge funds and market makers. If successful, this could redefine competitive dynamics, pressuring incumbents to increase yield pass-through or risk capital migration.

    For the $ENA governance token, the thesis centers on value accrual from $USDe supply growth. As the synthetic dollar scales, protocol revenue—derived from the spread between reserve yield and holder distributions—is expected to increase, benefiting $ENA stakers through buybacks or governance-controlled treasury flows. The market has reacted decisively: $ENA appreciated 105% over a two-week window, rallying from $0.13 to $0.28. Sam Ruskin, Investment Associate at Reciprocal Ventures, underscored the sentiment, stating: “There are very, very few projects in crypto with as much potential upside as Ethena.”

    Frequently Asked Questions

    What is a basis trade and how does it generate yield for $USDe?

    A basis trade involves buying a spot asset (such as tokenized stocks via Binance bStocks) while simultaneously shorting the equivalent perpetual futures contract. The strategy captures the funding rate paid by longs to shorts plus any price convergence between spot and futures, generating a market-neutral return. Ethena deploys $USDe reserves into these trades and shares a portion of the profits with $USDe holders.

    How does Ethena’s yield model differ from USDC or USDT?

    USDC and USDT hold reserves primarily in short-term U.S. Treasuries yielding ~4%, with the issuers (Circle and Tether) retaining nearly all interest income as profit. Ethena diversifies $USDe reserves across crypto basis trades, DeFi lending, institutional lending, and now equity perpetuals—targeting yields above 4%—and redistributes a share of that yield directly to $USDe holders.

    What is the relationship between $USDe supply growth and $ENA token value?

    $ENA is the governance and value-accrual token for the Ethena protocol. As $USDe supply expands, the protocol generates more absolute revenue from its reserve yield strategies. This revenue can be directed to $ENA stakers via governance votes, creating a fundamental link between synthetic dollar adoption and governance token valuation. Recent price action—$ENA rising 105% in two weeks—reflects market anticipation of this dynamic.
  • Altcoin Eliminates Token Inflation, Price Surges

    Altcoin Eliminates Token Inflation, Price Surges

    Key Highlights

    • Ethena Protocol will halt all $USDe token incentives and inflation by end of September, marking a full transition to a sustainable yield model.
    • $ENA token price surged to $0.28, leading altcoin gains, as markets reacted to the incentive wind-down and a new Binance partnership.
    • Ethena is expanding its basis trade strategy into tokenized equity markets via Binance-issued bStocks, diversifying $USDe yield sources beyond crypto perpetual futures.

    Ethena Ends $USDe Incentive Program, Shifts to Sustainable Yield Model

    Ethena Labs, the issuer of the synthetic dollar $USDe and governance token $ENA, has confirmed that all token incentives and associated inflation supporting $USDe growth will cease completely by the end of September. The protocol announced that incentive emissions have already been reduced by approximately 85% since the initial airdrop in 2024, and no new tokens will be issued for this purpose moving forward. In a statement, the Ethena team thanked the community of users and liquidity providers whose participation helped $USDe reach its current scale, framing the decision as a deliberate stepping stone to shift the protocol from a growth-promoting phase to a more sustainable, long-term operational model.

    Market Reaction Drives $ENA Price Surge

    The announcement coincided with a sharp rally in the $ENA token. According to data from HTX (formerly Huobi), $ENA emerged as one of the leading performers in the altcoin sector during the session, with its price climbing to $0.28. Market observers attribute the positive price action not only to the clarity provided by the incentive wind-down—which removes future sell pressure from token emissions—but also to a strategic partnership unveiled days earlier that could fundamentally diversify the protocol’s revenue base.

    Strategic Pivot: Expanding Basis Trade into Tokenized Equities

    Binance Partnership Unlocks Traditional Finance Yield

    On September 25, Ethena revealed a collaboration with Binance to expand its core “basis trade” strategy beyond cryptocurrency perpetual futures markets into equity perpetual futures. Under the new framework, Ethena plans to purchase bStocks—tokenized equity certificates issued by Binance-affiliated entities—and hedge the directional risk by shorting USDT-margined perpetual futures on the same underlying equities on the Binance platform. This mechanism aims to capture the funding rate spread between the spot tokenized equity and its perpetual future, effectively porting the protocol’s proven delta-neutral strategy from crypto-native assets into traditional equity indices and stocks.

    Diversifying $USDe’s Return Stack

    The move represents a significant evolution in $USDe’s yield generation. Historically, the synthetic dollar’s returns have been derived almost exclusively from funding rates in cryptocurrency perpetual futures markets (primarily BTC and ETH). By integrating tokenized equities via Binance, Ethena accesses a vastly larger, less correlated pool of funding rate premiums tied to traditional financial markets. This diversification could stabilize $USDe yields during periods of low crypto volatility and reduce the protocol’s concentration risk in digital asset derivatives.

    Why This Matters

    Ethena’s decision to sunset incentives signals a maturation milestone for the largest synthetic dollar protocol in DeFi, which currently manages over $3 billion in $USDe supply. The transition to a zero-inflation model tests whether $USDe can maintain its peg and market share purely on organic yield from basis trades—a critical proof point for the viability of non-custodial, censorship-resistant stablecoins. Simultaneously, the Binance equity integration bridges DeFi with traditional finance (TradFi) infrastructure, leveraging tokenized real-world assets (RWAs) to unlock new yield frontiers. If successful, this template could accelerate institutional adoption of on-chain synthetic dollars and establish a new paradigm for delta-neutral strategies spanning crypto and equity markets. The next key milestone will be the actual deployment of capital into bStocks positions and the resulting impact on $USDe’s yield profile in Q4 2024.

    Frequently Asked Questions

    When do $USDe token incentives officially end?

    All token incentives and inflation for $USDe will cease by the end of September 2024. The protocol confirmed that emissions have already been reduced by roughly 85% since the 2024 airdrop, and no new incentive tokens will be issued after the cutoff.

    How does the new Binance equity basis trade work?

    Ethena will buy bStocks (tokenized equity certificates from Binance-affiliated issuers) and simultaneously short the corresponding USDT-margined perpetual futures on Binance. This delta-neutral position aims to harvest the funding rate premium from equity perpetual futures, adding a TradFi-linked revenue stream to $USDe’s yield.

    What does the incentive wind-down mean for $ENA holders?

    The cessation of token emissions removes a major source of future sell pressure on $ENA, which the market interpreted positively—driving the token to $0.28 and making it a top altcoin gainer. However, $ENA’s long-term value will depend on the protocol’s ability to generate sustainable fee revenue from its expanded basis trade operations to fund buybacks or staking yields.

  • How Far Can USDe’s Yield Scale as Ethena Targets RWA Perpetuals?

    How Far Can USDe’s Yield Scale as Ethena Targets RWA Perpetuals?

    Ethena is expanding the collateral backing for its yield-bearing synthetic dollar, $USDe, into basis trades on equity perpetuals, also known as real-world asset (RWA) tokenization perps.

    Equity perpetuals create a larger basis-yield opportunity

    According to Ethena, the equity perpetuals market has grown tenfold since March, reaching $6 billion in open interest. The project believes the RWA perpetuals market could become 100 times larger, creating a scalable source of basis yield that is less dependent on the cyclical cryptocurrency market.

    The underlying asset base is >$150 trillion compared to ~$2.5 trillion of crypto, making this the most scalable extension of the basis allocation to date. We expect RWA perpetuals to eclipse crypto allocations in $USDe’s backing within 12-24 months.

    Ethena expects RWA perpetuals to outpace crypto-based basis trades as a source of $USDe collateral within one to two years. At present, liquid stablecoins such as USDT and USDC make up the largest share of $USDe’s backing at 32%. DeFi lending is the second-largest reserve category, accounting for 31% across Aave and Morpho.

    Source: Ethena

    Ethena diversifies $USDe’s yield sources

    A basis trade captures the spread between an asset’s spot price and its futures contract, including perpetual futures. However, the strategy is exposed to crypto market cycles. During the peak of the 2024–2025 bull run, $USDe’s supply reached nearly $15 billion, with more than 80% of the supply earning yield. As the crypto winter set in, supply fell to $4 billion and the yield dropped below 0%.

    Source: $USDe market supply (Ethena)

    To reduce its reliance on the crypto market, Ethena first expanded into traditional credit, powered by Janus Henderson. Traditional credit currently represents 12% of $USDe’s backing.

    The RWA perpetuals strategy, which is expected to launch in the next few weeks, would represent the second major stage of Ethena’s diversification plan. Explaining why the project waited before expanding into RWA perpetuals, Ethena founder Guy Young said:

    We took a cautious approach to what was a nascent market and waited until we saw deep, liquid markets with a data history we could study before moving into the opportunity at scale.

    Source: X

    Young added that the segment is “one of the very few 100x left” and could exceed the global cryptocurrency market’s trading volume and open interest within 24 months.

    $USDe yield compared with U.S. Treasury bills

    Compared with its main yield competitor, short-term U.S. Treasury bills, $USDe offered a 1.6% spread. In other words, $USDe could provide a higher yield than U.S. T-bills before accounting for the security risks associated with DeFi.

    Source: Ethena

    Ethena has continued upgrading its ecosystem ahead of the next crypto bull market. Whether the latest expansion of its yield sources will increase demand for $USDe remains to be seen.

  • Ethena Looks Beyond Crypto to Tap Yield From Booming Equity Perpetuals

    Ethena Looks Beyond Crypto to Tap Yield From Booming Equity Perpetuals

    Ethena is expanding its funding trade into equity perpetuals as the protocol seeks new sources of returns after the supply of $USDe fell below $5 billion from a peak of nearly $15 billion.

    The move follows Thursday’s major $ENA token overhaul, when the Ethena Foundation announced changes to $ENA’s token economics. The overhaul eliminates monthly venture capital unlocks and puts to a vote whether revenue from Ethena’s businesses should be used for token buybacks.

    Ethena adapts its funding strategy to equity markets

    The strategy is essentially the same trade Ethena has run since $USDe’s launch: hold exposure to an asset, short its perpetual contract and collect the funding paid by leveraged long traders. The assets involved have included bitcoin $BTC$79,389.75, ether ETH$2,496.79 and solana (SOL).

    However, the trade became far less lucrative in crypto this year as prices plunged and market activity cooled. Ethena said bitcoin $BTC$79,389.75 funding averaged 11% in 2024 and 4.9% in 2025 before falling to just 2.2% this year through Aug. 11.

    Equity perpetuals have shown the opposite trend. According to Ethena, funding was positive on 94% of days on Hyperliquid and 97% of days on Binance once those markets reached meaningful scale. The median equity funding rate was 13.9%, compared with 3.9% for bitcoin.

    “One other interesting characteristic which makes this more attractive versus crypto is the natural positive skew of funding distribution,” co-founder Guy Young said in an X post.