Tag: Metaplanet

  • VanEck Flags Heavy Executive Dilution at Bitcoin Treasury Firm Metaplanet

    VanEck Flags Heavy Executive Dilution at Bitcoin Treasury Firm Metaplanet

    Key Highlights

    • VanEck’s September 2026 Bitcoin ChainCheck flags executive stock-option capacity equal to approximately 22.4% of Metaplanet’s shares outstanding, raising dilution concerns for shareholders.
    • The analysis emphasizes that Metaplanet’s Bitcoin treasury itself remains intact and growing; the scrutiny focuses on capital structure efficiency rather than any sale of Bitcoin holdings.
    • As corporate Bitcoin adoption accelerates in Asia, investors may increasingly evaluate treasury strategies on Bitcoin-per-share accretion net of dilution, not just absolute BTC balances.

    VanEck Spotlights Dilution Risk in Metaplanet’s Bitcoin Treasury Model

    Metaplanet has emerged as one of the most closely watched corporate Bitcoin accumulators outside the United States, but a new analysis from VanEck is directing investor attention toward a less-visible component of the strategy: the equity compensation framework supporting it. In its mid-September 2026 Bitcoin ChainCheck, authored by Matthew Sigel, VanEck highlighted that Metaplanet’s executive stock-option pool represents capacity equivalent to roughly 22.4% of shares outstanding — a figure the firm characterizes as material for a company whose investment thesis increasingly hinges on growing Bitcoin exposure on a per-share basis.

    The Per-Share Math Behind the Headline Holdings

    Corporate Bitcoin strategies are typically discussed in terms of absolute treasury size — how many BTC a company holds. VanEck’s analysis argues that metric alone can obscure a critical dynamic: the denominator. If a firm expands its Bitcoin reserves while simultaneously issuing significant new equity or options, existing shareholders may own a shrinking slice of that treasury even as the headline balance rises. That tension is central to VanEck’s assessment of Metaplanet, where a roughly 15% reduction in executive base salaries sits alongside what the firm describes as substantial equity-based compensation.

    Capital Structure Scrutiny, Not Treasury Critique

    VanEck is explicit that this is not a story about Metaplanet liquidating its Bitcoin. The Japanese firm remains one of Asia’s most aggressive listed Bitcoin accumulators, and the ChainCheck makes clear the criticism targets the capital structure surrounding the treasury, not the treasury itself. The use of stock options to align management with shareholders is standard practice across listed markets; the distinction here is one of scale relative to a strategy explicitly marketed on Bitcoin-per-share growth. When dilution becomes part of the treasury math, VanEck suggests, it warrants the same analytical rigor applied to the acquisition side of the ledger.

    Why This Matters

    As more public companies across Asia and globally adopt Bitcoin treasury strategies, the framework for evaluating them is evolving. Absolute BTC holdings were a sufficient proxy for conviction in the early innings; the next phase of scrutiny will likely center on accretive efficiency — how much Bitcoin per share is actually being added after accounting for share-based compensation, at-the-market offerings, convertible debt, and other dilutive instruments. Metaplanet’s high-profile position makes it a bellwether for how the market prices that trade-off. Investors comparing corporate Bitcoin vehicles may soon demand normalized metrics such as “BTC per fully diluted share” alongside raw treasury totals, pushing boards to optimize capital structure with the same intensity they apply to procurement.

    Frequently Asked Questions

    Is Metaplanet selling its Bitcoin holdings?

    No. VanEck’s analysis explicitly states that Metaplanet is not selling its Bitcoin. The critique focuses on the potential dilution from executive stock options, not on any disposition of the treasury itself.

    What does the 22.4% dilution figure represent?

    The figure represents the total capacity of Metaplanet’s executive stock-option pool as a percentage of shares outstanding, per VanEck’s Bitcoin ChainCheck. It reflects the maximum potential dilution if all options were exercised, not dilution that has already occurred.

    Why does dilution matter for a Bitcoin treasury strategy?

    If a company’s investment thesis is built on increasing Bitcoin exposure per share, issuing new shares or options can erode that per-share gain even while the total Bitcoin balance grows. Shareholders end up owning a smaller fraction of the treasury, which can offset the benefit of additional BTC purchases.

  • VanEck Labels Metaplanet ‘Bad,’ Calls Executive Pay a ‘Shareholder Trap’

    VanEck Labels Metaplanet ‘Bad,’ Calls Executive Pay a ‘Shareholder Trap’

    Key Highlights

    • VanEck rates Metaplanet’s executive compensation “Bad” due to a 14.7% option pool driving shareholder dilution, far exceeding the 4.0% peer average among Digital Asset Treasury companies.
    • Metaplanet’s officer exposure stands at 8.2% (10.4x the 0.8% average) and its largest individual officer position at 3.8% (5.9x the 0.6% average), with no performance conditions beyond continued service.
    • VanEck proposes canceling approximately 273 million shares added via an “Evergreen” mechanism, replacing rights with a smaller shareholder-approved plan tied to Bitcoin per fully diluted share, and adopting a written equity-grant timing policy.

    VanEck Flags Metaplanet’s Executive Compensation as “Bad”

    Global investment manager VanEck has published a comparative analysis of executive compensation across the 10 largest Digital Asset Treasury companies (DATs), placing Metaplanet in the “Bad” category. The firm’s report highlights that Metaplanet’s compensation structure adds to shareholder dilution, citing a 14.7% option pool on a fully diluted basis, officer exposure of 8.2%, and a largest individual officer position of 3.8%.

    Peer Comparison: Strategy, BitMine, and Others Rated “Good”

    By contrast, six peers — Strategy, BitMine, Hyperliquid Strategies, Sharplink, Tron, and Bit Digital — earned a “Good” rating. VanEck attributes this to fixed pools, mandatory shareholder approval for increases, and officer exposure of 1% or less. For context, Strategy maintains a fixed 8.35 million-share pool (approximately 2% of fully diluted shares) with executive exposure of 0.5%. BitMine’s pool sits at 3.2% with officer exposure around 1%. Three companies — Twenty One Capital, Strive, and Forward Industries — were placed in the “Acceptable” band due to weaker safeguards.

    Metaplanet’s Dilution Mechanics and Historical Context

    Often dubbed Japan’s MicroStrategy, Metaplanet’s compensation framework originated when the company was a struggling hotel operator and was designed to protect executive pay from dilution. After its pivot to a Bitcoin treasury strategy, the mechanism remained, allowing the executive option pool to expand as the firm issued shares to fund Bitcoin purchases. By mid‑2026 the pool had reached 319.5 million potential shares (about 20% of the company) on a fully diluted basis. On 18 August 2026 Metaplanet removed the automatic “Evergreen” mechanism but retained the enlarged pool. Then on 11 September it rolled back the conversion ratio to its pre‑September 2025 level, cutting the pool by 41% to 188.2 million shares. However, 82.8 million shares had already been issued to insiders, leaving 105.4 million potential new shares (roughly 7% of the company). Compared with the other nine DATs, Metaplanet’s 14.7% plan pool is 3.7x the 4.0% peer average, officer exposure is 10.4x the 0.8% average, and its largest officer position is 5.9x the 0.6% average. Unlike Strategy, BitMine, and Strive, Metaplanet’s rights carry no performance conditions beyond continued service.

    VanEck’s Proposed Remediation Steps

    To address these concerns, VanEck has outlined four structural changes: first, cancel approximately 273 million shares added through the adjustment mechanism; second, replace the remaining rights with a smaller shareholder‑approved plan; third, link compensation to Bitcoin per fully diluted share; and fourth, adopt a written equity‑grant timing policy. VanEck estimates that, before the recent reductions, management dilution could have absorbed roughly 20% of the economic value created through Bitcoin purchases, leaving shareholders with about 80% in its analysis.

    Market Context: Bitcoin Holdings and Stock Performance

    Metaplanet’s Bitcoin holdings have reached 43,000 BTC, valued at $3.5 billion. The company’s stock traded at ¥243.00 after a 2.10% gain in the most recent session, though it has declined nearly 50% year‑to‑date, amplifying existing investor concerns about dilution and governance.

    Why This Matters

    The VanEck report underscores a growing focus on governance quality within the Digital Asset Treasury sector. As more companies adopt Bitcoin‑centric balance sheets, the alignment of executive incentives with shareholder value becomes critical. Metaplanet’s legacy compensation structure — designed for a different business model — illustrates how unchanged mechanisms can lead to excessive dilution, eroding the very value creation that the treasury strategy aims to deliver. The peer group’s “Good” ratings demonstrate that fixed pools, shareholder approval gates, and performance‑linked grants are achievable standards. VanEck’s specific remediation proposals provide a concrete roadmap for Metaplanet and a benchmark for other DATs evaluating their own compensation frameworks.

    Frequently Asked Questions

    Why did VanEck rate Metaplanet’s executive compensation “Bad”?
    VanEck assigned the “Bad” rating because Metaplanet’s 14.7% option pool is 3.7 times the peer average, officer exposure is 10.4 times the average, and its largest officer position is 5.9 times the average. Additionally, the rights lack performance conditions beyond continued service.
    What is the “Evergreen” mechanism and what did Metaplanet do about it?
    The “Evergreen” mechanism automatically increased the option pool as the company issued shares. Metaplanet removed this automatic feature on 18 August 2026 but retained the enlarged pool that had already accumulated.
    What changes does VanEck propose for Metaplanet?
    VanEck recommends canceling roughly 273 million shares added via the adjustment mechanism, replacing the remaining rights with a smaller shareholder‑approved plan, linking compensation to Bitcoin per fully diluted share, and implementing a written equity‑grant timing policy.
  • Corporate Treasuries Bought Only 5,900 Bitcoin in Three Months as Demand Signals Weaken

    Corporate Treasuries Bought Only 5,900 Bitcoin in Three Months as Demand Signals Weaken

    Key Highlights:

    • Corporate treasuries hold ~1.22 million BTC with an average cost basis of $80.5K, leaving them ~6% underwater at current prices.
    • Strategy (formerly MicroStrategy) dominates with ~845,050 BTC; Tokyo-listed Metaplanet ranks among the next-largest holders.
    • U.S. spot Bitcoin ETFs have drawn billions since August but remain ~$1 billion negative year-to-date, while the Coinbase premium stays mostly negative, signaling weaker U.S. demand versus offshore markets.

    Corporate Treasury Bitcoin Holdings Sit Underwater as Buying Momentum Stalls

    Corporate treasuries that drove significant Bitcoin accumulation through 2025 have abruptly stepped back, leaving their aggregate position underwater at current market levels. According to on-chain analytics firm Glassnode, the cohort’s average entry price—termed the Corporate Treasury Cost Basis—stands at $80,500, approximately 6% above spot. Bitcoin briefly reclaimed that level in recent sessions but failed to sustain gains, reinforcing the $80.5K threshold as a technical ceiling.

    “Corporate treasuries were a big buyer through 2025, and they have stepped back,” Glassnode said. “Their average entry, the Corporate Treasury Cost Basis, sits at $80.5K, about 6% above spot, so the group as a whole is under water.”

    Data from Bitcoin Treasuries confirms the scale of institutional exposure: public companies collectively hold roughly 1.22 million BTC across 181 listed firms. Strategy (formerly MicroStrategy) remains the dominant buyer and holder, controlling approximately 845,050 BTC. Tokyo-listed Metaplanet ranks among the next-largest corporate stacks. As a group, these treasuries remain in a loss position at prevailing prices, creating a potential overhang if entities choose to de-risk.

    “A reclaim of $80.5K would put the treasuries back in profit and remove one layer of overhead supply; until then their entry is one more ceiling,” Glassnode added.

    ETF Inflows Rebound Yet Year-to-Date Deficit Persists

    Demand indicators beyond corporate treasuries paint a mixed picture. U.S.-listed spot Bitcoin ETFs have attracted billions of dollars in net inflows since early August, signaling a rebound in institutional appetite. However, data from SoSoValue shows these funds remain roughly $1 billion short of turning positive on a year-to-date basis, underscoring that the recent surge has only partially offset earlier outflows.

    Coinbase Premium Signals Weaker U.S. Spot Demand

    The Coinbase premium indicator, tracked by CoinGlass, has stayed mostly negative since May, with only a brief move into positive territory on September 5. A negative reading means Bitcoin is trading at a discount on Coinbase relative to Binance, suggesting that U.S.-based buyers are exhibiting weaker spot demand compared to traders on offshore venues. This divergence highlights a geographic split in buying pressure that could influence price discovery in the near term.

    Why This Matters

    The confluence of corporate treasuries sitting underwater, ETF flows still negative for the year, and a persistent negative Coinbase premium creates a layered resistance structure for Bitcoin. The $80.5K corporate cost basis acts as both a psychological and fundamental supply zone: if reclaimed, it could trigger profit-taking relief and remove a structural overhang; if rejected, it reinforces a ceiling that may cap near-term upside. Meanwhile, the ETF year-to-date deficit indicates that institutional capital has not yet fully recommitted after earlier drawdowns, and the Coinbase discount suggests U.S. participants remain cautious relative to global peers. Market watchers should monitor whether the August ETF inflow momentum can close the YTD gap and whether the Coinbase premium flips sustainably positive—both would signal broadening, conviction-led demand.

    Frequently Asked Questions

    How many Bitcoin do public companies hold in total?

    According to Bitcoin Treasuries, public companies hold approximately 1.22 million BTC across 181 listed firms.

    What is the Corporate Treasury Cost Basis and why is it important?

    The Corporate Treasury Cost Basis is the average entry price of corporate Bitcoin holdings, currently $80,500. It matters because the group is underwater at current prices; a reclaim would put them in profit and remove a layer of potential selling pressure.

    Are U.S. spot Bitcoin ETFs positive for the year?

    No. Despite billions in inflows since early August, SoSoValue data shows U.S. spot Bitcoin ETFs remain roughly $1 billion negative year-to-date.

  • Strive Acquires 469 Bitcoin, Lifting Treasury to 25,000 BTC

    Strive Acquires 469 Bitcoin, Lifting Treasury to 25,000 BTC

    Strive Adds 469 Bitcoin to Treasury, Holdings Reach 25,000 BTC

    Strive, Inc. (Nasdaq: ASST) acquired 469 bitcoin at an average price of approximately $77,954 per coin between September 8 and September 11, bringing its total corporate treasury to 25,000 BTC, according to a Form 8-K filed with the U.S. Securities and Exchange Commission on September 14. At the stated average price, the purchase represents roughly $36.6 million, inclusive of fees and expenses.

    The Purchase

    In the current report filed under Item 8.01, the Dallas-based asset-management and structured-finance firm disclosed that its bitcoin holdings increased from 24,531 coins as of September 4 to 25,000 as of September 11, a net increase of 469. The acquisition was reported alongside an update to cash and cash equivalents, which stood at approximately $204.2 million as of September 11. Strive, incorporated in Nevada and headquartered in Dallas, Texas, reports its bitcoin position in periodic SEC filings, signaling the asset’s growing weight on its balance sheet. The 8-K, a current report used to disclose material events between quarterly filings, was signed by Chief Executive Officer Matthew Cole.

    Bitcoin as the Treasury Benchmark

    The accumulation mirrors a wider shift among public companies treating bitcoin as a reserve asset. Strategy, the largest corporate bitcoin holder, recently resumed bitcoin purchases after a multi-week pause, while Strive has described bitcoin as its hurdle rate for capital deployment and says it is focused on growing bitcoin per share. Through its SEC-registered subsidiary Strive Asset Management, the firm manages more than $2.7 billion in assets. That framing places Strive among a small but expanding group of public companies actively building bitcoin treasuries rather than holding the asset passively.

    What Comes Next

    Corporate treasuries have continued to add bitcoin even as markets digest macroeconomic uncertainty. Metaplanet, another public company pursuing a bitcoin-treasury strategy, recently reshaped its capital structure to boost bitcoin per share. Strive’s next disclosure will show whether the firm keeps accumulating at a similar pace, and whether the broader cohort of corporate buyers sustains its recent momentum. The move keeps Strive among the public companies steadily converting a portion of their balance sheets into bitcoin, even as the wider market waits for the next catalyst.

  • Metaplanet Cuts Series 10 Stock Rights Pool 41% to Boost Bitcoin per Share

    Metaplanet Cuts Series 10 Stock Rights Pool 41% to Boost Bitcoin per Share

    Tokyo-listed Bitcoin treasury firm Metaplanet Inc. (TSE: 3350) announced on 11 September 2026 that its board of directors resolved to reduce the potential share pool under its 10th Series Stock Acquisition Rights by 41.1%, from 319,464,000 to 188,190,000 shares. The decision follows feedback from shareholders and capital market participants. Chief executive Simon Gerovich signed the notice on behalf of the company.

    Board Resolution Details

    The amendment cuts the number of shares underlying each stock acquisition right from 696 to 410, lowering the total potential pool by 131,274,000 shares. After deducting the portion already exercised, the remaining potential shares fall by 55.5%, from 236,640,000 to 105,366,000.

    Unvested rights now carry a new exercise restriction, with three equal portions becoming exercisable on 18 August 2029, 2030, and 2031 respectively. The company also withdrew its plan to transfer up to 90,000 rights to a long-term officer and employee incentive vehicle and will instead design a new compensation plan with a global consultant. The lock-up through 17 August 2031 and the JPY 10 exercise price remain unchanged. If all remaining rights are exercised, the company would receive roughly JPY 1.05 billion.

    Why Metaplanet Changed Course

    The board said it reconsidered the reference date used to calculate the shares underlying the rights, shifting it from 30 June 2026 to 1 September 2025. Metaplanet argued this better aligns the options with the period when its equity financings were executed at the highest premiums to net asset value, whereas later offerings including the September 2025 international placement were completed at more modest premiums. The company has drawn scrutiny as its floating option pool expanded alongside its share count while it pursued a strategy of raising equity to accumulate Bitcoin.

    Bitcoin Per Share Improves

    Because the fully diluted share count falls in line with the rights reduction, Metaplanet said its fully diluted Bitcoin per share improves accordingly. The company holds 43,000 BTC and reported roughly 0.0286646 BTC per effective diluted share, up from 0.0263554 as of 30 June, with the current-quarter BTC Yield at 8.8%.

    The disclosure shows one director holds 276,000 units, equal to 113,160,000 underlying shares after the cut, with 49,128,000 still exercisable. As Metaplanet expands its treasury strategy, it expects the amendment’s impact on current-year results to be immaterial.

  • Metaplanet CEO Surrenders $220M Stock Rights to Restore Investor Trust

    Metaplanet CEO Surrenders $220M Stock Rights to Restore Investor Trust

    Metaplanet Cuts Executive Rewards Amid Declining Bitcoin Per-Share Value

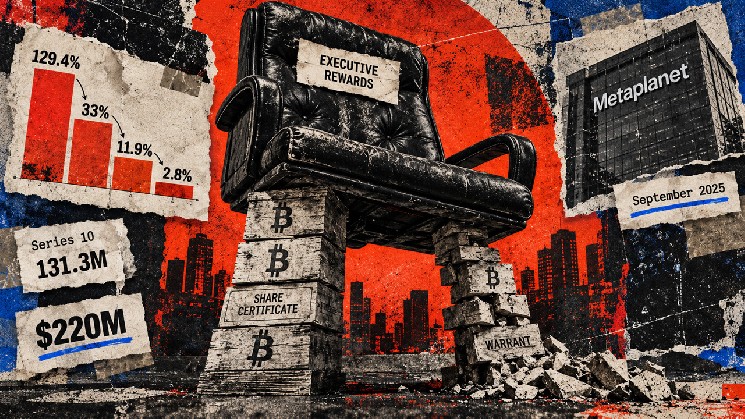
    Tokyo-listed Bitcoin treasury company Metaplanet announced on September 11 that it is resetting its Series 10 stock acquisition rights, eliminating more than $220 million in warrant value. The move cancels 131.3 million potential shares — representing 41.1% of the Series 10 pool — and reduces the remaining unexercised shares by 55.5% to approximately 105.4 million.

    Reset Draws a Line at September 2025 Financing

    The board’s review of previous equity financings focused on the premium to Bitcoin net asset value (NAV) at which shares were sold, the $BTC Yield generated, and the resulting shareholder value. Financings completed through mid-2025 were executed at multiples of Bitcoin NAV and produced substantial increases in Bitcoin per fully diluted share.

    That dynamic shifted with Metaplanet’s September 2025 international offering and subsequent capital raises, which closed at more modest premiums to NAV. While those transactions still added Bitcoin per share, the rate of accretion slowed dramatically.

    CEO Simon Gerovich stated that the September offering marked the point when capital raises became “less accretive” and the Series 10 structure began giving holders disproportionate value relative to existing shareholders.

    Sharp Decline in $BTC Yield Highlights the Problem

    Metaplanet’s $BTC Yield — a measure of Bitcoin accumulation per diluted share — reached 129.4% in the second quarter of 2025 as holdings jumped to 13,350 BTC from 4,046 BTC. The metric fell to 33% in the following quarter, 11.9% in the fourth quarter, and dropped to 2.8% in the first quarter of 2026.

    This declining accretion created a structural issue: the Series 10 pool was designed to adjust alongside Metaplanet’s diluted share count. As the company issued more stock to buy Bitcoin, management’s potential entitlement could expand even when each financing generated progressively less Bitcoin for existing shareholders.

    Investor Pressure Drives Deeper Cuts

    Metaplanet initially addressed the issue in August by eliminating the automatic adjustment mechanism and fixing the Series 10 pool at 319.5 million potential shares, using the June 30, 2026 share count as the reference point. However, investor criticism persisted.

    The board has now gone substantially further, replacing the June 2026 reference date with September 1, 2025 and resetting the conversion ratio to 410 shares per Series 10 right from 696.

    Matthew Sigel, VanEck’s head of digital assets research, called the revision a “meaningful concession,” saying it better aligns management with shareholders. He also noted that the revision would see the firm’s “CEO forfeit $123 million of controversial Series 10 comp.”

    Compensation Reset Boosts Bitcoin Per Share Without New Purchases

    The cancellation of 131.3 million potential shares raises Bitcoin per fully diluted share by approximately 8.8%, according to Gerovich. The company still holds 43,000 BTC; the improvement comes purely from a reduction in the share-count denominator.

    By extinguishing more than $220 million of warrant value, Metaplanet is effectively surrendering part of management’s future equity upside to improve existing investors’ Bitcoin-per-share position. The change also ties executive rewards more closely to the quality of future capital raises, acknowledging that an additional Bitcoin bought with newly issued stock does not provide the same shareholder benefit at every valuation.

    The board also abandoned a proposal to transfer up to 90,000 Series 10 rights into a new employee incentive pool. Those rights will be canceled as part of the 41% reduction.

    New Pay Structure Under Development

    The remaining Series 10 awards are being pushed further out: unvested rights will become exercisable in three equal portions in 2029, 2030, and 2031, while shares received through exercise remain subject to the existing five-year lock-up. This timeline gives the board time to decide which metrics — such as $BTC Yield, Bitcoin per diluted share, or NAV accretion — should determine future rewards as the treasury strategy matures.

    Metaplanet is also expanding internationally, including a pending acquisition of a controlling stake in Nasdaq-listed Super League Enterprise and the establishment of a Hong Kong subsidiary, Metaplanet Asset Management Asia Limited. The company said it will work with a leading global compensation consultant and other external advisers on a new incentive program for employees and future hires.

    CEO Gerovich Outlines Next Steps

    Gerovich said:

    “We will develop a new plan in consultation with a leading global compensation consultant to incentivize new hires. We will share details as the design progresses.”

    Metaplanet’s next compensation plan will reveal whether the September 10 concession simply reduced an unusually large legacy award or permanently changed how executives are rewarded for growing the company’s Bitcoin stack.

  • Bitcoin-Focused Metaplanet Transfers Hundreds of BTC to Coinbase: Is a Sell-Off Coming?

    Bitcoin-Focused Metaplanet Transfers Hundreds of BTC to Coinbase: Is a Sell-Off Coming?

    Metaplanet, a Japan-based company focused on Bitcoin, transferred 2,400 BTC worth approximately $186 million to Coinbase Prime within a three-hour period, according to on-chain analytics platform Lookonchain data dated August 31.

    The transaction is among Metaplanet’s recent large-scale Bitcoin movements. The transferred coins reportedly came from the company’s holdings of approximately 43,000 BTC, acquired at an average price of $96,191 per Bitcoin. Those assets are estimated to be worth around $3.48 billion.

    Metaplanet’s Bitcoin transfer draws market attention

    Large Bitcoin transfers involving companies and institutional investors are closely watched because deposits to centralized exchanges or institutional trading platforms can indicate preparations for a potential sale. However, Coinbase Prime also provides custody, liquidity management, and other institutional services. As a result, the transfer alone does not confirm that Metaplanet sold any Bitcoin.

    Metaplanet is one of the most prominent institutional investors to place Bitcoin at the center of its corporate treasury strategy. The company has continued expanding its cryptocurrency reserves through regular Bitcoin purchases as part of its long-term treasury management approach.

    Following the latest transfer, market participants are monitoring how the 2,400 BTC will be used on Coinbase Prime. If the Bitcoin is sold, the transaction could add supply and increase selling pressure in the market. Alternatively, the transfer may have been made solely for institutional custody or liquidity management.

    Metaplanet’s subsequent on-chain activity could offer further insight into whether the company plans to continue accumulating Bitcoin or intends to reduce part of its existing holdings.

    This is not investment advice.

  • Metaplanet Sells Bitcoin in Latest $237 Million Transaction

    Metaplanet Sells Bitcoin in Latest $237 Million Transaction

    Metaplanet Transfers $237 Million in Bitcoin to Coinbase Prime, Raising Sell-Off Concerns

    Japan-based Bitcoin treasury firm Metaplanet has transferred approximately $237 million worth of Bitcoin to Coinbase Prime, prompting speculation that the company may be preparing to sell part of its holdings as the broader cryptocurrency market slows.

    Metaplanet Moves Bitcoin to Coinbase Prime

    According to the latest data shared today, Metaplanet sent the large Bitcoin deposit to Coinbase Prime, the leading U.S. cryptocurrency exchange’s institutional trading platform.

    The transaction has drawn attention from market participants because it comes as Bitcoin’s recent rally loses momentum. While Metaplanet is known for making regular Bitcoin purchases, the size and timing of this transfer have raised questions about whether the firm is becoming more cautious.

    Metaplanet has not specified the reason for the transfer. However, some market participants believe the move could represent an attempt to sell a portion of the company’s Bitcoin holdings.

    Transfers to cryptocurrency platforms such as Coinbase Prime do not necessarily indicate that Bitcoin has been sold. The assets could also be moved for custody, trading, or other operational purposes. Nevertheless, the scale of the transaction has fueled speculation about a potentially bearish move by Metaplanet.

    Is Metaplanet Taking Bitcoin Profits?

    The Bitcoin transfer comes as investors have started trading more cautiously, with some market participants selling assets to lock in gains from the recent price rally.

    Bitcoin has since pulled back from its upward trend and is trading in negative territory. The decline, combined with increased profit-taking activity, has led to speculation that Metaplanet may have moved the assets to secure profits.

  • Metaplanet Moves $108 Million in Bitcoin to Coinbase Prime, Raising Selloff Concerns

    Metaplanet Moves $108 Million in Bitcoin to Coinbase Prime, Raising Selloff Concerns

    Bitcoin treasury firm Metaplanet is back on investors’ radar after moving 1,350 BTC into Coinbase Prime, raising concerns about a potential sell-off.

    The transfer comes as Bitcoin continues to target a successful break above the $80,000 resistance level. The movement of the coins to Coinbase Prime has fueled speculation over whether Metaplanet could be preparing to sell part of its Bitcoin holdings.