Tag: DeFi lending

  • EU faces September 30 deadline to decide future of DeFi loans

    EU faces September 30 deadline to decide future of DeFi loans

    Key Highlights

    • The European Banking Authority has asked the European Commission to examine new MiCA rules for crypto firms that connect customers to DeFi lending protocols, recommending a cost-benefit analysis of potential duties for intermediated borrowing and lending.
    • The EBA identified two possible regulatory changes: adding intermediated crypto borrowing and lending to MiCA’s list of CASP services, and setting requirements for CASPs facilitating access to DeFi lending through interfaces or products.
    • The Commission’s targeted consultation closes on September 30, 2024, and may accompany its report with a legislative proposal if warranted, though no new rules are currently enacted.

    EBA Urges Commission Review of MiCA Rules for DeFi Access Points

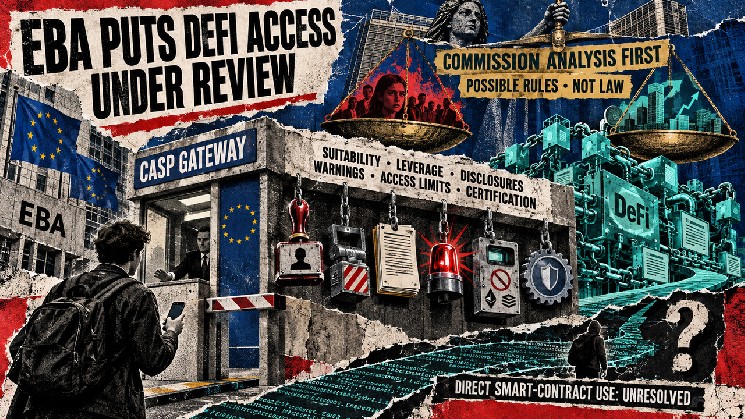
    The European Banking Authority (EBA) has formally requested that the European Commission examine potential new rules under the Markets in Crypto-Assets (MiCA) regulation targeting crypto-asset service providers (CASPs) that connect customers to decentralized finance (DeFi) lending protocols. In its September 24 response to the Commission’s consultation, the regulator called for a cost-benefit analysis of possible duties for intermediated borrowing and lending, specifically focusing on CASPs that give clients access to DeFi lending through interfaces or product offerings. The EBA emphasized that consumer risks—including incomplete information about fees, yields, collateral changes, leverage amplifying losses, and risks from commingling, outages, hacks, and poor recordkeeping—prompted its call to assess the issue.

    Mapping CASP Roles in DeFi Lending

    The EBA’s review maps potential CASP roles in DeFi lending while noting that direct smart-contract use remains unresolved. The authority identified two distinct regulatory pathways for the Commission’s consideration. The first would add intermediating crypto borrowing and lending to MiCA’s existing list of CASP services. The second would establish specific requirements for CASPs that facilitate access to DeFi lending protocols, whether through a user interface or a product providing exposure to DeFi yields. The Commission would need to weigh the scale of these activities, the extent of retail participation, and the materiality of risks before deciding whether to pursue legislation.

    Proposed Safeguards and Access Restrictions

    Among the six DeFi lending safeguards proposed for Commission analysis, the EBA suggested suitability tests to assess whether a customer should participate, leverage caps, and fuller disclosures to address borrowing risks. For DeFi access specifically, the regulator floated extra warnings that activity through a truly decentralized protocol may lack regulatory safeguards, as well as certification of lending protocols for resilience to cyberattacks. A separate option concerns tokens whose issuers lack required MiCA authorization: the EBA said CASPs could be prohibited from intermediating or facilitating borrowing and lending involving assets that meet MiCA’s definition of an asset-referenced or e-money token but have no authorized issuer.

    Why This Matters

    The EBA’s recommendations signal a potential regulatory boundary forming around the “front-end” access points to DeFi—wallets, apps, and structured products that bridge retail users to on-chain lending protocols like Aave. While the underlying protocols continue to execute loans autonomously via smart contracts, the firms controlling the user-facing layer could face new suitability checks, disclosure requirements, and leverage restrictions. The distinction between an interface providing protocol access, a service intermediating a loan, and a product offering DeFi exposure will be critical: any future measure must translate these categories into clear obligations for firms and customers. The Commission’s consultation closes on September 30, 2024, at 11:59 p.m. Central European Summer Time, and its subsequent report—potentially accompanied by a legislative proposal—will determine whether these proposals advance into binding law. Until then, the current MiCA framework remains unchanged for DeFi lending access.

    Frequently Asked Questions

    Does the EBA’s response create any new rules for DeFi lending today?

    No. The EBA’s response is a recommendation to the European Commission to examine potential legislation. It does not enact any new lending rules or change current MiCA requirements. The Commission must still conduct its analysis, weigh the scale and risks of intermediated DeFi access, and decide whether to pursue a legislative proposal.

    How would the proposed rules affect direct smart-contract interaction with DeFi protocols?

    The EBA’s review explicitly notes that direct smart-contract use remains unresolved. The proposals target CASPs that facilitate access through interfaces or products—not users interacting directly with protocol smart contracts. Future lawmakers would still need to define the scope of “facilitating access” and decide how to treat direct on-chain interaction.

    What specific consumer risks did the EBA cite to justify its recommendations?

    The EBA highlighted incomplete information about fees, yields, and collateral requirement changes; leverage amplifying losses; risks from commingling, outages, hacks, and poor recordkeeping; absence of creditworthiness checks; and possible over-indebtedness as the key consumer harms driving its call for regulatory examination.

  • Maple Finance Unveils Expanded Allocation Engine

    Maple Finance Unveils Expanded Allocation Engine

    Maple Finance Expands Allocation Strategies to Meet Rising Institutional Demand

    Maple Finance has published a new memo outlining enhanced allocation strategies designed specifically for institutional lenders. The announcement signals growing confidence from partners who already entrust the platform with billions in lending capital, further cementing Maple’s position in the decentralized finance (DeFi) lending landscape.

    Strategic Response to Institutional DeFi Growth

    The memo, released by @syrupsid, details the necessity of expanding Maple’s allocation engine to accommodate surging institutional demand. By widening the range of available capital allocation strategies, the platform aims to facilitate broader access to diverse lending options while maintaining the robust infrastructure that has attracted billions in institutional commitments.

    This development arrives as the broader crypto market displays mixed momentum across major assets. Despite the absence of significant price movements in current data, Maple’s proactive approach to scaling its lending infrastructure highlights a strategic focus on long-term institutional adoption rather than short-term market fluctuations.

    Key Developments in Maple’s Institutional Offering

    • New allocation strategies added for institutional lenders seeking diversified capital deployment
    • Expanded allocation engine designed to handle increased volume and strategy variety
    • Billions in existing institutional lending under management, demonstrating established trust
    • Focus on corporate-scale loans that require the infrastructure Maple provides

    Market Context and Regulatory Landscape

    Maple Finance operates as a specialized DeFi platform connecting institutional lenders with borrowers requiring larger loan sizes typical in corporate finance. As regulatory frameworks governing financial services continue to evolve, the platform’s ability to adapt its allocation strategies becomes essential for maintaining compliance while meeting market demands.

    The jurisdictional considerations surrounding decentralized lending practices necessitate flexible infrastructure that can accommodate varying regulatory requirements across different markets—a factor that likely influenced the timing and scope of these strategic enhancements.

    Implications for DeFi Lending Ecosystem

    Market observers should monitor how Maple’s expanded strategies influence capital flows within the institutional DeFi sector. The platform’s move to accommodate growing demand may catalyze increased transaction volumes and deeper institutional participation, potentially setting a precedent for how other DeFi lending protocols approach scalability and institutional onboarding.

    As these new allocation strategies roll out, the market response will provide valuable signals about the trajectory of decentralized institutional lending and whether enhanced infrastructure translates to sustained capital inflow and user engagement growth.

    This article is for informational purposes only and should not be considered financial advice.

  • Curve’s Soft Liquidation Model Helps Borrowers Survive Market Drawdowns

    Curve’s Soft Liquidation Model Helps Borrowers Survive Market Drawdowns

    Curve Finance Soft Liquidation Data Reveals Borrowers Recover After Weeks in Liquidation

    New on-chain data from Curve Finance shows that hundreds of borrowers spent days or weeks in a partially liquidated state before their positions recovered, challenging the conventional assumption that liquidation equals immediate loss.

    How Soft Liquidation Works on Curve

    Unlike traditional hard liquidation — where a position is closed outright once collateral value drops below a threshold — Curve’s crvUSD lending markets use a soft liquidation mechanism. When a borrower’s collateral value falls into a specific price band, the protocol automatically converts a portion of that collateral into crvUSD stablecoins to reduce debt.

    The unusual finding is that these conversions happen while the loan remains open. A position can stay partly liquidated for extended periods and still recover if market prices reverse.

    Curve Finance Market Context

    Curve Finance operates as a major decentralized finance (DeFi) protocol specializing in stablecoin swaps and lending. According to DefiLlama data:

    • Total deposits: Approximately $1.35 billion
    • 30-day DEX volume: Roughly $3.4 billion
    • 30-day protocol fees: About $4.3 million
    • 30-day protocol revenue: Approximately $1.15 million
    • Active loans outstanding: Roughly $46 million

    Costs and Risks Remain for Borrowers

    Soft liquidation is not cost-free. The data indicates borrowers can still lose money through:

    • Trading fees during collateral conversion
    • Rebalancing costs
    • Accrued interest
    • Repeated price movements in both directions

    A position can still progress to hard liquidation if adverse price action continues. Even when prices recover, the borrower may not return to their original position due to accumulated costs and slippage.

    Key Takeaway for DeFi Lending

    Curve’s data establishes that on this system, crossing into liquidation does not mean a loan is dead. Hundreds of borrowers experienced extended periods in soft liquidation — days or weeks — before their positions recovered, demonstrating a materially different risk profile compared to traditional lending protocols.

  • Aave V4 Deposits Surge to $806M on 30% Weekly Gain

    Aave V4 Deposits Surge to $806M on 30% Weekly Gain

    Aave V4 Deposits Surge 30% in a Week to Record $806 Million

    Aave’s Version 4 protocol has reached a new all-time high in user deposits, hitting $806 million according to the platform’s live onchain dashboard. The figure represents a 30% increase over the past seven days and extends a steep growth trajectory that began in mid‑August.

    Rapid August Milestones

    Separate protocol announcements tracked the ascent: V4 deposits crossed $500 million on August 19, breached $600 million two days later, and surpassed $800 million six days after that. A further update noted that Ethereum‑based V4 deposits alone exceeded $500 million on August 25. EtherFi Cash has emerged as the second‑largest market within the V4 ecosystem.

    Borrowing Activity Grows Alongside Deposits

    The dashboard shows $216 million in active loans across V4. In the EtherFi Cash market specifically, Aave measured $62 million of active loans where weETH collateral backs WETH borrowing at 92% utilization.

    Deployment Breakdown by Network and Market

    V4 is currently deployed on Ethereum, Optimism, and Avalanche. The largest market by deposits is Ethereum Core at $378 million, followed by EtherFi Cash on Optimism at $257 million. Ethereum Global Dollar holds $75 million, Ethereum Prime $63 million, while Avalanche Core and Ethereum Plus account for $18 million and $15 million respectively.

    Asset Composition of Deposits

    The deposit mix is led by weETH at $97 million and USDG at $90 million. WETH and USDC each represent $81 million, followed by liquidETH ($77 million), liquidUSD ($58 million), and WBTC ($54 million).

    V3 Still Dominates Total Liquidity

    Despite V4’s rapid growth, Aave’s V3 protocol retains a far larger deposit base. The equivalent V3 dashboard shows $31 billion in user deposits, with Ethereum Core alone holding $25 billion.

    Architectural Shift: Hub‑and‑Spoke vs. Market‑per‑Pool

    The two versions organize liquidity differently. According to Aave’s documentation, V4 replaces V3’s market‑per‑pool design with a hub‑and‑spoke system. Hubs consolidate liquidity and accounting, while spokes apply separate borrowing rules and risk limits to particular markets.

    EtherFi Cash Targets $500 Million Lending Capacity

    On August 27, TokenLogic reported that the EtherFi Cash market had been live for two weeks and was progressing toward a $500 million lending‑capacity target.