Tag: Crypto Asset Service Providers

  • EU faces September 30 deadline to decide future of DeFi loans

    EU faces September 30 deadline to decide future of DeFi loans

    Key Highlights

    • The European Banking Authority has asked the European Commission to examine new MiCA rules for crypto firms that connect customers to DeFi lending protocols, recommending a cost-benefit analysis of potential duties for intermediated borrowing and lending.
    • The EBA identified two possible regulatory changes: adding intermediated crypto borrowing and lending to MiCA’s list of CASP services, and setting requirements for CASPs facilitating access to DeFi lending through interfaces or products.
    • The Commission’s targeted consultation closes on September 30, 2024, and may accompany its report with a legislative proposal if warranted, though no new rules are currently enacted.

    EBA Urges Commission Review of MiCA Rules for DeFi Access Points

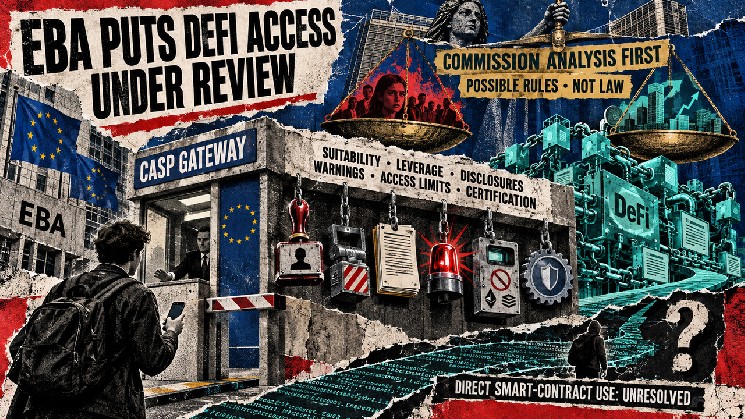
    The European Banking Authority (EBA) has formally requested that the European Commission examine potential new rules under the Markets in Crypto-Assets (MiCA) regulation targeting crypto-asset service providers (CASPs) that connect customers to decentralized finance (DeFi) lending protocols. In its September 24 response to the Commission’s consultation, the regulator called for a cost-benefit analysis of possible duties for intermediated borrowing and lending, specifically focusing on CASPs that give clients access to DeFi lending through interfaces or product offerings. The EBA emphasized that consumer risks—including incomplete information about fees, yields, collateral changes, leverage amplifying losses, and risks from commingling, outages, hacks, and poor recordkeeping—prompted its call to assess the issue.

    Mapping CASP Roles in DeFi Lending

    The EBA’s review maps potential CASP roles in DeFi lending while noting that direct smart-contract use remains unresolved. The authority identified two distinct regulatory pathways for the Commission’s consideration. The first would add intermediating crypto borrowing and lending to MiCA’s existing list of CASP services. The second would establish specific requirements for CASPs that facilitate access to DeFi lending protocols, whether through a user interface or a product providing exposure to DeFi yields. The Commission would need to weigh the scale of these activities, the extent of retail participation, and the materiality of risks before deciding whether to pursue legislation.

    Proposed Safeguards and Access Restrictions

    Among the six DeFi lending safeguards proposed for Commission analysis, the EBA suggested suitability tests to assess whether a customer should participate, leverage caps, and fuller disclosures to address borrowing risks. For DeFi access specifically, the regulator floated extra warnings that activity through a truly decentralized protocol may lack regulatory safeguards, as well as certification of lending protocols for resilience to cyberattacks. A separate option concerns tokens whose issuers lack required MiCA authorization: the EBA said CASPs could be prohibited from intermediating or facilitating borrowing and lending involving assets that meet MiCA’s definition of an asset-referenced or e-money token but have no authorized issuer.

    Why This Matters

    The EBA’s recommendations signal a potential regulatory boundary forming around the “front-end” access points to DeFi—wallets, apps, and structured products that bridge retail users to on-chain lending protocols like Aave. While the underlying protocols continue to execute loans autonomously via smart contracts, the firms controlling the user-facing layer could face new suitability checks, disclosure requirements, and leverage restrictions. The distinction between an interface providing protocol access, a service intermediating a loan, and a product offering DeFi exposure will be critical: any future measure must translate these categories into clear obligations for firms and customers. The Commission’s consultation closes on September 30, 2024, at 11:59 p.m. Central European Summer Time, and its subsequent report—potentially accompanied by a legislative proposal—will determine whether these proposals advance into binding law. Until then, the current MiCA framework remains unchanged for DeFi lending access.

    Frequently Asked Questions

    Does the EBA’s response create any new rules for DeFi lending today?

    No. The EBA’s response is a recommendation to the European Commission to examine potential legislation. It does not enact any new lending rules or change current MiCA requirements. The Commission must still conduct its analysis, weigh the scale and risks of intermediated DeFi access, and decide whether to pursue a legislative proposal.

    How would the proposed rules affect direct smart-contract interaction with DeFi protocols?

    The EBA’s review explicitly notes that direct smart-contract use remains unresolved. The proposals target CASPs that facilitate access through interfaces or products—not users interacting directly with protocol smart contracts. Future lawmakers would still need to define the scope of “facilitating access” and decide how to treat direct on-chain interaction.

    What specific consumer risks did the EBA cite to justify its recommendations?

    The EBA highlighted incomplete information about fees, yields, and collateral requirement changes; leverage amplifying losses; risks from commingling, outages, hacks, and poor recordkeeping; absence of creditworthiness checks; and possible over-indebtedness as the key consumer harms driving its call for regulatory examination.
  • South Africa Moves to Regulate Cross-Border Crypto Transfers

    South Africa Moves to Regulate Cross-Border Crypto Transfers

    Key Highlights

    • South Africa’s draft crypto cross-border framework imposes strict daily (ZAR 5,000) and monthly (ZAR 25,000) limits on person-to-person remittances via crypto rails, while standard Web3 transfers require individuals to use existing SDA (R2 million) or FCA (R10 million) allowances with SARS tax clearance.
    • Crypto Asset Service Providers (CASPs) must obtain separate cross-border authorization from the SARB’s Financial Surveillance Department (FinSurv) beyond their FSCA license, conduct enhanced due diligence, report all cross-border flows, and enforce traveler declarations—with penalties up to ZAR 1 million fine and five years’ imprisonment.
    • Industry stakeholders warn the rules could freeze an estimated R2.2 billion in corporate and private equity, drive innovation underground, raise remittance costs, and trigger legal challenges, arguing the state neglected consultation during drafting.

    South Africa Unveils Restrictive Draft Framework for Crypto Cross-Border Transfers

    South Africa has published draft regulatory requirements governing cryptocurrency cross-border transfers, marking a significant escalation in the oversight of digital asset flows into and out of the continent’s most industrialized economy. The framework, which complements the broader Capital Flow Management Regulations slated for 2026, introduces granular transaction caps, enhanced licensing mandates for service providers, and stringent reporting obligations that have drawn sharp criticism from local crypto executives and industry bodies.

    Tiered Limits for Remittances and Web3 Transfers

    The draft framework delineates two primary categories of cross-border crypto activity. Under Person-to-Person Remittances, individual users face a daily transaction ceiling of ZAR 5,000 and a monthly aggregate limit of ZAR 25,000 when sending money abroad using cryptocurrency rails. For Standard Web3 Transfers—covering movements from both custodial and non-custodial wallets—individuals over 18 may only move crypto offshore by drawing on their existing regulatory allowances: the R2 million Single Discretionary Allowance (SDA) or the R10 million Foreign Capital Allowance (FCA). Utilization of the FCA further requires a tax clearance certificate from the South African Revenue Service (SARS).

    Compliance Burden Intensifies for CASPs

    Local Crypto Asset Service Providers (CASPs), already licensed by the Financial Sector Conduct Authority (FSCA), must now secure a separate cross-border authorization from the South African Reserve Bank’s Financial Surveillance Department (FinSurv). The new obligations include intensive customer due diligence, mandatory verification of the source of funds, and real-time reporting of all cross-border inflows and outflows to FinSurv. Additionally, CASPs are required to enforce a declaration regime for travelers carrying digital assets above specified thresholds. Non-compliance carries severe penalties: fines of up to ZAR 1,000,000 and imprisonment of up to five years.

    Industry Backlash and Frozen Capital

    Digital asset companies argue the drafting process excluded meaningful stakeholder consultation. Executives contend the proposed rules disproportionately target blockchain-based settlement technology that reduces transaction costs, and warn that conflating stablecoins with volatile cryptocurrencies under heavy capital flight restrictions will drive innovation underground, inflate remittance fees, and cripple businesses’ ability to manage treasury operations efficiently across Africa. Since the draft’s release, an estimated R2.2 billion in corporate and private equity has reportedly been frozen as market participants await regulatory clarity. Several firms have signaled potential legal action if the framework is enacted in its current form.

    Why This Matters

    South Africa’s approach signals a pivot from its earlier, relatively permissive stance—evidenced by the FSCA’s 2022 declaration of crypto as a financial product and the licensing of over 200 CASPs—toward a capital-control-centric model that prioritizes exchange-rate stability and tax compliance over fintech innovation. The framework aligns with the National Treasury’s forthcoming Capital Flow Management Regulations and reflects growing central bank anxiety over the 7.8 million South Africans estimated to hold crypto, a figure that has surged despite regulatory uncertainty. For multinational firms and remittance corridors linking South Africa to the rest of the continent, the new caps and reporting layers could raise operational costs and fragment liquidity. Meanwhile, institutional entrants such as Ripple’s custody partnership with Absa may face friction onboarding corporate clients if cross-border authorization bottlenecks persist. The coming months will test whether the SARB and Treasury refine the draft in response to industry feedback or proceed with a regime that could push significant volumes into unregulated peer-to-peer channels.

    Frequently Asked Questions

    What are the daily and monthly limits for person-to-person crypto remittances under the draft rules?
    Individuals may send a maximum of ZAR 5,000 per day and ZAR 25,000 per month abroad using cryptocurrency rails under the Person-to-Person Remittance category.
    Do CASPs need a new license to facilitate cross-border crypto transfers?
    Yes. Beyond their existing FSCA license, CASPs must obtain a separate cross-border authorization from the SARB’s Financial Surveillance Department (FinSurv) and comply with enhanced due-diligence, source-of-funds verification, and transaction-reporting requirements.
    What penalties apply for non-compliance with the draft cross-border framework?
    Violations can attract fines of up to ZAR 1,000,000 and imprisonment of up to five years, applicable to both service providers and individuals who fail to declare digital assets above the prescribed traveler thresholds.